
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CMS Energy Stock: Is CMS Underperforming the Utility Sector?
With a market cap of $20.8 billion, CMS Energy Corporation (CMS) is a Michigan-based energy company operating through three segments: Electric Utility, Gas Utility, and NorthStar Clean Energy. The company generates, distributes, and sells electricity from diverse sources while also providing natural gas through an extensive network of transmission, storage, and distribution infrastructure.
Companies valued at $10 billion or more are generally considered “large-cap” stocks, and CMS Energy fits this criterion perfectly. Serving approximately 1.9 million electric and 1.8 million gas customers, CMS Energy also develops and operates renewable energy projects through NorthStar Clean Energy.
Shares of the Jackson, Michigan-based company have dipped 17.6% from its 52-week high of $80.36. The stock has fallen 9.7% over the past three months, a steeper decline than the State Street Utilities Select Sector SPDR ETF's (XLU) 6.2% decrease during the same period.
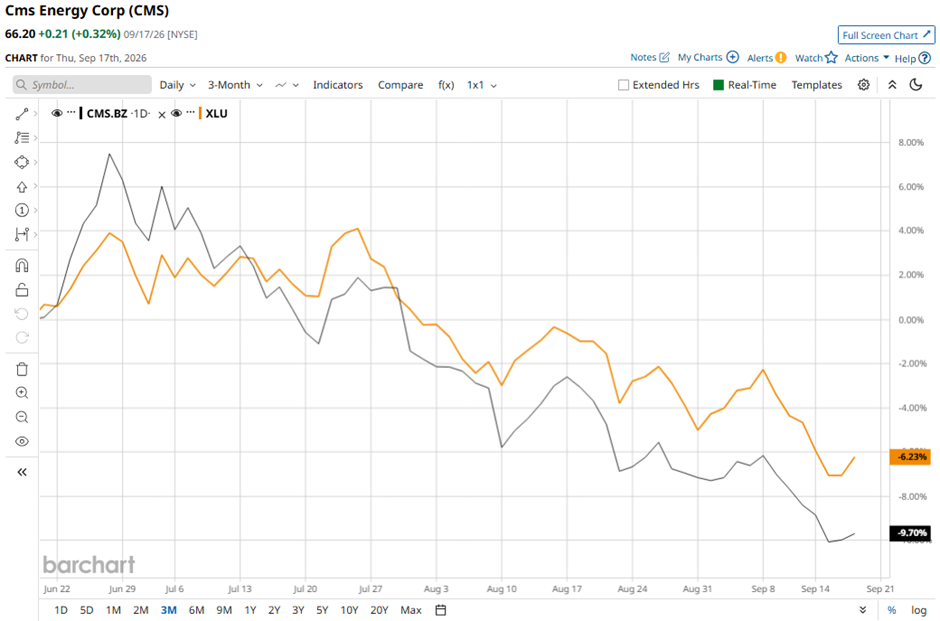
The energy company stock is down 5.3% on a YTD basis, lagging behind XLU's 2.3% decline. Longer term, the stock has dropped 5.9% over the past 52 weeks, compared to XLU's 1.2% dip over the same time frame.
CMS stock has been trading below its 50-day and 200-day moving averages since August.
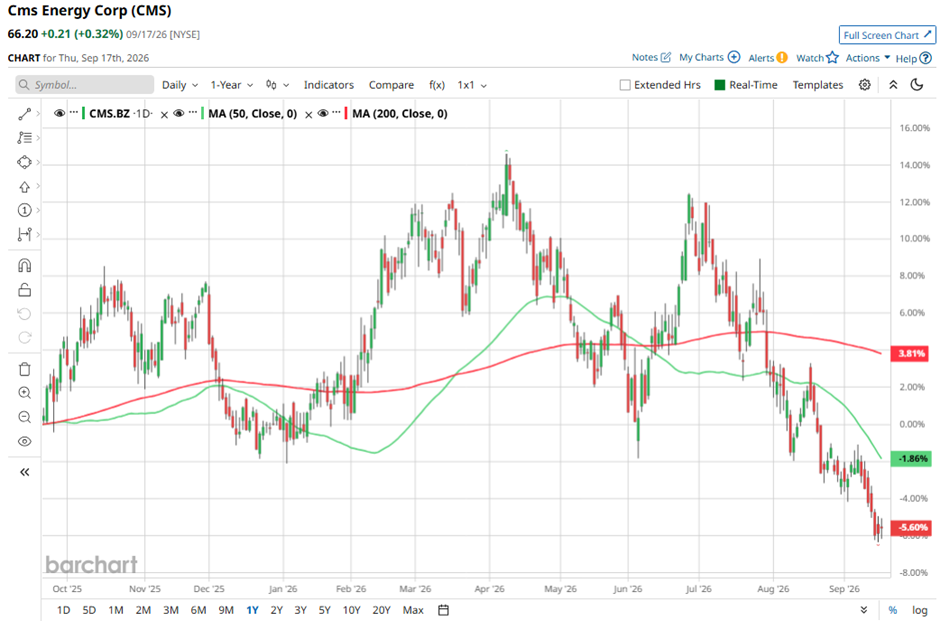
CMS Energy released its Q2 2026 results on Jul. 28. The company decided to exit non-utility renewables development and a weaker-than-expected 2027 earnings outlook. The company forecast 2027 adjusted EPS of $4.08 - $4.17, with the $4.13 midpoint below analysts’ estimate, while restructuring NorthStar Clean Energy and shifting focus toward its regulated utility business. Although Q2 adjusted EPS of $0.37 beat the estimate, net income fell 40.3% to $120 million and operating expenses rose 2.6% to $1.56 billion.
In comparison, rival WEC Energy Group, Inc. (WEC) has shown a less pronounced decline than CMS stock. WEC stock has fallen marginally on a YTD basis and 4.2% over the past 52 weeks.
Despite CMS stock’s underperformance over the past year, analysts are moderately optimistic with a consensus rating of "Moderate Buy" from 16 analysts. The mean price target of $79.23 is a premium of 19.7% to current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.