
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sea (SE) Stock May Trade At A Premium Given Its Earnings
Sea has given shareholders a wild ride, and the question now is whether the current US$101.27 share price still lines up with the earnings that support it. After sharp swings in recent years, a key issue is whether the stock you see today is being priced in a way that matches what the business is actually earning.
- Over the past 3 years, Sea has delivered a share price gain of about 181.7%. That places greater focus on whether its earnings story can support that kind of performance.
- The group relies heavily on converting its digital businesses into consistent profits and cash flow. This can shape how much investors are prepared to pay for each dollar of earnings.
- There is a second opinion on Sea worth weighing. See what analysts think Sea's shares could be worth.
For investors, the debate is whether Sea's current valuation is adequately supported by the earnings it is generating today and is expected to produce in the future.
If you want to see how Sea compares with other opportunities where earnings and price are under the microscope, a focused stock screen built around 29 high quality undervalued stocks can be a useful next step.
Is Sea Getting Expensive on Earnings?
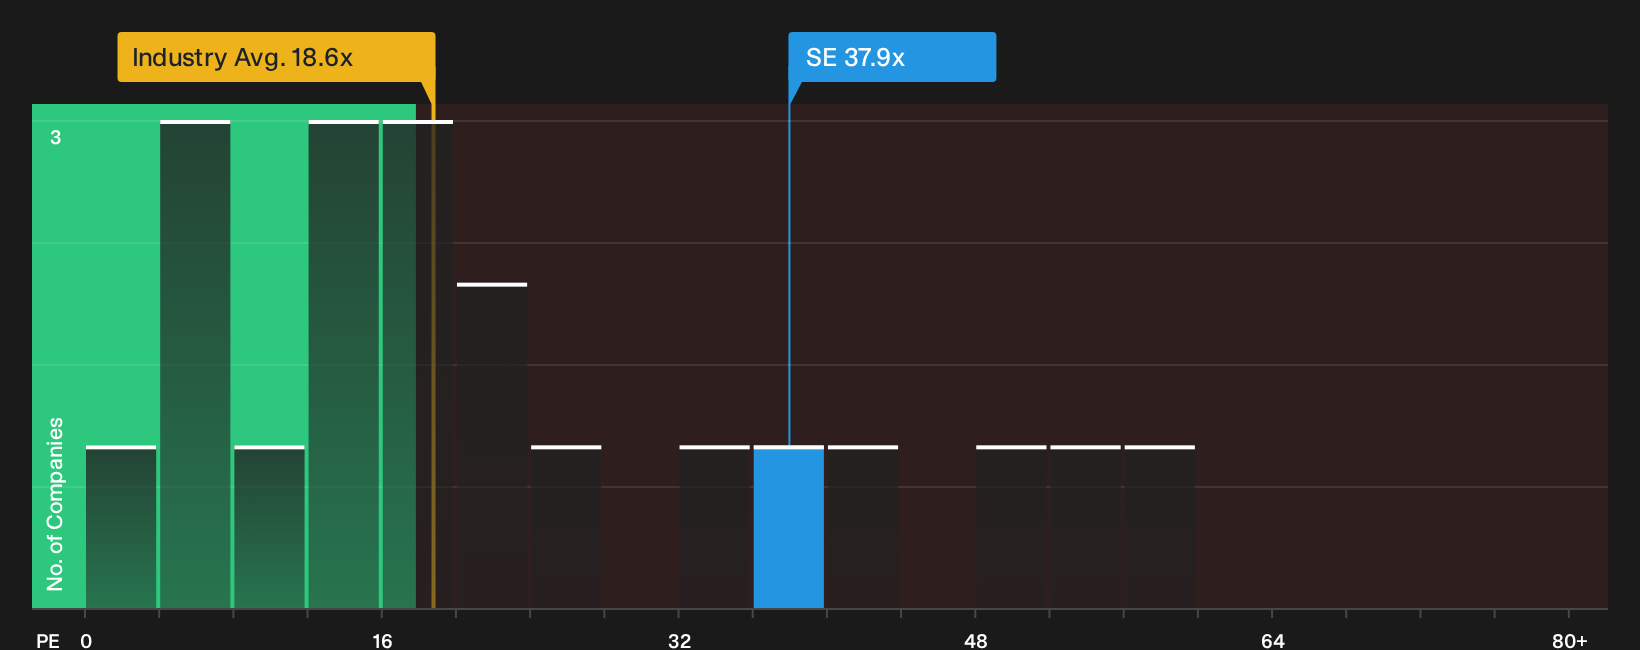
The P/E ratio is a useful lens for Sea because earnings have become a meaningful reference point for what buyers are willing to pay per share. At roughly 37.9x earnings, the stock trades well above the Multiline Retail industry average of about 18.6x, which already indicates that investors are paying a sizeable premium for each dollar of profit compared with more traditional retailers.
Compared with a broad peer group, where Sea screens around a 24.2x P/E, the gap remains wide. A valuation model that adjusts for Sea's growth profile, margins, size and risk points to a lower P/E as a more tailored anchor, so the current 37.9x level appears expensive relative to that benchmark. Anyone considering the shares has to decide whether the business quality and future earnings profile justify paying that kind of premium multiple. Explore the numbers behind Sea's P/E valuation.
The Sea Narrative: What Would Justify Today's Price?
Sea Narratives on Simply Wall St sit between the current P/E puzzle and the real world assumptions that would need to hold on growth, margins and earnings for the stock to be worth materially more or less than today. Each one sets out Sea's implied fair value as a thesis about how the business might perform that you can watch over time, rather than a single frozen snapshot.
One of the top community narratives on Sea: 36% undervalued
"Investments in logistics technology, AI-driven ad tech, and content ecosystem improvements are enhancing customer experience, boosting take rates, and lowering per-order costs..."
Discover why this Narrative puts Sea at 36% undervalued.
One more Sea question that could change how you see the stock
Everything so far has focused on what Sea looks like right now, but there is a separate set of analyst projections a few years out that gives you another reference point to compare with today's price and earnings picture. Explore where analysts expect Sea to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com