
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Japan Bank Stocks Facing A New Rate Era With 3 Regional Lenders In Focus
Japanese bank stocks just stepped into a different world. The Bank of Japan has lifted its policy rate to about 1.25% for the first time since the mid-1990s, and markets are already rearranging the winners and losers as funding costs, deposit pricing and lending margins all shift. This article walks through 3 Japan-focused financial stocks that appear especially exposed to this new rate path, and why that may be important context for your portfolio decisions.
The three stocks below are a starting sample. The full screen surfaced 13 more Japanese domestic-focused financial companies with equally compelling stories that are not covered here. To go straight to the broader opportunity set, use the Japanese Domestic-Focused Banks and Financials screener to analyze, compare, and identify your highest conviction ideas.
Gunma Bank (TSE:8334)
Overview: Gunma Bank is a regional Japanese lender focused on domestic deposits, loans and related financial services that are directly exposed to higher local interest rates.
Operations: Gunma Bank generates about ¥228.7b from banking and ¥37.0b from leasing, with all reported revenue of roughly ¥199.3b coming from Japan.
Market Cap: ¥1.11t
Gunma Bank is a pure play on Japanese rate normalisation, with most earnings tied to domestic lending, deposits and securities income. Its current valuation reflects stronger recent earnings and revenue figures alongside only moderate ROE. As a result, the investment case for this regional lender now depends on how one unseen pressure may influence future net interest margins.
Those pressure points start to show up clearly in the 3 key rewards and 1 important warning sign, where Gunma Bank’s rate upside and margin risk sit side by side, waiting for a catalyst.

Hokuhoku Financial Group (TSE:8377)
Overview: Hokuhoku Financial Group is a regional Japanese banking group that concentrates on serving domestic households and smaller businesses through loans, deposits and related financial services.
Operations: Hokuhoku Financial Group generates about ¥130.4b from The Hokuriku Bank and ¥93.5b from Hokkaido Bank, with ¥22.0b segment adjustments.
Market Cap: ¥998.0b
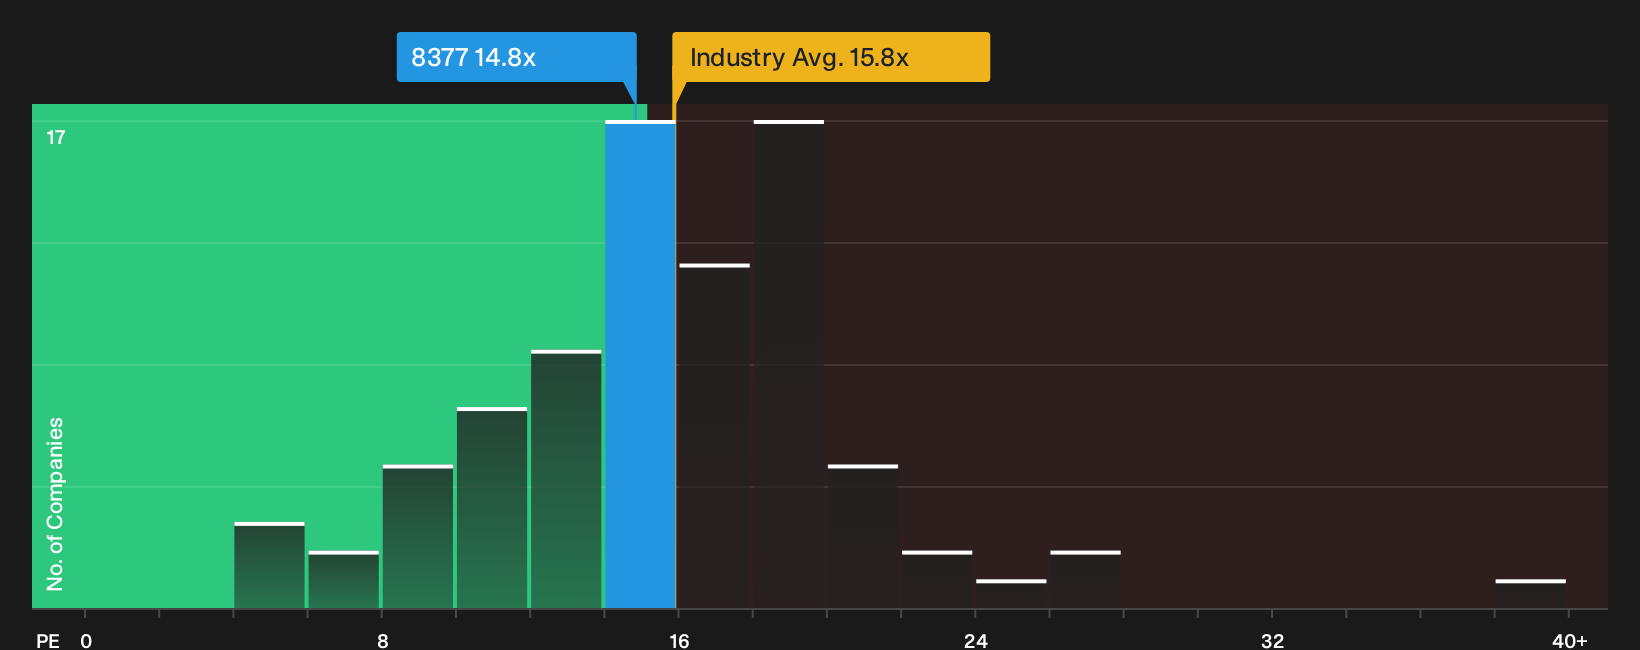
Hokuhoku Financial Group sits squarely in the Japanese domestic-focused banks theme, with regional branches, SME lending and retail deposits tying its fortunes closely to local interest rates and credit conditions. Recent earnings growth has exceeded both the broader Japanese market and the banks industry. At the same time, valuation signals and a P/E of 14.8x indicate that investors may be considering how a potential shift in funding costs and lending spreads could affect current margins.
Those shifting spreads and funding costs are already baked into some expectations, so use the 4 key rewards and 2 important warning signs to see how Hokuhoku Financial Group’s upside and pressure points line up.
Hachijuni Nagano Bank (TSE:8359)
Overview: Hachijuni Nagano Bank is a regional Japanese lender that provides domestic loans, deposits and everyday banking services to households and businesses.
Operations: Hachijuni Nagano Bank generates about ¥279.9b from banking and ¥41.2b from leasing, with reported revenue of ¥266.3b coming from Japan.
Market Cap: ¥1.24t
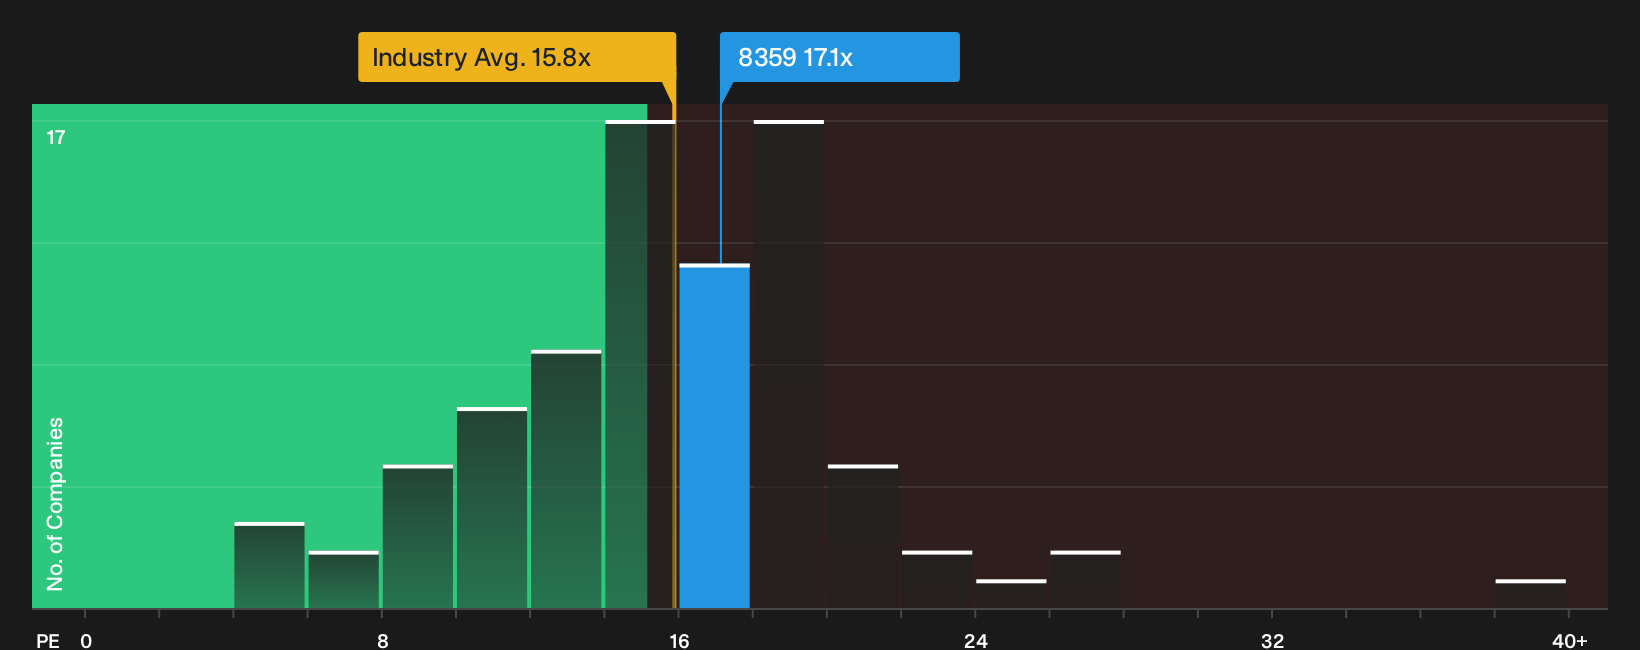
Hachijuni Nagano Bank is closely aligned with the Japanese Domestic-Focused Banks and Financials theme, with a regional franchise built around local lending, deposits and cross-sold financial services inside Japan. Analysts expect earnings and revenue to grow faster than the broader banks sector, while the stock currently trades at a higher P/E and at a premium to some fair value estimates. This combination can influence how much of any domestic interest rate tailwind may ultimately flow through to shareholder outcomes.
How much of that rate tailwind is already priced into Hachijuni Nagano Bank? Start with the 2 key rewards and 2 important warning signs to see where expectations may be stretching or lagging.
Seeking Alternatives Before The Crowd?
Fresh themes are already building breakout momentum while many investors stay focused on yesterday’s moves. Scan these ideas that are still under the radar and consider them before they attract wider attention.
- Look for early-stage potential that bigger funds may be missing by reviewing the 74 high quality undiscovered gems before attention and pricing catch up.
- Identify resilient compounders that may help stabilise a choppy portfolio by filtering for the 21 resilient stocks with low risk scores while it still reflects current conditions.
- Review companies with stronger cash generation and balance sheets by running through the list of solid balance sheet and fundamentals (20 results) before the broader market reacts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com