
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Dollar General (DG) Affordable Hallmark Holiday Line
- Dollar General introduced the Simply for You by Hallmark Holiday 2026 Collection, an exclusive in-store line of more than 30 décor, entertaining and gift items priced from $1 to $15, with over 70% at $5 or less, now available across about 19,500 locations in 48 states.
- The Hallmark partnership aligns directly with Dollar General’s value focus, using low-price seasonal décor and gifts to encourage holiday traffic from budget-conscious shoppers who are facing ongoing pressure from inflation and fuel costs.
- We will now look at how Dollar General’s low-priced Hallmark holiday range could influence the broader investment narrative around value retail.
Scan value retailers taking a similar approach to Dollar General’s holiday push by focusing on curated lists like 29 high quality undervalued stocks for ideas under pressure but still priced for potential recovery.
Dollar General Investment Narrative Recap
Dollar General shareholders need to believe that a value driven model in rural and small town markets can keep pulling in traffic even as shoppers stay under pressure. The Hallmark holiday collection fits that story but is a seasonal add on rather than a core profit driver. The nearer term swing factor remains whether consumables and everyday basics keep customers coming in often enough to support same store sales.
The biggest current risk is margin strain from inflation, labor and intense price competition while the chain is still investing in digital and store growth. The Hallmark range does not materially change that risk profile. It mainly tests Dollar General’s ability to use curated, low ticket non consumables to lift basket size without bloating inventory or hurting cash generation.
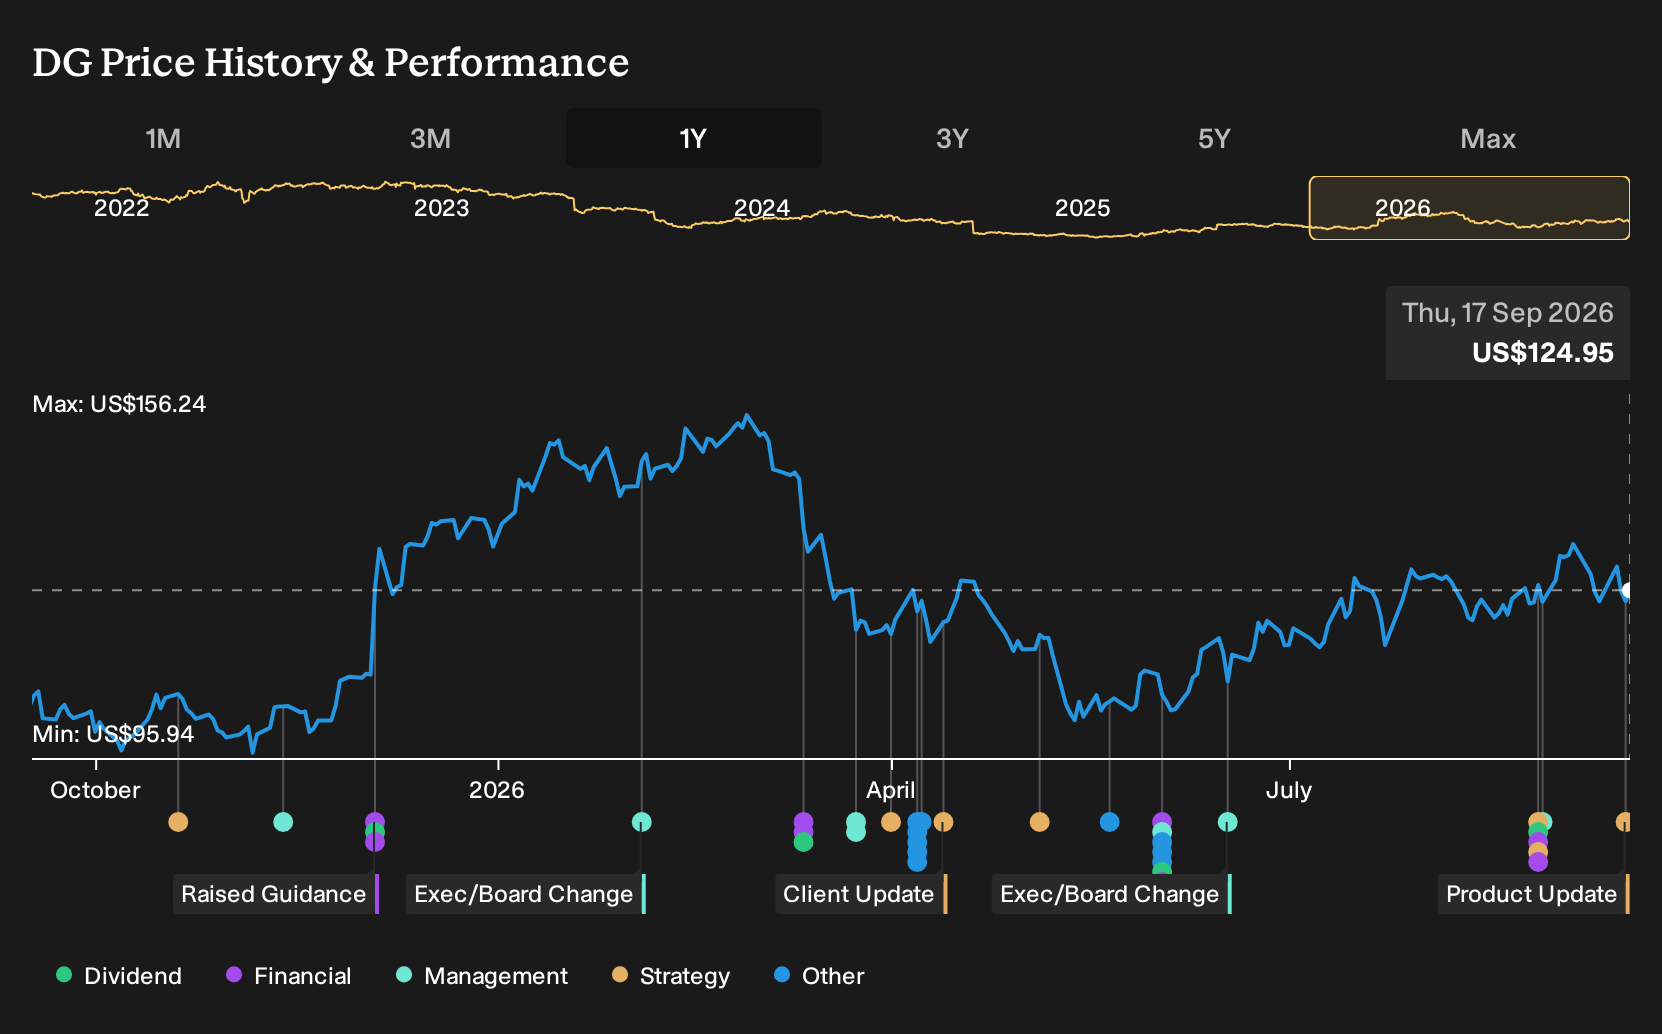
The most relevant recent update alongside this Hallmark launch is management’s plan to resume up to US$700m in share buybacks supported by stronger cash generation. That indicates the board views current cash flow as sufficient to fund both store investments and shareholder returns. For you, the key question is whether that confidence lines up with your own expectations.
If the Hallmark holiday push brings in incremental visits at healthy margins, it can support those cash flow ambitions and reduce the risk that buybacks compete with core investments. If it underperforms, investors will likely refocus quickly on execution in consumables, digital delivery and remodels, along with ongoing pressures from rural exposure and labor costs.
What The Analyst Narrative Implies For Dollar General
Dollar General's narrative projects US$48.8b revenue and US$1.9b earnings by 2029. This assumes 4.3% yearly revenue growth and an earnings increase of about US$300m from US$1.6b today.
Uncover why Dollar General's fair value indicates a 5% potential upside to its current price. This gap could narrow quickly once sentiment shifts.
Exploring Other Perspectives
One alternate view on Dollar General leans into tariff risk. The most cautious analysts worry that future price hikes to offset trade costs could squeeze already stretched shoppers. Their models sat closer to US$48.6b in 2029 revenue and about US$1.8b in earnings, so this Hallmark rollout might eventually shift those assumptions in either direction.
Explore 6 other Dollar General fair value estimates, including one that suggests there could be as much as 17% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Dollar General research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Dollar General. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dollar General's overall financial health at a glance.
Looking For More Ideas Beyond Dollar General?
Once you have a view on Dollar General, it can help to compare that thesis with a few other stocks that share similar themes around value, resilience and balance sheet strength. The Simply Wall St Screener is built for exactly that kind of side by side homework.
- If you want potential upside with a margin of safety, scan a 29 high quality undervalued stocks that match your preference for quality at a reasonable price.
- If dependable payouts matter to your plan, focus on a 6 dividend fortresses that combine higher yields with a focus on durability.
- If capital preservation sits near the top of your checklist, filter for a 30 resilient stocks with low risk scores that may offer steadier profiles through different cycles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com