
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Align Technology Stock: Is ALGN Underperforming the Healthcare Sector?
With a market capitalization of approximately $10.7 billion, Align Technology, Inc. (ALGN) has established itself as one of the leading names in digital orthodontics. The Tempe, Arizona-based company develops and markets the Invisalign clear aligner system, Vivera retainers, and iTero intraoral scanning systems, providing advanced digital treatment solutions for both patients and dental professionals worldwide. Operating through its Clear Aligner and Imaging Systems segments, Align has helped reshape the orthodontic industry by replacing traditional braces with technology-driven alternatives.
Companies valued between $10 billion and $200 billion are generally classified as “large-cap stocks,” and Align Technology fits this description, with its market capitalization reflecting its substantial size and established position within the healthcare sector. Align Technology has helped transform clear aligners into a global orthodontic business, led by its Invisalign system. With more than 90% market share and over 23 million patients treated worldwide, the company combines strong brand recognition with digital technology, including iTero scanners, while maintaining a high Profitability Rank of 9/10.
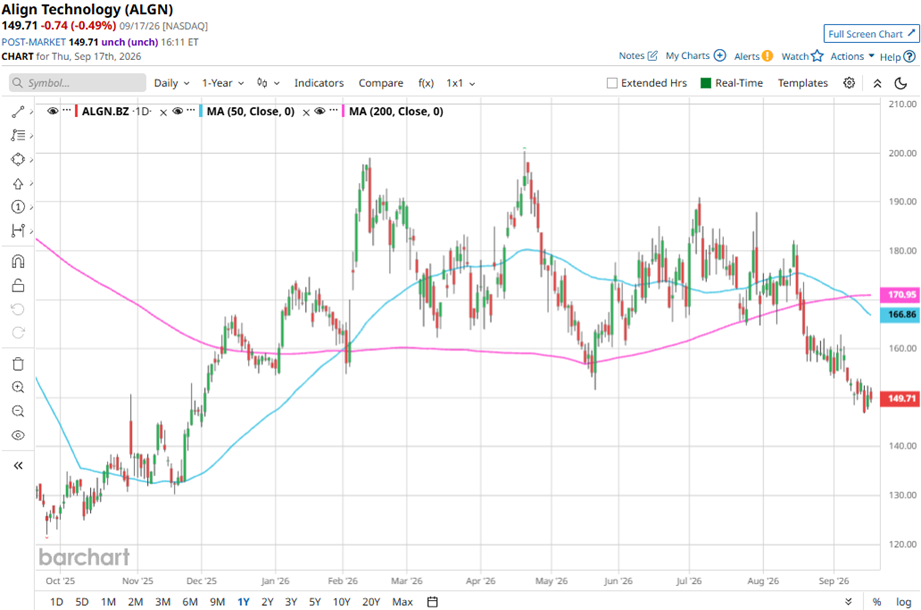
Despite these strengths, ALGN has slipped 25.3% from its 52-week high of $200.43, reached on April 21. Over the past three months, ALGN stock has dipped 13.7%, considerably underperforming the State Street Health Care Select Sector SPDR ETF (XLV), which has climbed 12% during the same time frame.
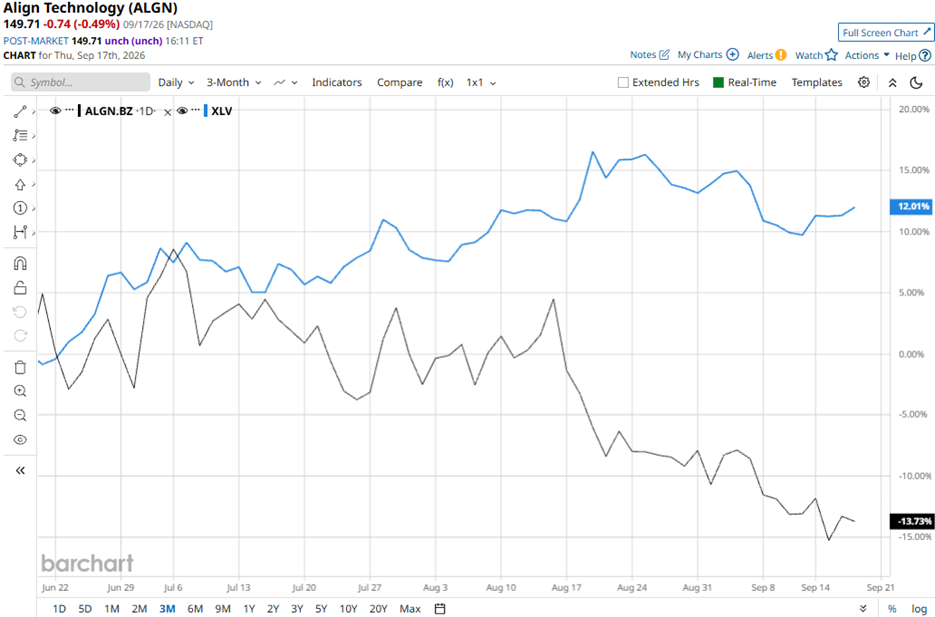
Shares of Align have declined 4.1% on a year-to-date (YTD) basis but gained 15.7% over the past year, trailing the ETF’s 9.1% YTD surge and 23% increase over the past 52 weeks.
The stock’s recent weakness is also showing up on the chart. Since mid-August, ALGN has remained below both its 50-day and 200-day moving averages, suggesting that the pullback has been more than a brief bout of volatility.
The bigger question for Align Technology is what is holding the stock back. The business itself is not broken, but the dental market has been moving through a slow recovery. In 2025, patients continued to put off elective procedures such as clear aligners as inflation, economic uncertainty, and cautious spending weighed on demand. Dental visits and aligner sales have started to improve, but the recovery remains gradual.
Plus, ALGN stock slipped after its latest quarterly results offered a mixed picture. Align reported Q2 2026 adjusted EPS of $2.64 and revenue of $1.06 billion, both above Wall Street’s estimates. Still, shares fell 3.7% the following session after management guided for below-consensus Q3 revenue of $1 billion to $1.02 billion, suggesting that near-term growth may remain under pressure.
In the competitive healthcare sector, Intuitive Surgical, Inc. (ISRG) has underperformed ALGN, declining 32.6% year-to-date and 12.5% over the past 52 weeks.
Wall Street analysts remain moderately bullish on ALGN’s prospects. The stock has a consensus “Moderate Buy” rating from the 16 analysts covering it. The mean price target of $206.60 suggests 38% upside from current price levels.
On the date of publication, Sristi Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.