
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sherwin-Williams (SHW), Why Is The Story Getting More Complicated?
Sherwin-Williams (SHW) has been drawing fresh attention after recent share performance data showed the stock down about 7% over the past month, even though its return over the past 3 months is roughly flat.
At a share price of $320.94, Sherwin-Williams has seen momentum cool, with a 30-day share price return that declined 7.05% and a year-to-date share price return that is down 2.10%, even though the 3-year total shareholder return of 29.57% points to a much stronger longer-term record.
Scan for other paint, materials, and coatings stocks showing similar momentum shifts by reviewing the curated 29 high quality undervalued stocks along with Sherwin-Williams.
That recent 7% slide puts Sherwin-Williams back on a lot of watchlists. Does that pullback offer a reasonable entry now, or does the valuation still argue for patience and a lower price first?
Most Popular Narrative: 18% Undervalued
On the most followed narrative, Sherwin-Williams screens as undervalued, with a fair value of $390.10 against the last close at $320.94. This puts the current pullback in a different light for anyone focused on long term potential rather than just recent price action.
The company's sustained focus on cost control, broad and deep restructuring (doubling annual savings targets to approximately $80 million), and disciplined SG&A management is structurally improving fixed cost leverage and expected to yield improved net margins and earnings power as sales volumes recover.
Ongoing construction of a new R&D center and increased R&D investment is expected to accelerate the rollout of premium, environmentally friendly, and specialty coatings that command higher price points, supporting future gross margin expansion and increasing competitive differentiation as sustainability and performance requirements intensify.
See why 37 investors see Sherwin-Williams as 18% undervalued.
Result: Fair Value of $390.10 (UNDERVALUED)
Still, if housing demand stays weak or supply chain inefficiencies linger, the Sherwin-Williams narrative could shift from margin recovery to renewed pressure.
Find out about the key risks to this Sherwin-Williams narrative.
Another View: Sherwin-Williams Through The P/E Lens
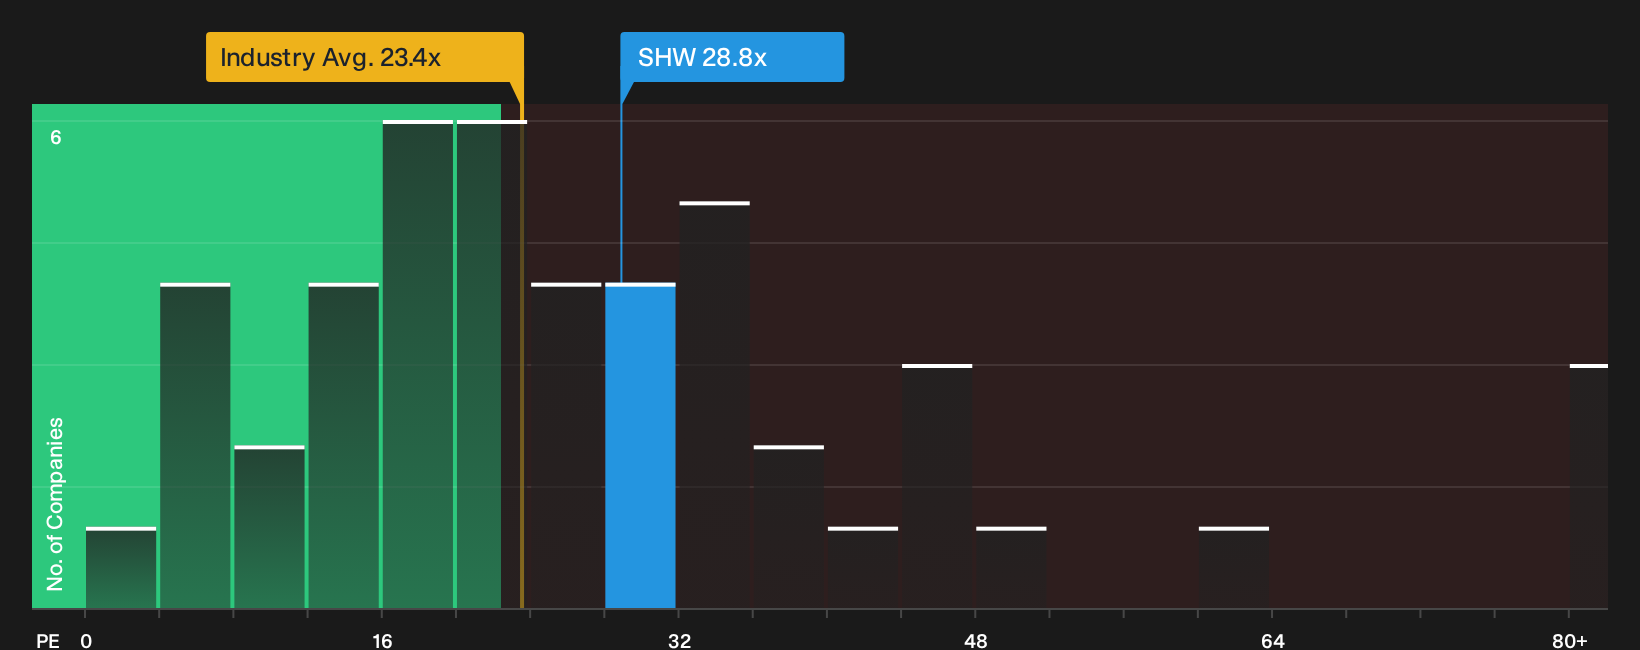
There is a catch. While the SWS DCF model flags Sherwin-Williams as undervalued, the current P/E of 28.8x sits well above both the US Chemicals industry at 23.4x and an estimated fair ratio of 22.6x. That premium suggests less room for error if growth disappoints. Does that richer multiple fit your risk appetite?
For a closer look at how this pricing stacks up against earnings power and peer valuations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mixed mood around Sherwin-Williams right now? Act quickly, break down the potential upside and downside for yourself, then weigh the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Sherwin-Williams?
If Sherwin-Williams has you rethinking your watchlist, you can broaden your view with a few focused idea lists that may highlight different types of opportunities.
- Target steadier compounding potential by scanning a curated set of companies with robust fundamentals and conservative profiles through the 30 resilient stocks with low risk scores.
- Search for quality at a discount by reviewing the carefully filtered 29 high quality undervalued stocks before prices change from levels that might appeal to you.
- Identify potential future market favorites early by checking the 16 high quality undiscovered gems that combine solid financials with relatively low current visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com