
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Patent Win Require Action From First Quantum Minerals Stock Investors?
- First Quantum Minerals recently secured UK patent and trademark protection for its Quantum Electra-Haul trolley-assist system and advanced stockpile processing at the halted Cobre Panamá mine, under a limited government authorization.
- The combination of patented trolley-assist technology that can materially cut diesel use and a controlled restart of Cobre Panamá processing reshapes how First Quantum Minerals balances decarbonisation goals with keeping a major asset in working condition.
- We will now see how First Quantum Minerals' trolley-assist push could reshape its investment narrative around scale, costs and ESG positioning.
Scan how First Quantum Minerals' trolley-assist push compares with other miners pursuing lower emissions and cost efficiency by reviewing the hand-picked 8 resilient stocks with low risk scores.
First Quantum Minerals Investment Narrative Recap
Owning First Quantum Minerals is essentially a view on large scale copper and nickel operations improving from a challenged starting point. The halted Cobre Panamá mine and current unprofitability mean the business is still working through real issues, even as revenue sits at $5,747m and analysts expect strong revenue and earnings growth over the next few years.
The key near term catalyst remains any durable solution around Cobre Panamá that moves the asset from preservation back toward normal operations. The biggest risk is financial pressure if earnings do not recover quickly enough to comfortably cover interest, given current losses of $83m and reliance on higher risk borrowing.
The limited authorization to process 38 million tonnes of Cobre Panamá stockpiles is the announcement that matters most here. It keeps First Quantum Minerals’ processing facilities warm, supports asset integrity and provides some copper concentrate output while the broader dispute with Panama remains unresolved.
This controlled restart sits alongside the trolley assist rollout and conference appearances as a live test of execution. You can watch whether management converts the interim processing window, trolley technology already used in Zambia and balance sheet tools like the $1b gold stream into a clearer path toward profitability and more comfortable interest coverage.
First Quantum Minerals' current analyst story points to $11.3b in revenue and $2.2b in earnings by 2029, built on an assumed 25.2% yearly revenue growth rate and an earnings swing of about $2.3b from today’s loss of $83m to that 2029 consensus profit figure.
Uncover why First Quantum Minerals' fair value indicates a 10% potential upside to its current price, which could narrow quickly.
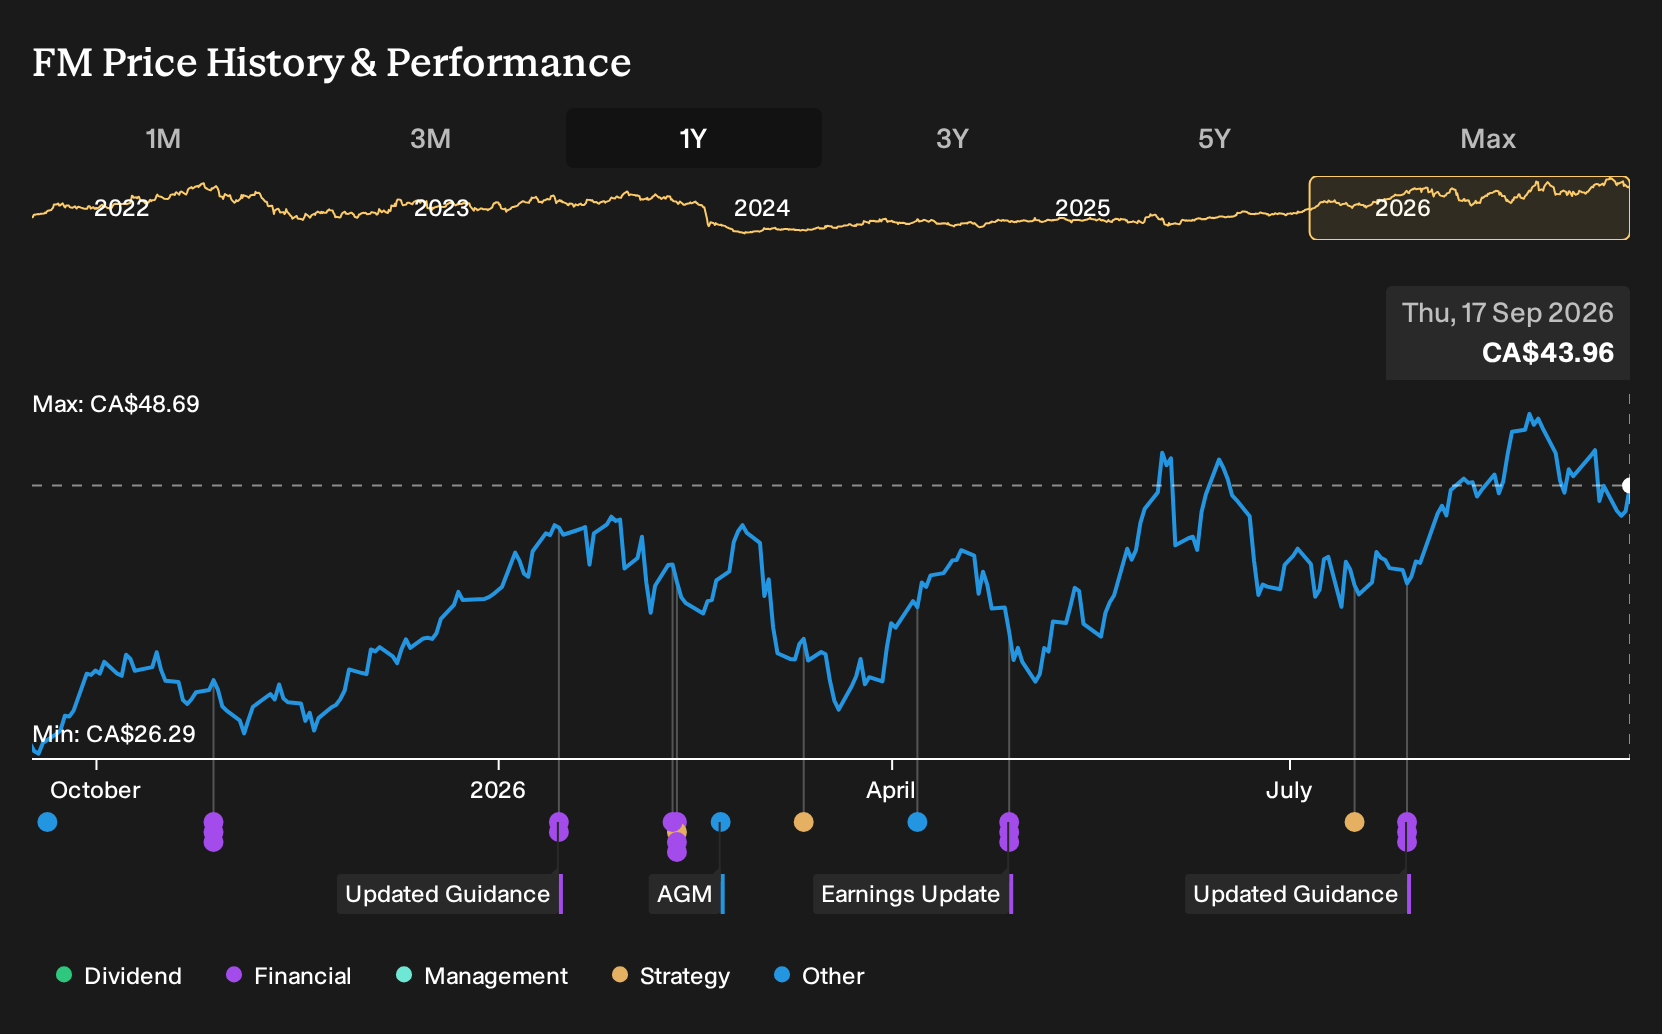
Exploring Other Perspectives
Conference bears on First Quantum Minerals focus on Cobre Panamá staying constrained for longer. Before this trolley assist push and stockpile restart, the most pessimistic analysts only pencilled in revenue of about $8.0b and earnings of $1.5b by 2029. That is well below consensus. This shows how widely opinions can differ and why you may want to explore several viewpoints that could now shift after these September 2026 updates.
Explore 3 other First Quantum Minerals fair value estimates, including one that suggests it could be worth just CA$48.53.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First Quantum Minerals research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Quantum Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Quantum Minerals' overall financial health at a glance.
Looking For More Ideas Beyond First Quantum Minerals?
If you want to pressure test the First Quantum Minerals thesis against other opportunities, using a curated screener can help you quickly spot different types of risk and reward profiles without getting lost in endless tickers.
- For investors who care most about resilient balance sheets and fundamentals, start with a list of solid balance sheet and fundamentals (7 results) that can handle tougher conditions without stretching cash resources.
- If value is your main filter, compare First Quantum Minerals with a 3 high quality undervalued stocks that currently screens as both financially strong and attractively priced on key metrics.
- Income focused readers can complement the First Quantum Minerals story by reviewing a 1 dividend fortresses that combines higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com