
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Diesel Shortage Stocks To Watch Including Flowserve Stock
Diesel has quietly become the new pressure point for the global economy, as war damage to refineries, export bans and thin spare capacity push fuel prices higher and ripple through shipping, farming and heavy industry. That pain on the ground can mean fresh order books for select refinery equipment suppliers and service contractors. This article looks at 3 stocks exposed to this news and how each might either benefit or face growing risks.
The stocks below are just a starting sample, and the full screen on this theme surfaced 65 more companies with equally compelling narratives that are not covered here.
Head straight into the Global Energy Infrastructure and Refining Services Suppliers screener to identify, filter and analyze the highest conviction refinery equipment and services plays tied to this diesel squeeze story.
Flowserve (FLS)
Overview: Flowserve supplies pumps, valves, seals and flow management services that keep refineries and petrochemical plants running across global energy hubs.
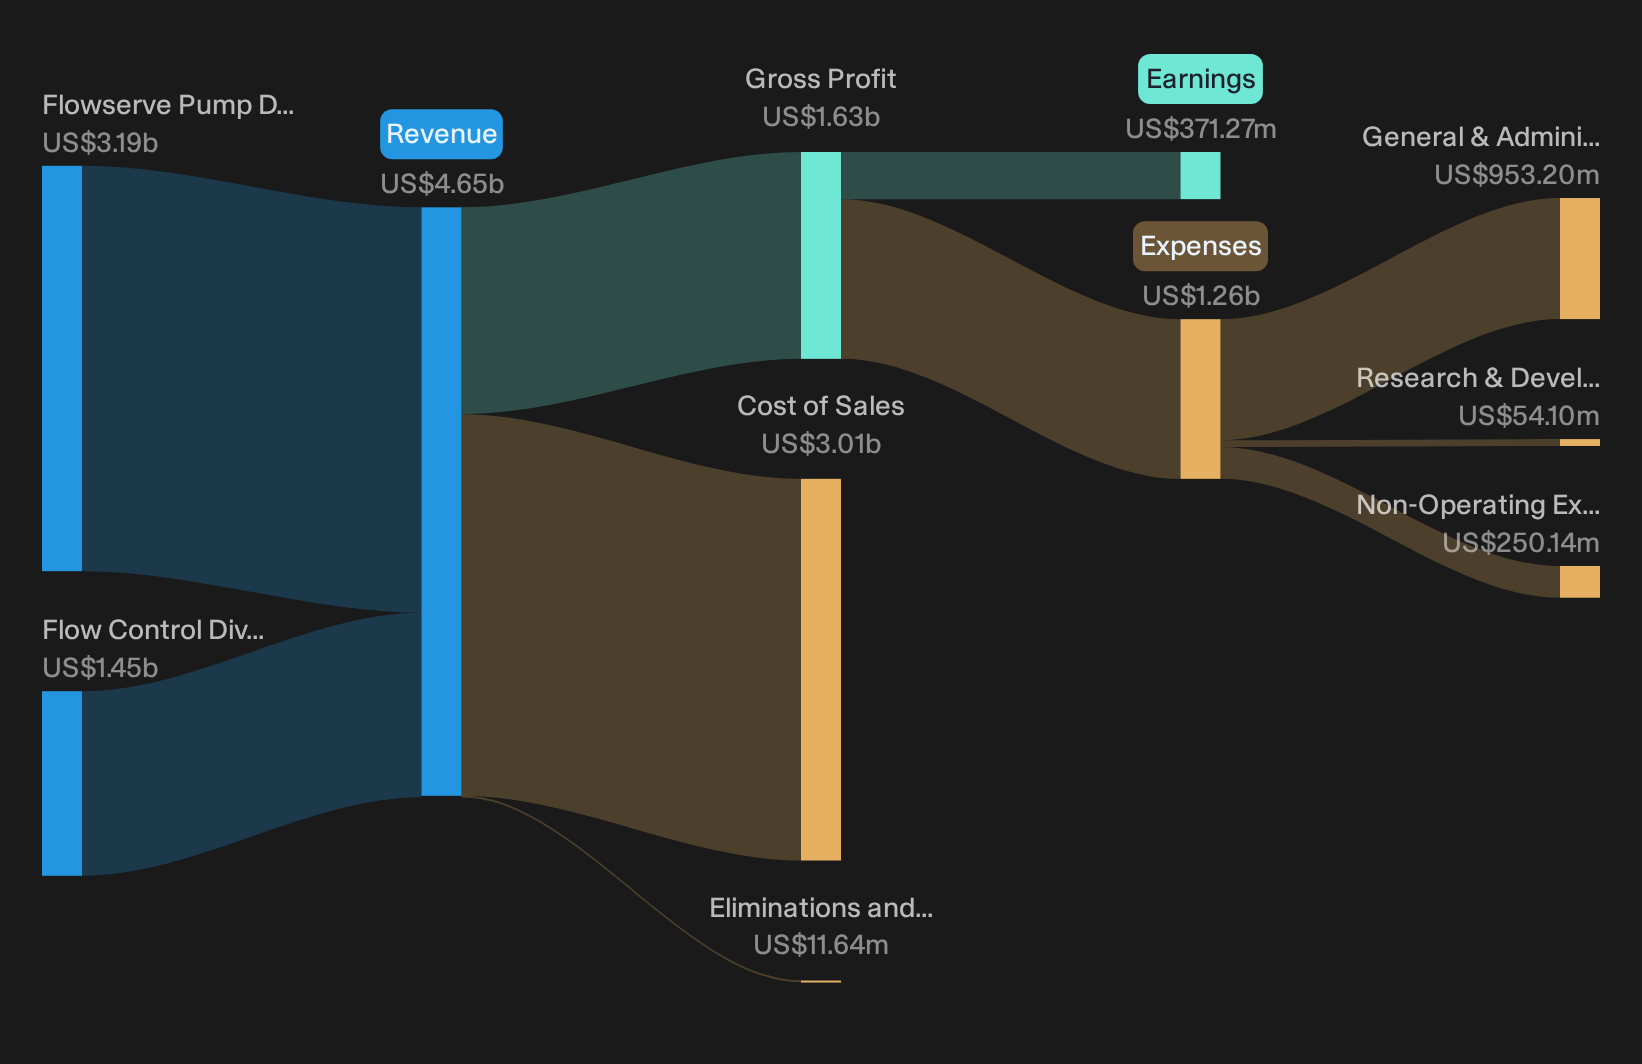
Operations: Flowserve generates about US$3.2b from its Pump Division and US$1.5b from its Flow Control Division, after small internal eliminations.
Market Cap: US$9.2b
Flowserve matters for this diesel squeeze theme because its equipment and service work often sits where refinery bottlenecks, outages and upgrades get resolved.
"The ongoing macroeconomic uncertainty, combined with the new dynamic introduced by the changing tariff environment, could limit Flowserve's ability to expand revenue despite a healthy start to the year, as tariffs may impact global market demand which might first affect project spending."
What happens to margins and project timing if a single unseen pressure on that refinery capex and maintenance cycle breaks differently?
If that pressure point is what you care about, read the full narrative for Flowserve to see how Flowserve might turn refinery stress into accelerating opportunity.
Johnson Matthey (LSE:JMAT)
Overview: Johnson Matthey develops emission control catalysts, refinery and PGM services, and hydrogen technologies that link diesel demand, desulfurization and cleaner fuels.
Operations: Johnson Matthey generates about £3.8b from Clean Air, £10.3b from PGM Services and £80m from Hydrogen Technologies, after £1.6b eliminations.
Market Cap: £2.8b
Johnson Matthey matters for this diesel crunch theme because its refinery and emissions catalysts sit where tighter fuel specs meet limited capacity.
"Ongoing transformation efforts aimed at increasing efficiency and reducing costs are expected to continue to positively impact net margins and overall earnings."
What happens to that margin story if a single assumption about diesel desulfurization demand or refinery upgrade intensity breaks differently from expectations?
If that question is on your mind, read the full narrative for Johnson Matthey to see how Johnson Matthey could turn refinery upgrades into accelerating earnings power.

DNOW (DNOW)
Overview: DNOW distributes pipe, valves, fittings, pumps and related services that keep refineries and wider energy infrastructure supplied for construction, maintenance and repairs.
Operations: DNOW generates US$4.1b from Wholesale Miscellaneous activity, with revenue largely from the United States, supported by Canada and international markets.
Market Cap: US$2.8b
DNOW matters for this refinery infrastructure theme because it sits in the middle of the parts flow, sourcing the valves, pipe and pumps that keep diesel-focused facilities running when outages, upgrades or emergency repairs suddenly need hardware on site.
"Expansion into the midstream market through the acquisition of Whitco, expected to bolster supply chain capabilities, particularly in the aging and undersized midstream infrastructure, potentially increasing revenues by accessing a larger market and offering day-to-day MRO and capital project opportunities."
What happens to DNOW’s margins and growth profile if a single assumption about integration timing or synergy delivery plays out differently than expected?
If that integration swing factor matters to you, read the full narrative for DNOW for how DNOW could turn refinery stress into accelerating, higher quality earnings power.

Curious About What You Might Be Missing?
Fresh stories move first. When capital rotates, some themes start to break out while others lose momentum and get caught dropping under the radar for now, so consider acting promptly.
- Spot potential turnarounds early by scanning the 16 high quality undiscovered gems that screens for under-followed businesses with fundamentals that still look fresh while attention is elsewhere.
- Ride structural shifts by tracking the 37 power grid technology and infrastructure stocks that highlights companies tied to grid upgrades before that narrative is fully reflected in prices.
- Stay aware of developments in the mining space with the 36 elite gold producer stocks that filters for producers where operations, balance sheets and reserves still align with stated strategies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com