
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Cellebrite DI (CLBT) Faces A Probe And CEO Change, Is It Still Cheap?
Cellebrite DI (CLBT) is back in focus after a securities law probe, missed Annual Recurring Revenue projections, reduced full-year guidance, and a sudden CEO change, all tied to permit delays on cloud deals.
Cellebrite DI’s share price has bounced 3.41% over the past day and 7.45% over the past month to US$11.82. However, the year-to-date share price return is down 33.74%, while the three-year total shareholder return of 56.97% points to much stronger longer-term momentum.
Scan beyond Cellebrite DI and stress test your thesis against a curated 29 high quality undervalued stocks that pairs solid cash flows with stronger balance sheets.
The recent rebound in Cellebrite DI after a sharp year-to-date decline puts a simple tension on the table. Are investors reassessing the business, or just reacting to sentiment swings around guidance cuts and the CEO change?
Most Popular Narrative: 23% Undervalued
Cellebrite DI last closed at $11.82, while the most followed narrative pegs fair value at roughly $15.36, which implies a meaningful discount that hinges heavily on how recurring SaaS revenue plays out over time.
The continued transition to a recurring, subscription-based revenue model, with over 90% of revenues now from subscriptions and growing SaaS/cloud penetration, improves revenue visibility, predictability, and operating leverage. This is already translating into higher EBITDA and free cash flow margins and is likely underappreciated in current valuations.
See why 20 investors see Cellebrite DI as 23% undervalued.
The narrative uses a 10.48% discount rate and ties its fair value to assumptions about subscription growth, margin expansion, and a 43.6x future P/E multiple, all of which sit above the current sector average quoted in that same narrative. Analysts contributing to this view also cluster around a $15.36 consensus target, while still disagreeing on the exact upside, which puts extra weight on how readers judge the cloud shift, federal exposure, and management execution after the latest guidance reset.
Result: Fair Value of $15.36 (UNDERVALUED)
Still, the heavy dependence on US federal contracts and ongoing regulatory scrutiny around digital evidence could quickly challenge the Cellebrite DI upside case that investors are leaning on.
Find out about the key risks to this Cellebrite DI narrative.
Another View: Multiples Paint A Tougher Picture For Cellebrite DI
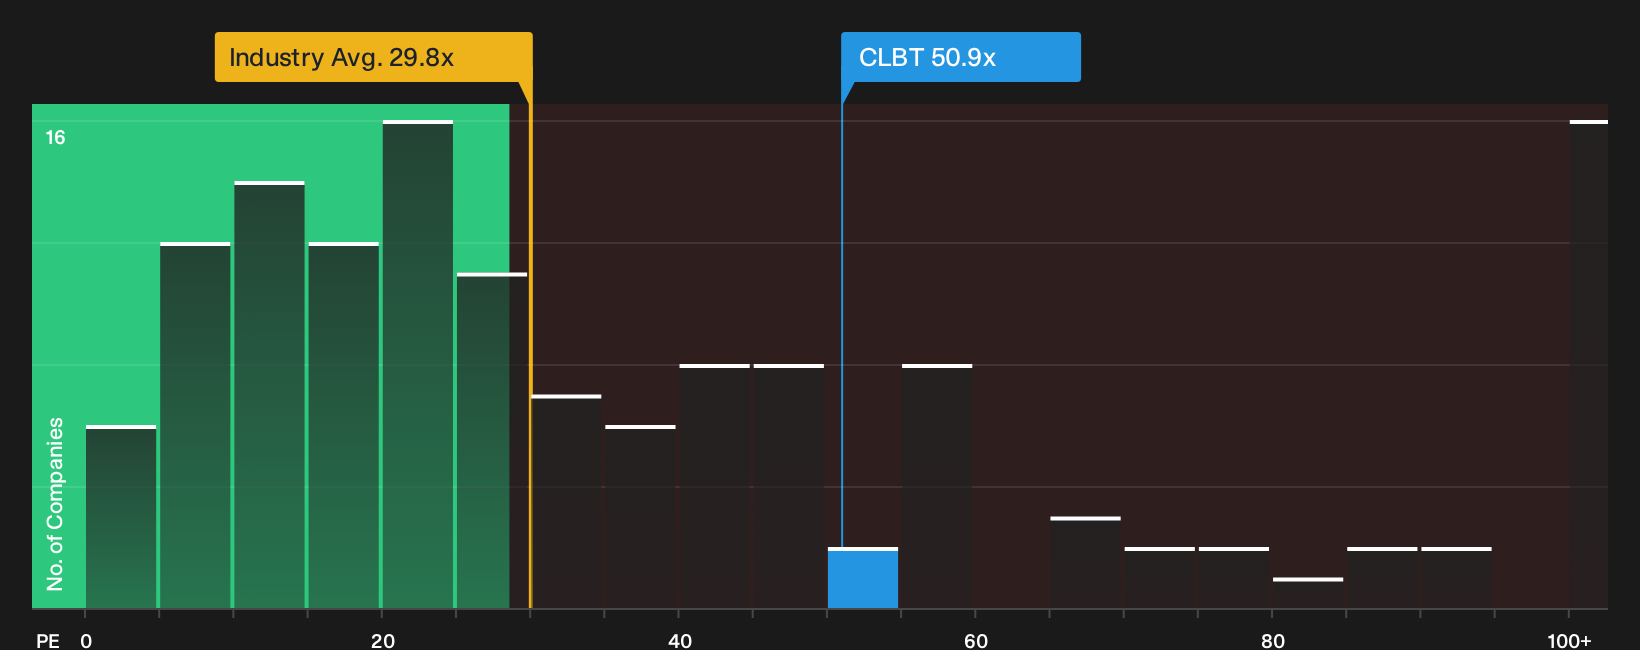
The story changes once the focus shifts to simple price ratios. Cellebrite DI trades on a P/E of 50.9x, which is higher than the peer average of 40.5x and well above a fair ratio estimate of 35.6x. That gap suggests valuation risk if sentiment cools, so which signal do you put more weight on?
To pressure test your own view against the numbers that underpin this richer multiple, take a closer look at the valuation breakdown and how it compares to other software stocks, then see what the numbers say in our breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Cellebrite DI is mixed, so consider using that friction as a prompt to move quickly, review the numbers yourself, and weigh up the balance of 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Cellebrite DI?
If Cellebrite DI has sharpened your thinking, do not stop there. Use the Simply Wall St screener to pressure test fresh ideas before capital goes to work.
- Target resilient compounding potential by focusing on businesses with strong balance sheets and solid fundamentals through our list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality and compare valuations against your Cellebrite DI thesis using a curated 29 high quality undervalued stocks.
- Prioritize stability and income by lining up companies offering robust cash payouts with the help of our 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com