
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Joby Aviation (JOBY) Is Getting Attention Today
Joby Aviation (JOBY) has kicked off a month-long, coast-to-coast tour of its autonomous J208 aircraft, using a converted Cessna Caravan to showcase real-world cargo, medical, and defense logistics use cases.
Despite the high-profile Electric Skies tour and fresh corporate events like the recent executive appointment and upcoming Morgan Stanley conference appearance, Joby Aviation’s share price has been under pressure, with the stock down 56.89% on a year-to-date share price return and the 1-year total shareholder return declining 57.69%. This suggests recent news is being weighed against ongoing questions about execution risk and the timeline to commercial scale.
Benchmark Joby Aviation’s autonomous push against other high-conviction ideas in future-focused transport by screening for 95 robotics and automation stocks that are already turning advanced automation into real-world use cases.
Joby Aviation is now trading far below where it started the year, even as the J208 tour puts its autonomy story in front of regulators and partners. Does that reset leave enough potential to justify the execution risk?
Most Popular Narrative: 42% Undervalued
Joby Aviation’s most followed narrative pegs fair value at $10.68 per share, well above the recent $6.19 close. This frames a wide gap between market pricing and that long term story built on air taxi, defense, and autonomy optionality.
The business model now spans manufacturing, a vertically integrated air taxi network, defense variants, autonomy software and Blade’s existing helicopter routes. This breadth of initiatives could stretch management focus, introduce integration risks and keep operating expenses elevated, which may weigh on future net margins and delay any path to sustained earnings.
See why 35 investors see Joby Aviation as 42% undervalued.
Result: Fair Value of $10.68 (UNDERVALUED)
Still, the narrative around Joby Aviation could shift quickly if liquidity of roughly US$1.55b and progress through FAA Type Inspection Authorization begin to ease execution fears.
Find out about the key risks to this Joby Aviation narrative.
Another View: Joby Aviation Looks Expensive On Book Value
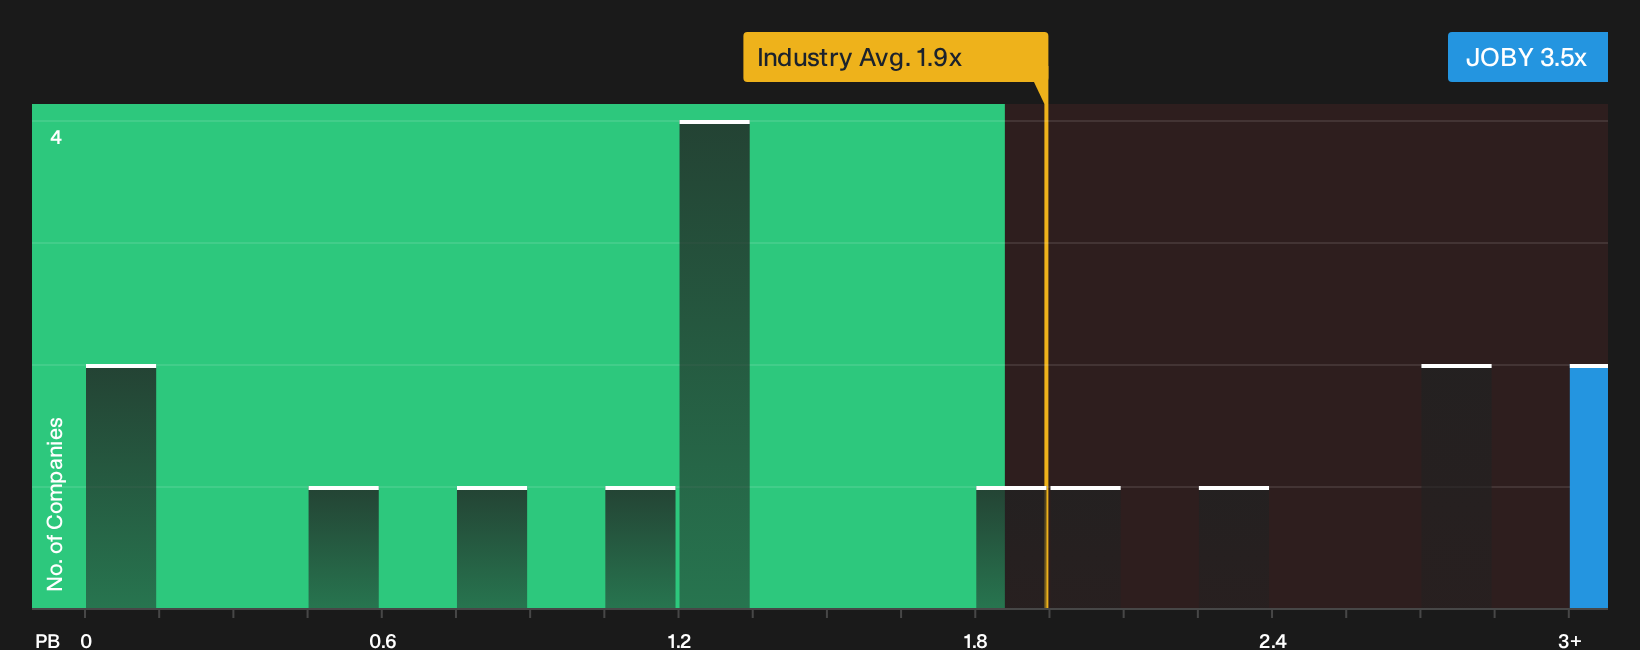
The fair value story around Joby Aviation leans on long term earnings assumptions, but its current P/B ratio of 3.5x is high next to both the Global Airlines industry at 1.9x and peers at 1.8x. That richer multiple raises a simple question. Is the market already paying up for a future that still has to be earned?
To see how this price compares with the ratio the market could move towards, and what that might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals are all over the Joby Aviation story, so if this coverage has raised more questions than answers, move fast and weigh the trade off between concern and upside using the 1 key reward and 2 important warning signs.
Looking For More Ideas Beyond Joby Aviation?
If Joby Aviation has you thinking harder about risk and reward, do not stop here. Let data driven shortlists guide your next round of research.
- Target higher income potential by scanning 6 dividend fortresses that focus on sizable yields paired with resilience in tougher conditions.
- Hunt for mispriced quality using the 16 high quality undiscovered gems that highlight strong fundamentals before wider attention arrives.
- Dial down volatility risk and focus on staying power through 30 resilient stocks with low risk scores that prioritise durable balance sheets and steadier returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com