
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Caledonia Mining (NYSEAM:CMCL) A Bargain Or Fully Priced On Earnings?
Caledonia Mining has delivered a powerful long term share-price gain, yet the stock is well down from its highs over the past year. This puts fresh focus on whether its current market value lines up with the earnings the business is generating today. With that mixed price history in mind, investors are asking if the recent quote around US$24 still reflects what the company earns, or if sentiment has moved ahead of the underlying profit stream.
- Over the past 3 years the share price has climbed 166.9%. This raises the question of how much of that move is supported by sustainable earnings power rather than changing investor appetite.
- The business relies heavily on converting its mining operations into cash profits, so the durability of production levels and cost control can shape how much investors are willing to pay for each dollar of earnings.
- The analysts covering Caledonia Mining have run their own numbers. See what analysts think Caledonia Mining's shares could be worth.
The stock's next move may depend on whether Caledonia Mining's current share price is adequately supported by its earnings profile.
If you are weighing whether Caledonia Mining's earnings justify its recent share-price swings, it can help to compare that question across 29 high quality undervalued stocks.
Is Caledonia Mining a Bargain on Earnings?
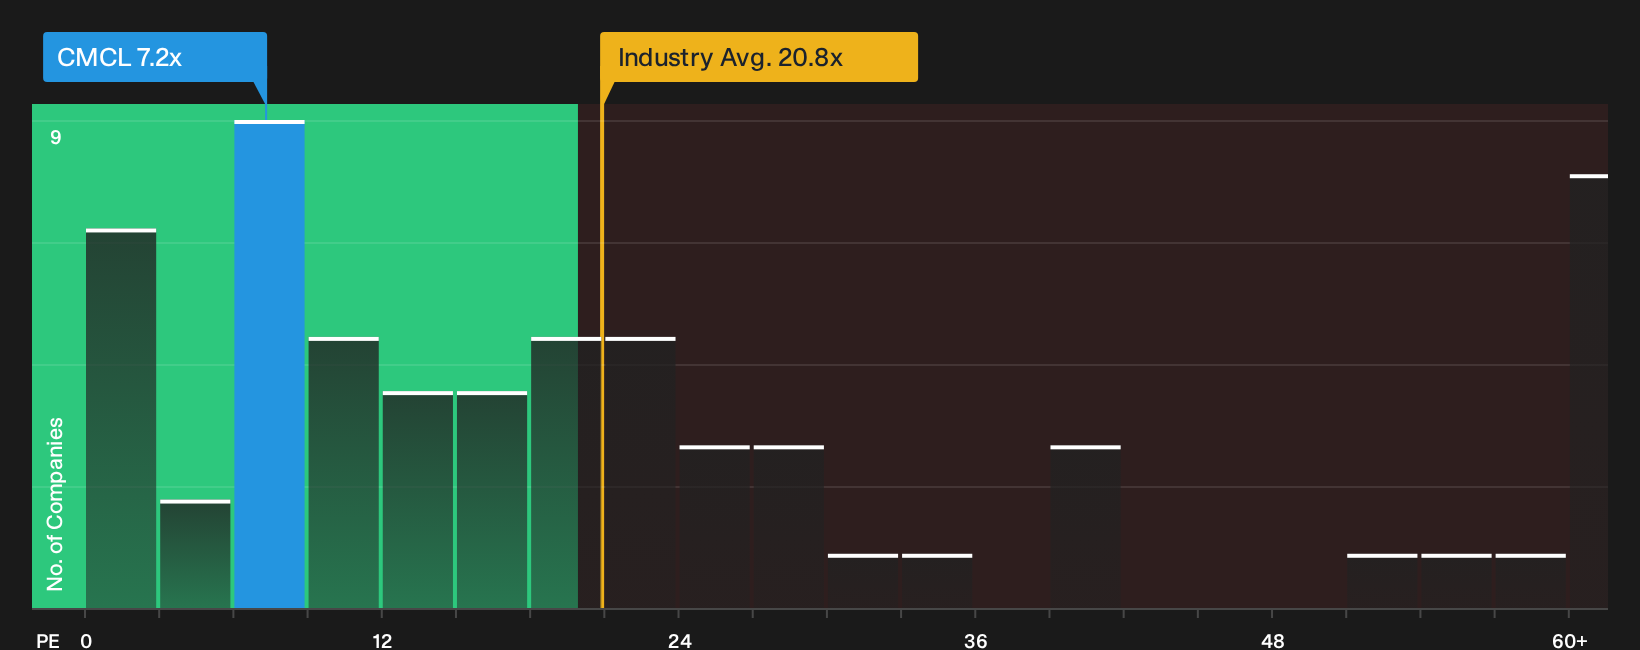
The P/E ratio suits Caledonia Mining because earnings sit at the center of how investors typically judge a mature producer. On this metric, the stock trades on a P/E of 7.2x, compared with roughly 20.8x for the wider Metals and Mining group and about 11.2x for its closest peers. That puts the current pricing at a clear discount to what investors are paying elsewhere in the sector for each dollar of profit.
The valuation model that blends Caledonia Mining's growth profile, margins, size and risk points to a higher multiple as a more tailored anchor. As a result, the present 7.2x reading screens as undervalued against that benchmark. For a reader, that gap means the market is currently asking a lower price for the company’s earnings stream than the model would suggest. The key judgement is whether the quality and durability of those profits justify a closer alignment. Explore the numbers behind Caledonia Mining's P/E valuation.
The Caledonia Mining Narrative: What Would Justify Today's Price?
Narratives for Caledonia Mining pick up where the valuation puzzle stops by spelling out what kind of future path for production, earnings and margins would need to hold for the shares to end up worth materially more or materially less than today’s price. They sit on Simply Wall St’s Community page, and each storyline links a specific mix of potential catalysts and risks to its own view of fair value, so you can watch over time which version of events appears to be unfolding.
One of the top community narratives on Caledonia Mining: 49% undervalued
"Expansion at Motapa and operational improvements could drive outsized resource growth, higher margins, and sustainable competitive advantages in cost and profitability..."
Discover why this Narrative puts Caledonia Mining at 49% undervalued.
One more angle on Caledonia Mining that could change the story
Numbers only tell part of the story for Caledonia Mining, because the people setting priorities and how they are rewarded can quietly shape risk, capital allocation and long term outcomes in ways the P/E alone never shows. See who runs Caledonia Mining and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com