
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Fourmile Dispute Resolution At Newmont Stock Has Changed Its Investment Story
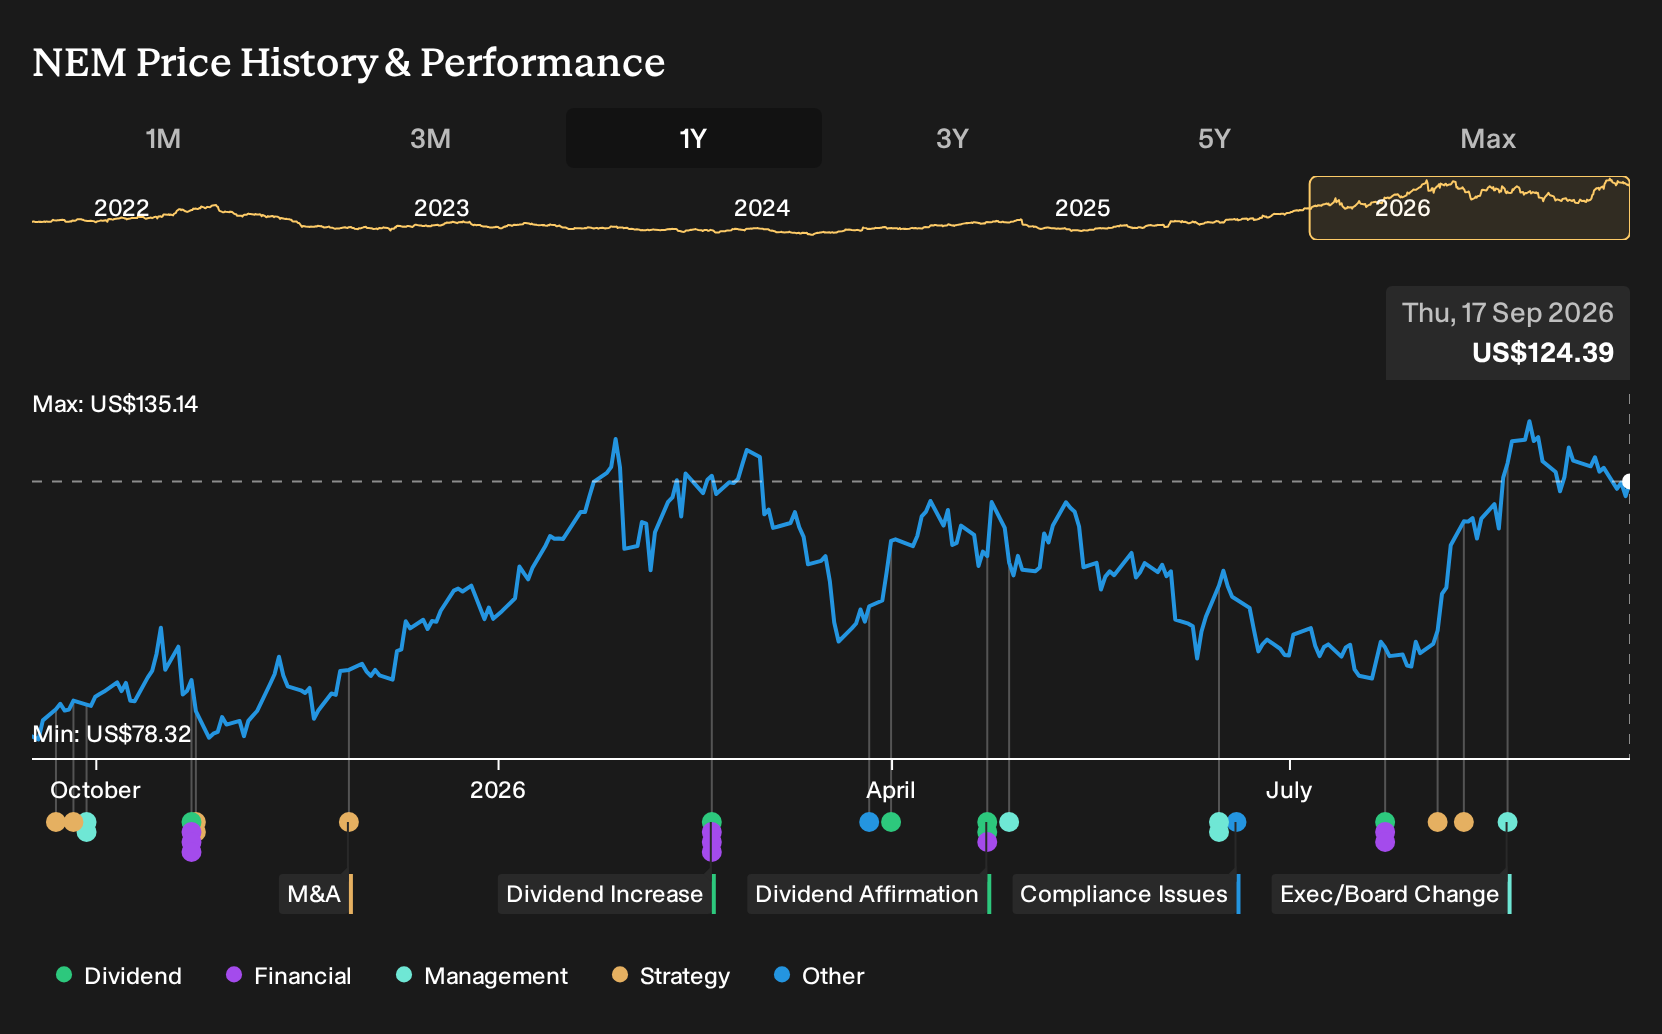
- Newmont recently resolved its Fourmile project dispute with Barrick Mining and benefited from a rebound in gold prices following the latest Federal Reserve interest rate decision. This eased project uncertainty and reinforced its balance sheet flexibility.
- The cleared overhang at Fourmile reduces execution risk for Newmont's growth pipeline and supports its capacity to maintain shareholder distributions from internal cash generation.
- We will assess how Newmont's investment narrative is affected by the Fourmile dispute resolution and the recent rebound in gold prices.
Compare Newmont's setup to hand-picked peers by scanning our 36 elite gold producer stocks, reacting to the same gold price swings and project catalysts.
Newmont Investment Narrative Recap
For you to be comfortable holding Newmont, you need to believe the miner can keep turning a large existing asset base into steady cash flow while gold prices stay supportive enough to offset higher operating and capital costs. The key short term swing factor remains operational delivery on core mines as grades trend lower at some sites and spending on sustaining projects stays elevated.
The latest bounce in gold after the Fed decision helps near term cash generation but does not meaningfully change the main risk, which is execution across a complex portfolio that includes integration of recently acquired assets and leadership changes. Cost creep, safety issues or project delays would matter more than a one day move in the metal.
The cleanest operational development around this news is the settlement of the Fourmile dispute with Barrick. That removes uncertainty over ownership and future development rights on an important Nevada growth option for Newmont. The company can now plan mine sequencing and capital allocation there without a legal overhang sitting in the background.
With that issue resolved, the focus turns back to how effectively management can convert the broader project pipeline and the Newcrest integration into stable volumes and margins while dealing with rising sustaining and development capex. Analyst optimism around production potential only matters if execution matches the plan, so your attention as a shareholder stays on safety performance, project timing and unit costs over the next few quarters.
What The Newmont Forecasts Assume
Newmont's narrative projects US$31.4b revenue and US$12.3b earnings by 2029. That framework rests on analysts baking in 6.8% yearly revenue growth and an earnings increase of about US$3.7b from US$8.6b today.
Uncover why Newmont's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One area where the most optimistic analysts part ways with consensus is the revenue potential for Newmont if automation and digitalization become more impactful. Before this Fourmile settlement and the latest gold move, the bullish camp was outlining US$39.9b of revenue and US$19.5b of earnings by 2029. That is far above the baseline. Use this news as a prompt to consider whether those assumptions still feel realistic to you or require reconsideration.
Explore 8 other Newmont fair value estimates, including one that suggests as much as 35% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Newmont research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Newmont. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newmont's overall financial health at a glance.
Looking For More Investment Ideas Beyond Newmont?
If this Newmont update has sharpened your view on gold producers, it can be useful to widen the lens and see how other businesses stack up on quality, income and risk using the Simply Wall St Screener.
- For investors who want a margin of safety built on both fundamentals and valuation, scan a curated set of 29 high quality undervalued stocks that combine stronger balance sheets with appealing prices.
- If capital preservation and steadier profiles matter more to you than headline excitement, narrow your research to a 30 resilient stocks with low risk scores that aims to filter for more resilient businesses.
- When you want potential upside but still care about underlying strength, broaden your watchlist with a 16 high quality undiscovered gems that highlight lesser known companies with solid financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com