
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Global AI Contest Will Impact iQIYI Stock
- iQIYI recently launched the Global AI Creator Challenge on the international version of its NadouPro platform, pairing it with Alibaba's Wan3.0 model. The initiative includes detailed submission rules, a prize pool above US$10,000, and a judging schedule that runs through late September 2026.
- The contest and NadouPro upgrades highlight iQIYI's push to embed AI into professional content workflows, which could influence production costs, creator engagement, and the appeal of its broader long-form ecosystem.
- We will now assess how this push into AI-driven NadouPro filmmaking could influence iQIYI's investment narrative for long-form video.
Scan beyond iQIYI and this contest by lining up other AI-focused media players using our handpicked 35 AI small caps that are already pushing hard into machine-driven content workflows.
iQIYI Investment Narrative Recap
For iQIYI, the core belief is that long form video on the big screen can still attract large, loyal audiences and that the platform can convert that attention into steadier subscription and ad income. The near term swing factor remains whether content output and user engagement recover enough to ease pressure after earlier declines in membership and advertising revenue.
The biggest operational risk is still the cost and hit driven nature of premium shows, especially with margins recently close to breakeven. The NadouPro AI push, including this global contest, may help on efficiency over time, but the direct impact on the key short term catalyst and risk profile looks limited for now.
The recent focus on big screen viewing is highly relevant here. iQIYI is leaning into TV and connected device usage as a way to deepen watch time, push higher tier memberships, and give advertisers more premium inventory to work with. All of these efforts tie directly into user scale, engagement, and monetization.
If that big screen push gains traction, it could amplify whatever efficiency gains NadouPro and Alibaba's Wan3.0 model eventually deliver by spreading content economics over a broader, more engaged audience. If engagement on large screens stalls or content misfires, even strong AI tools may not offset the earnings and margin pressure already visible in the business.
iQIYI's current loss of CN¥683.0 million is set against analyst expectations for earnings of CN¥728.7 million on revenue of CN¥27.0 billion by 2029, a swing of about CN¥1.4 billion in profit, while overall revenue is projected to remain broadly flat over the next three years.
Uncover how iQIYI's fair value indicates a 40% potential upside to its current price, which could narrow quickly as sentiment around iQIYI shifts.
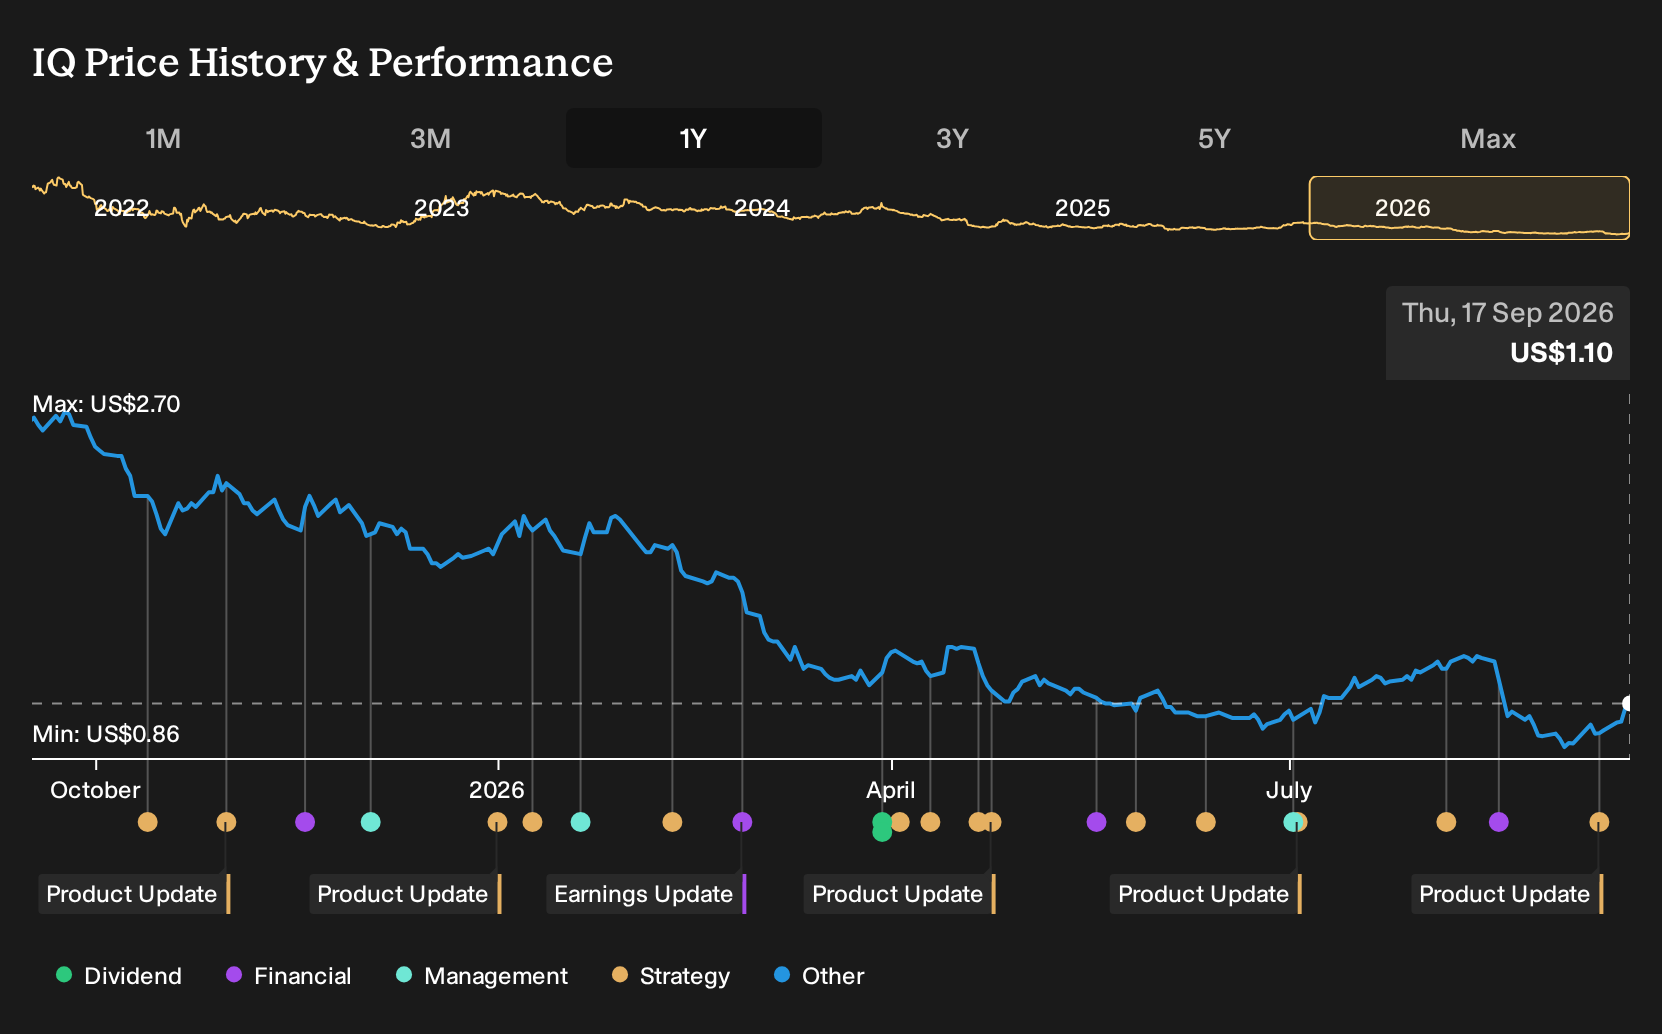
Exploring Other Perspectives
Some analysts care less about iQIYI's AI push and focus on a tougher risk. They worry that long form viewing keeps losing ground to ultra short content, which feeds into their lower forecasts. The most cautious group was looking for CN¥24.3b of revenue and only CN¥321.1m of earnings by 2029. Those views came before this contest.
Explore 3 other iQIYI fair value estimates, including one that suggests it could be worth just $1.40!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your iQIYI research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for iQIYI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate iQIYI's overall financial health at a glance.
Looking for more iQIYI style investment ideas?
If the iQIYI story has sharpened your thinking about content, cash flow, and risk, it can help to line it up against a wider watchlist built around clear themes.
- Prefer stocks where quality and valuation both matter? Filter for companies that score well on fundamentals yet trade at what may be appealing prices using our 29 high quality undervalued stocks.
- Want income to do more of the heavy lifting? Focus on resilient payers with higher yields by scanning the 6 dividend fortresses that meet your comfort level for stability.
- Care most about balance sheet strength and durability? Build a list of companies with lower leverage and solid financial footing through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com