
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vistra (VST) Shares Moved, What Is Driving Attention Now?
Vistra (VST) has drawn fresh attention after filing an omnibus shelf registration for common and preferred stock, a move that gives the utility more flexibility to respond to AI driven power demand and financing needs.
Vistra’s share price has pulled back from earlier highs, with a 90 day share price return that declined 12.33% and a year to date share price return down 13.12%, even though the 3 year total shareholder return is around 3.4x and the 5 year total shareholder return is close to 8x. Recent news around long term power agreements with major technology customers, the new shelf registration, and a US$1.5b junior subordinated notes offering suggests that investors are reassessing both the growth potential tied to AI driven demand and the risks around capital needs, regulation, and Vistra’s role in PJM.
Scan how other power producers are positioned for the AI data center buildout by reviewing the hand picked 37 power grid technology and infrastructure stocks along with Vistra’s latest moves.
Vistra’s pullback, new funding levers, and long term AI power deals create a clear fork in the road. Is the better move to step in now, or to wait for a cheaper entry before the next leg of execution plays out?
Most Popular Narrative: 51% Undervalued
Vistra last closed at $143.56, while the most followed narrative pegs fair value at about $291.87. The gap between price and perceived worth is wide and is based on detailed cash flow analysis rather than headline multiples.
Here''s what I actually found. Vistra''s Q2 2026 GAAP net income came in at $305 million, down about 7% year over year. In the same quarter, Ongoing Operations Adjusted EBITDA grew more than 31% to $1.767 billion, with full-year guidance reaffirmed.
See why 63 investors see Vistra as 51% undervalued.
Result: Fair Value of $291.87 (UNDERVALUED)
Still, Vistra’s heavy net debt load and recurring hedge driven GAAP swings could easily flip sentiment again if cash generation or contract economics disappoint.
Find out about the key risks to this Vistra narrative.
Another View: Vistra Through The P/E Lens
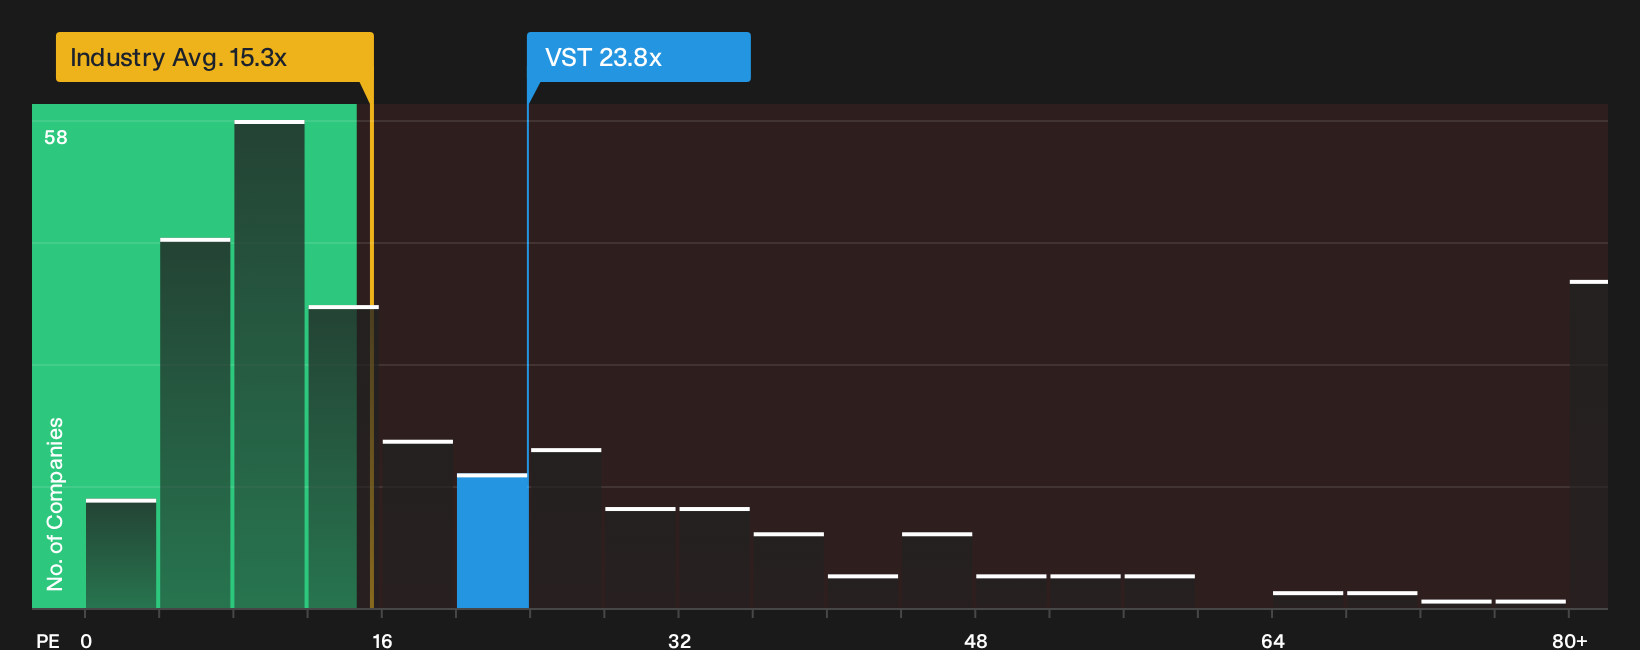
There is a very different read on Vistra when you move away from cash flow models and look at the P/E ratio. The stock trades at 23.8x earnings, while peers average 17.8x and the broader renewable energy group sits near 15.3x. Against a fair ratio of 29.7x, that mix of premium versus peers but discount to the fair ratio raises a simple question. Is the market overpaying compared with competitors, or underpaying if earnings move toward that fair multiple?
To see how that earnings based view stacks up against the wider peer set and where valuation pressure could build, have a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Vistra is clearly split, so use that tension as a prompt to move quickly. Review the data for yourself and weigh both sides of the story through the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Vistra?
If Vistra has you thinking differently about power, do not stop here. Use focused stock lists to spot fresh ideas that match your style and risk comfort.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (23 results) that pair sturdier finances with fundamental support.
- Hunt for mispriced opportunities by reviewing the 29 high quality undervalued stocks where stronger quality meets prices that may not fully reflect fundamentals.
- Prioritise stability and income by checking the 6 dividend fortresses for higher yielding payouts that could suit a more cash focused approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com