
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Insider Buying Highlights Undervalued Small Caps In September 2026
In the last week, the United States market has stayed flat, yet it is up 12% over the past year with earnings forecast to grow by 17% annually. In this context, identifying stocks that are potentially undervalued can be crucial for investors looking to capitalize on growth opportunities, particularly when insider buying signals confidence in a company's prospects.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Cardinal Infrastructure Group | NA | 1.0x | 34.77% | ★★★★★★ |
| Regional Management | 6.3x | 0.5x | 36.59% | ★★★★★★ |
| Union Bankshares | 9.8x | 2.1x | 44.93% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.8x | 2.4x | 27.16% | ★★★★☆☆ |
| Shore Bancshares | 11.7x | 3.4x | 36.54% | ★★★★☆☆ |
| Five Star Bancorp | 15.2x | 6.5x | 44.81% | ★★★☆☆☆ |
| Franklin Financial Services | 11.5x | 3.1x | -40.36% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 10.72% | ★★★☆☆☆ |
| Hanover Bancorp | 20.4x | 2.8x | 35.50% | ★★★☆☆☆ |
| Orion Group Holdings | 101.6x | 0.4x | 46.02% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
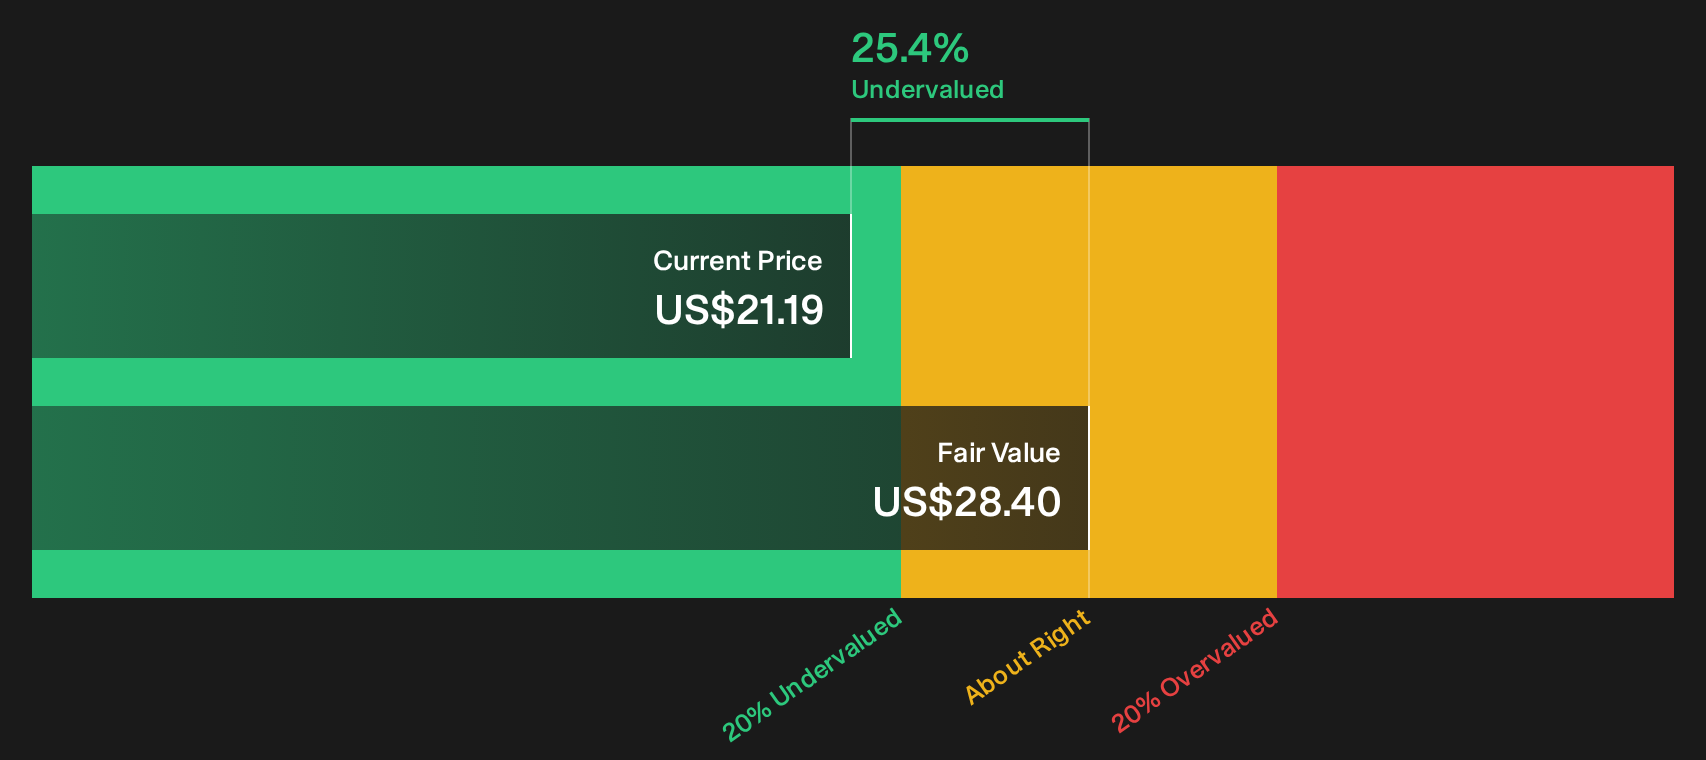
Target Hospitality (TH)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Target Hospitality provides workforce housing and hospitality services, primarily serving the government and various industries, with a market capitalization of approximately $1.45 billion.
Operations: The company's revenue primarily comes from Workforce Hospitality Solutions and Hospitality & Facilities Services - South, with additional contributions from Government contracts. The cost of goods sold (COGS) has fluctuated, impacting the gross profit margin, which reached 68.59% in September 2023 before declining to 31.14% by June 2026. Operating expenses and non-operating expenses further influence net income margins over time.
PE: -54.9x
Target Hospitality, a company with a focus on modular accommodations and hospitality services, recently completed a $259 million equity offering. Their new multi-year contract with a top hyperscaler in West Texas is set to generate $250 million through 2030, showcasing their strategic growth in workforce hospitality solutions. Despite reporting net losses for Q2 2026, they raised full-year revenue guidance to between US$435 million and US$445 million. The firm’s asset-light approach and expanded credit facility enhance financial flexibility for future growth initiatives.
- Delve into the full analysis valuation report here for a deeper understanding of Target Hospitality.
Evaluate Target Hospitality's historical performance by accessing our past performance report.
CI&T (CINT)
Simply Wall St Value Rating: ★★★☆☆☆
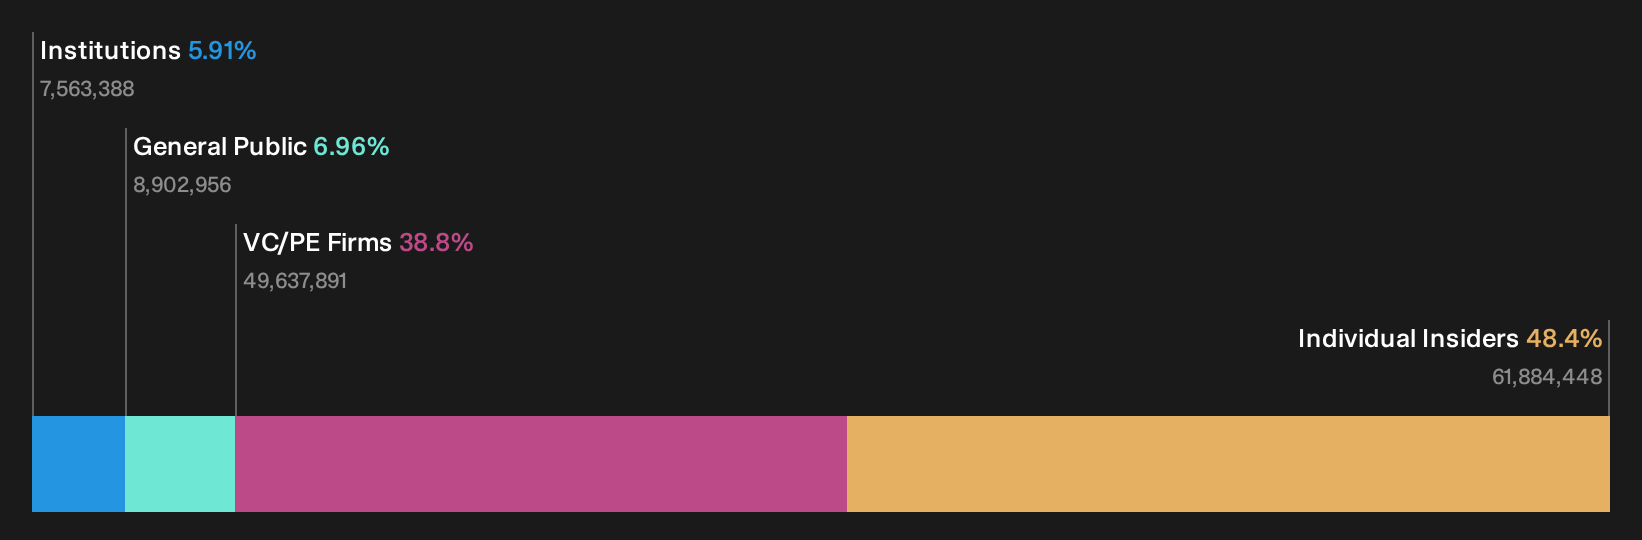
Overview: CI&T is a technology solutions provider specializing in digital transformation for enterprises, with operations focused on computer services and a market capitalization of approximately $1.18 billion.
Operations: The company generates revenue primarily from its Computer Services segment, which reached $541.02 million. Its cost of goods sold (COGS) impacts the gross profit margin, which was 31.16% as of the latest period. Operating expenses include significant allocations to sales and marketing, and general and administrative functions.
PE: 10.9x
CI&T, a company with ambitious growth plans, has seen insider confidence through share purchases in the past quarter. Despite relying on external borrowing for funding, they project earnings growth of 19.17% annually. Recent expansions include launching CI&T Business Builders to address AI-driven challenges and a strategic alliance with Mistral to enhance AI deployment globally. Their updated guidance forecasts revenue between US$565.5 million and US$577.8 million for 2026, indicating strong organic growth potential amidst industry transformation efforts.
- Unlock comprehensive insights into our analysis of CI&T stock in this valuation report.
Gain insights into CI&T's historical performance by reviewing our past performance report.
Trinity Capital (TRIN)
Simply Wall St Value Rating: ★★★★★☆
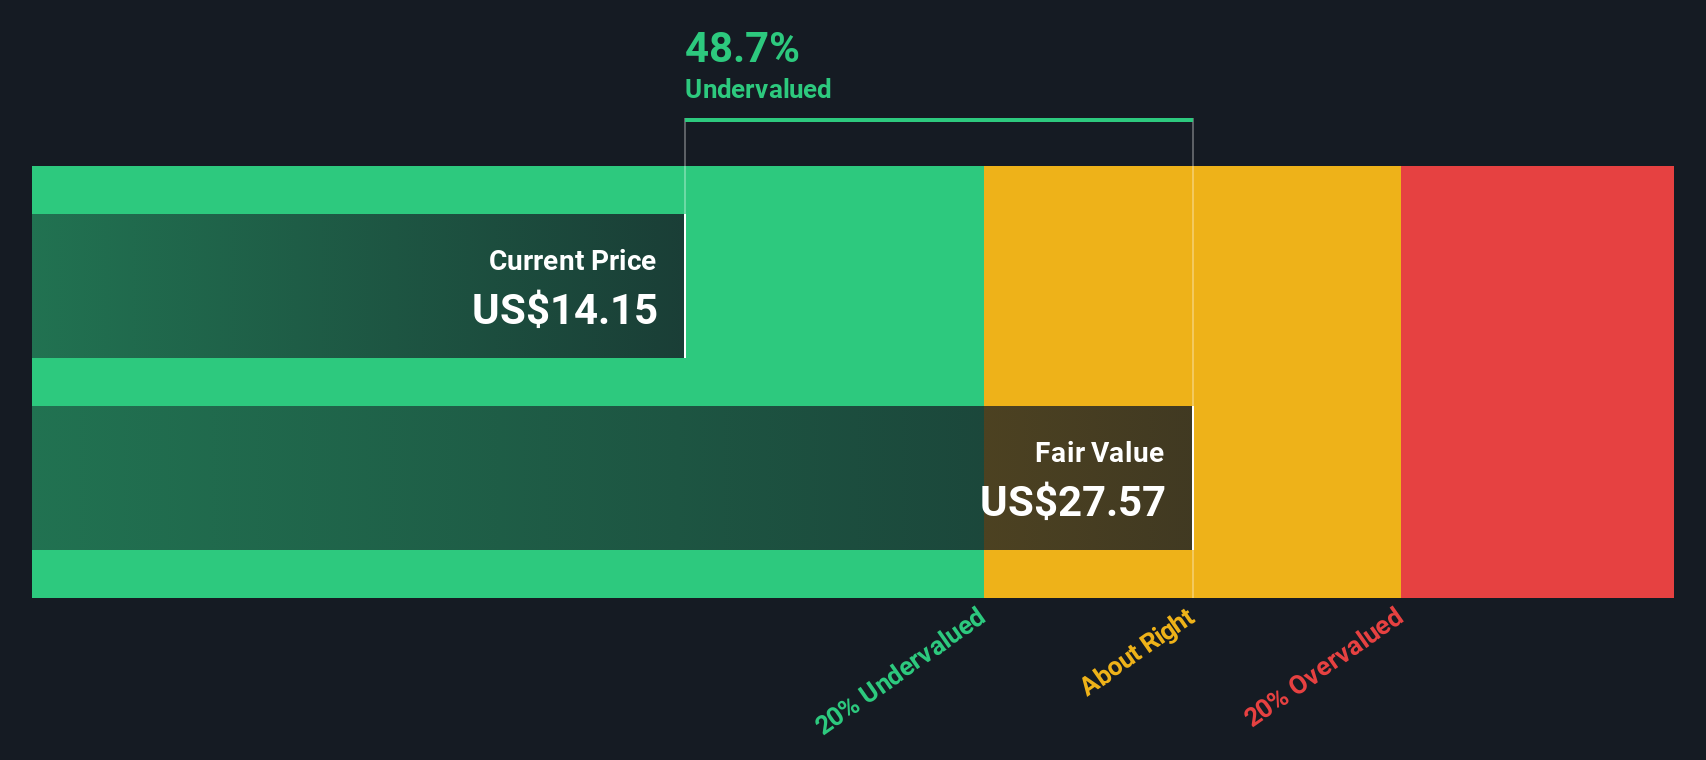
Overview: Trinity Capital is a financial services company specializing in providing venture capital to growth-stage businesses, with a market cap of approximately $0.69 billion.
Operations: Trinity Capital generates revenue primarily from its venture capital segment, with recent figures reaching $313.05 million. The company consistently achieves a gross profit margin of 100%, indicating no direct costs associated with revenue generation. Operating expenses, including general and administrative costs, are notable but do not impact the gross profit margin. Net income margins have shown variability over time, reflecting fluctuations in non-operating expenses and other financial factors.
PE: 12.1x
Trinity Capital, a small company in the U.S., recently declared monthly dividends of US$0.17 per share through December 2026, reflecting steady cash returns to shareholders. While earnings grew to US$87 million in Q2 2026 from US$69 million a year prior, diluted EPS fell to $0.49 from $0.63 due to past shareholder dilution and reliance on external borrowing for funding. Insider confidence remains strong with recent purchases signaling potential growth opportunities despite being removed from the NASDAQ Composite Index in July 2026.
- Take a closer look at Trinity Capital's potential here in our valuation report.
Examine Trinity Capital's past performance report to understand how it has performed in the past.
Next Steps
- Take a closer look at our Undervalued US Small Caps With Insider Buying list of 66 companies by clicking here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com