
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Uncovering Three Undiscovered Gems in the US Market
Over the last 7 days, the United States market has remained flat, yet it has seen a 12% rise over the past year with earnings forecasted to grow by 17% annually. In such an environment, identifying stocks that are not only stable but also poised for growth can be key to uncovering potential opportunities in the market.
Top 10 Undiscovered Gems With Strong Fundamentals In The United States
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Insteel Industries | NA | -1.98% | -26.25% | ★★★★★★ |
| Perma-Pipe International Holdings | 31.47% | 11.47% | 32.99% | ★★★★★★ |
| TOYO | 36.72% | 208.58% | 54.90% | ★★★★★☆ |
| Bank of N.T. Butterfield & Son | 0.11% | 4.35% | 6.80% | ★★★★☆☆ |
| Meridian | 77.88% | -7.73% | -15.61% | ★★★★☆☆ |
| Kingstone Companies | 2.94% | 9.01% | 64.05% | ★★★★☆☆ |
| Deluxe | 191.02% | 0.87% | 5.66% | ★★★☆☆☆ |
| Pangaea Logistics Solutions | 68.85% | -2.42% | -25.03% | ★★★☆☆☆ |
| F&G Annuities & Life | 48.57% | 13.75% | -26.95% | ★★★☆☆☆ |
| GDEV | NA | -1.59% | 54.97% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
Kingstone Companies (KINS)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Kingstone Companies, Inc., operating through its subsidiary Kingstone Insurance Company, offers property and casualty insurance products in the United States with a market cap of $280.84 million.
Operations: Kingstone generates revenue primarily from its property and casualty insurance segment, amounting to $237.70 million. The company's net profit margin is a key financial metric to consider when evaluating its profitability.
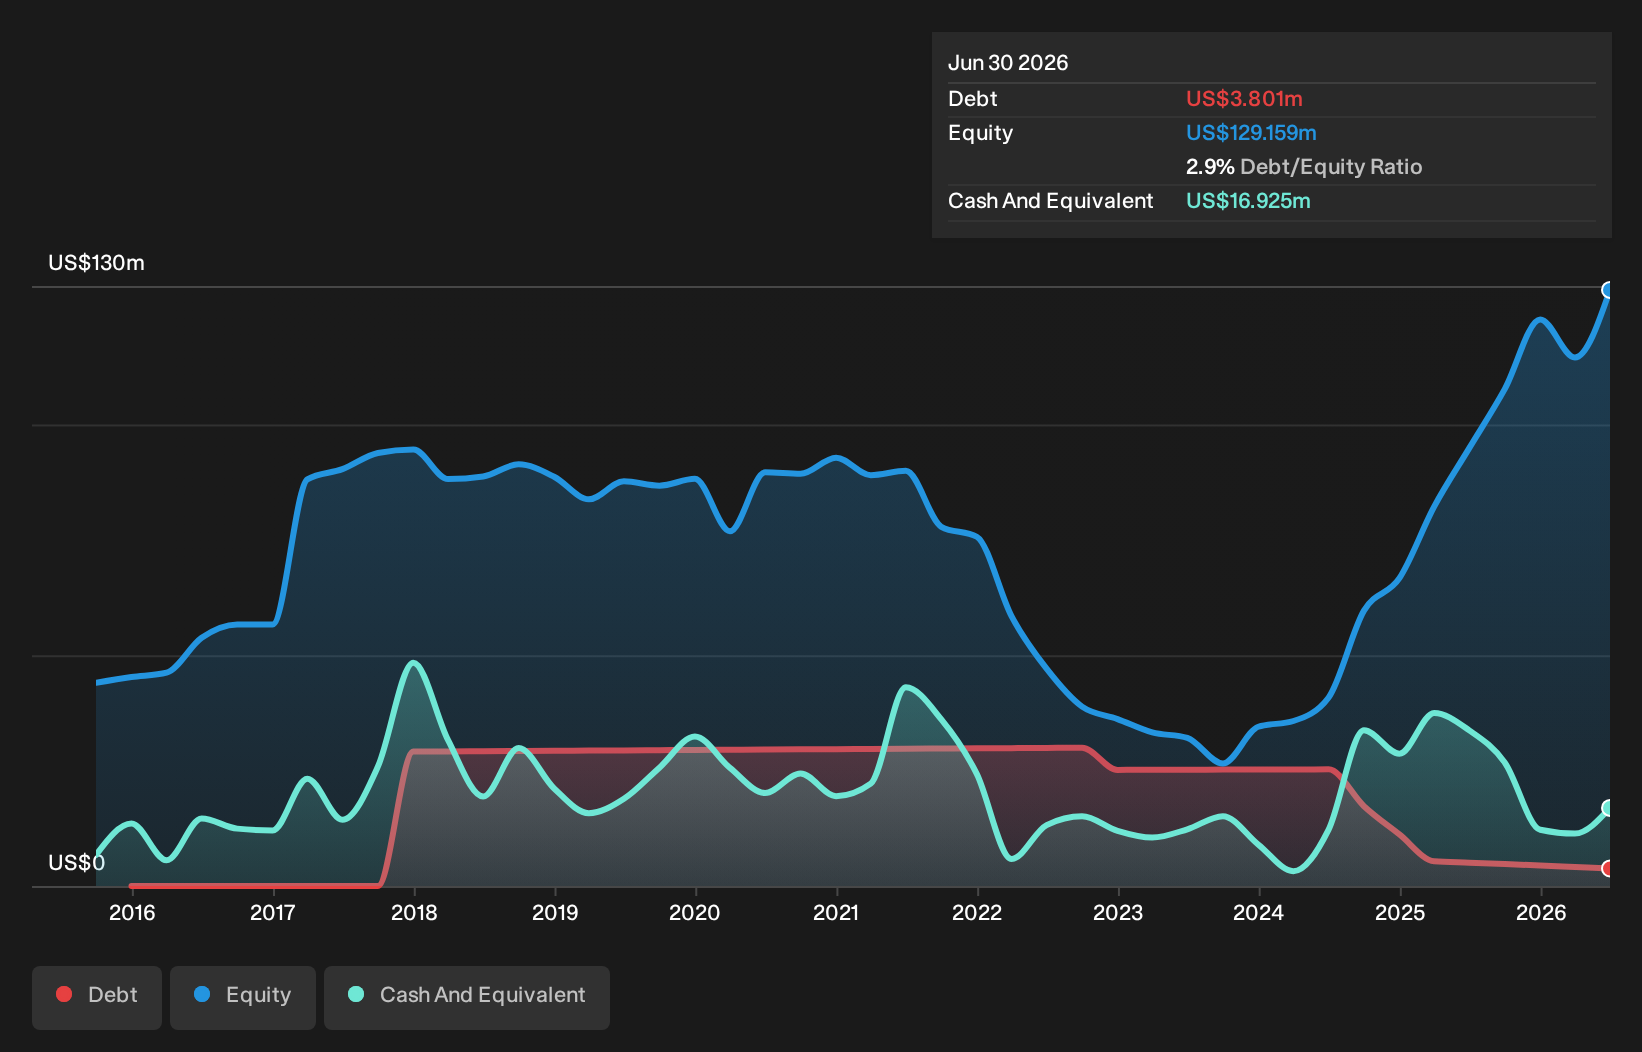
Kingstone Companies, a nimble player in the insurance sector, is showing some promising signs. Its earnings surged by 28% over the past year, outpacing the industry average of 27%. The company’s debt to equity ratio impressively dropped from 33.1% to just 2.9% over five years, indicating stronger financial health. Trading at nearly 43% below its estimated fair value suggests potential for upside. Recent changes include an auditor switch to Deloitte and reaffirmed earnings guidance for fiscal year 2026 with expected net income per share between US$2.20 and US$2.90, reflecting confidence in future performance despite recent index drops.
Kaspi.kz (KSPI)
Simply Wall St Value Rating: ★★★★★☆
Overview: Joint Stock Company Kaspi.kz, along with its subsidiaries, offers payments, marketplace, and fintech solutions for consumers and merchants in Kazakhstan, Azerbaijan, and Ukraine with a market cap of $18.58 billion.
Operations: Kaspi.kz generates revenue primarily through its fintech, payments, and marketplace segments, with fintech contributing KZT 1.71 trillion and marketplace generating KZT 2.15 trillion. The payments segment adds KZT 677.21 billion to the revenue stream.
Kaspi.kz, a prominent fintech entity in Kazakhstan, Azerbaijan, and Ukraine, showcases an intriguing investment profile. Trading at 49.7% below its estimated fair value and boasting high-quality earnings, it presents a compelling case for value seekers. Despite significant insider selling in the last three months and interest payments not well covered by EBIT (2.3x), the company has reduced its debt to equity ratio from 54.8% to 22.2% over five years while maintaining more cash than total debt. Recent dividend hikes reflect confidence in growth prospects despite challenges like increased competition and regulatory hurdles impacting profitability margins slightly from 24.2% to 22.2%.

Bancorp (TBBK)
Simply Wall St Value Rating: ★★★★★☆
Overview: The Bancorp, Inc. serves as the financial holding company for The Bancorp Bank, National Association, offering a range of banking products and services in the United States with a market cap of approximately $2.07 billion.
Operations: The Bancorp generates revenue primarily from its Fintech segment, contributing $263.30 million, and Real Estate Bridge Lending at $102.95 million. Additional income streams include Commercial at $67.93 million, Corporate at $50.53 million, and Institutional Banking at $47.19 million.
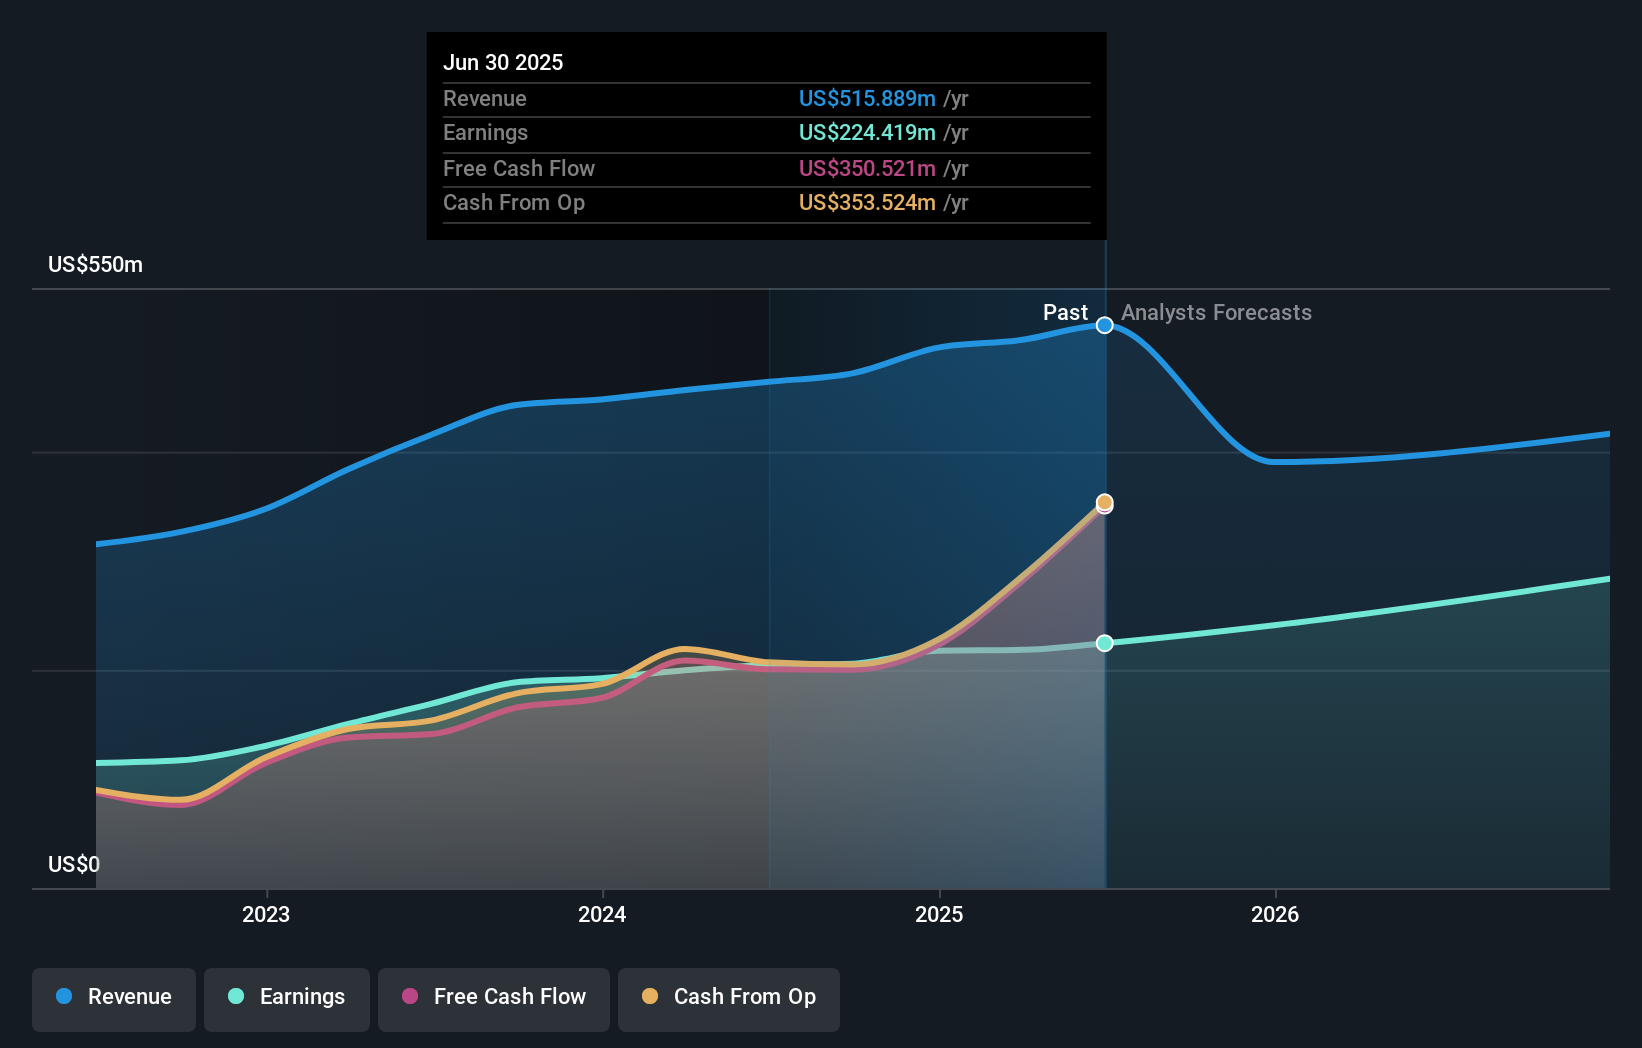
Bancorp, with total assets of US$9.2 billion and equity of US$705.4 million, stands out for its strong reliance on low-risk customer deposits, comprising 88% of its liabilities. Trading at a significant 62.5% below estimated fair value, it offers an attractive proposition compared to industry peers while maintaining an appropriate bad loans ratio at 1.1%. The company has demonstrated consistent earnings growth of 17.5% annually over five years and forecasts a further rise by 19%. Recent buybacks saw the repurchase of over 1.7 million shares for US$100 million, indicating confidence in its valuation strategy and future prospects.
- Dive into the specifics of Bancorp here with our thorough health report.
Assess Bancorp's past performance with our detailed historical performance reports.
Summing It All Up
- Navigate through the entire inventory of 17 US Undiscovered Gems With Strong Fundamentals here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com