
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Sanofi (ENXTPA:SAN) New Flu Vaccine Plant
- Sanofi has opened the Charles Best Building in Toronto, a C$925 million flu vaccine facility that will produce Fluzone High-Dose for older adults and expand end to end manufacturing capacity in Canada, alongside a planned transfer of 20 mature medicines and three plants to Cheplapharm.
- The combination of a large-scale Canadian vaccine build-out and a shift of mature products and sites to Cheplapharm highlights Sanofi’s push to concentrate internal resources on higher value R&D and biologics, while keeping established therapies supplied through a specialist partner.
- The following section examines how Sanofi's investment narrative could be influenced by the Canadian vaccine facility and the related portfolio reshaping.
Sanofi Investment Narrative Recap
To own Sanofi today, you need to believe the business can turn a heavy investment phase into steadier earnings despite pressure on vaccine pricing and mixed R&D outcomes. The key short term swing factor is still execution on high value launches and the broader late stage pipeline, not this single Canadian flu plant.
At the same time, risks around lower net margins, a not fully covered 5.47% dividend and one off losses remain front of mind. The Toronto facility and portfolio reshaping do not remove those issues. They mainly reinforce that Sanofi is committing capital to vaccines while trying to keep mature assets from consuming internal bandwidth.
The planned transfer of 20 mature medicines and three plants to Cheplapharm is the announcement that ties most directly into this vaccine build out. It suggests Sanofi is trying to simplify its manufacturing footprint while keeping long established therapies supplied through a specialist operator, and receiving a 26.4% equity stake in return.
For you as a shareholder, the catalyst to watch is whether this partnership helps Sanofi focus resources on higher value R&D and biologics without operational hiccups or supply issues in the older portfolio. Any disruption at the transferred sites, or slower than expected progress from the refocused pipeline, would lean into the existing margin and execution risks.
Sanofi Earnings And Revenue Assumptions Tied To The Build Out
Sanofi's narrative projects €54.4 billion in revenue and €11.0 billion in earnings by 2029. This assumes 3.6% yearly revenue growth and an earnings increase of about €7.1 billion from €3.9 billion today.
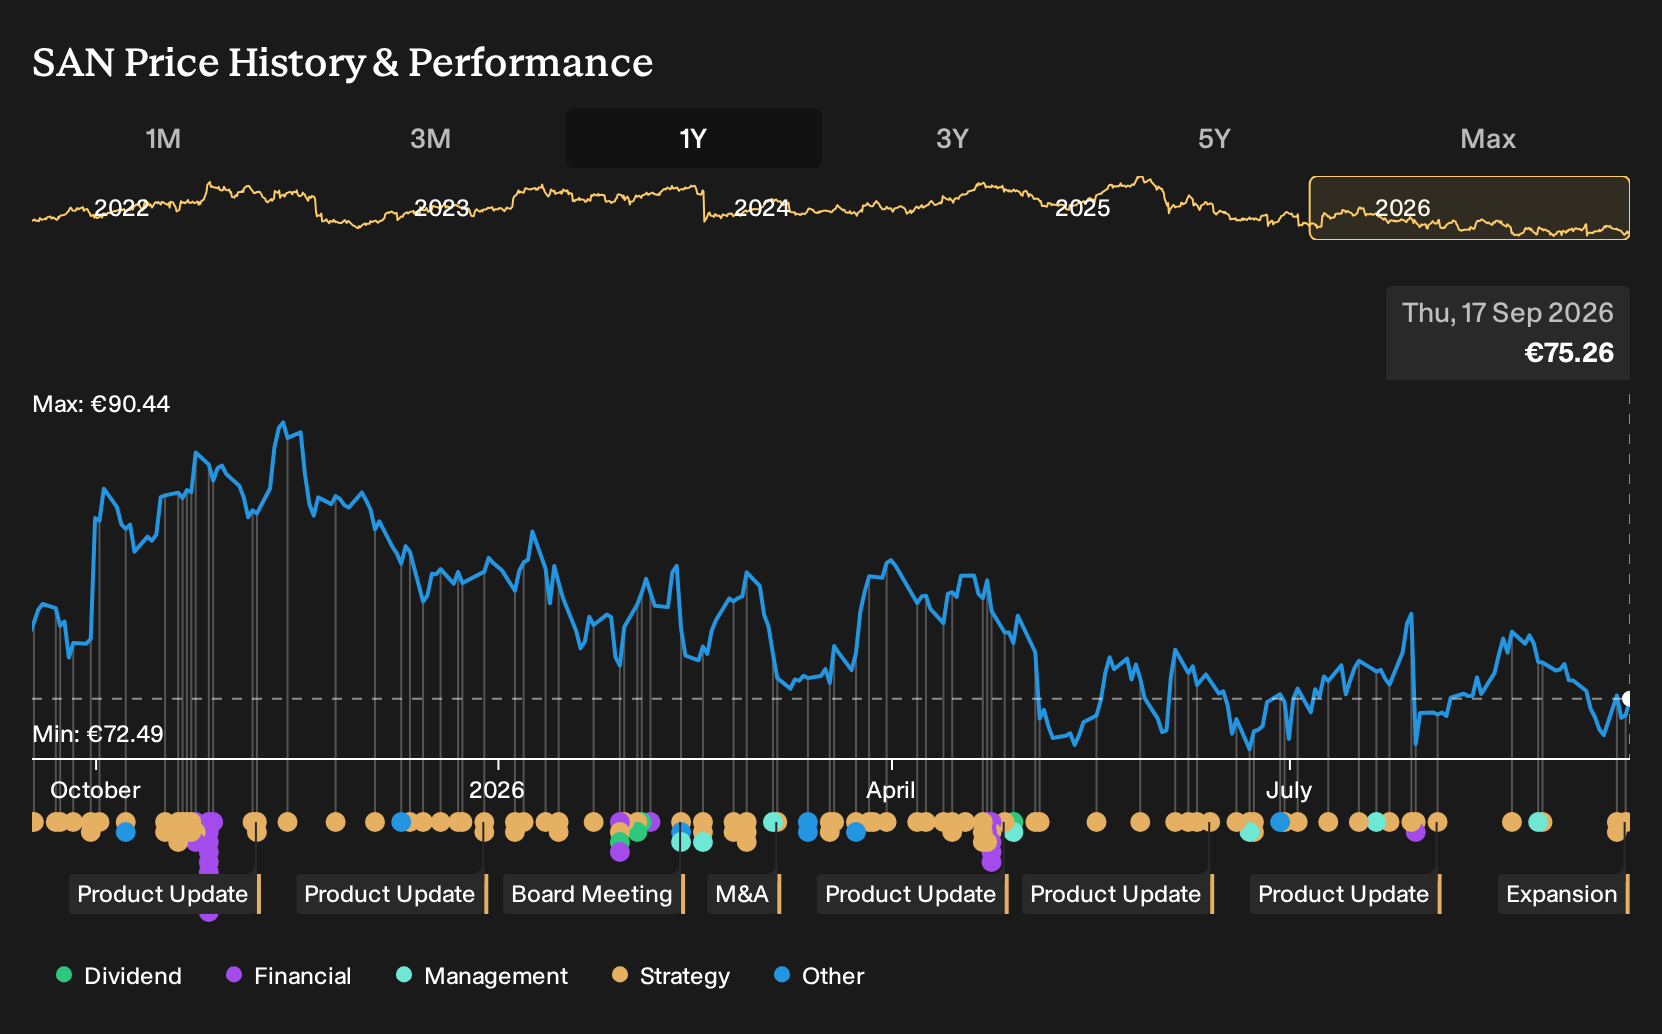
Uncover why Sanofi's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is vaccine concentration risk. The most cautious analysts already saw Sanofi as more fragile here, pencilling in €52.1b of revenue and €9.6b of earnings by 2029, versus the wider group on €54.4b and €11.0b. Those views were set before the Toronto build, so your own take may shift as new data lands.
Explore 8 other Sanofi fair value estimates, including one that suggests it could be worth just €78.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sanofi research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sanofi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanofi's overall financial health at a glance.
Looking For More Sanofi Sized Investment Ideas?
If the Sanofi story has sharpened your focus on balance sheets, cash generation and capital allocation, it can help to scan a wider field of companies that share similar financial traits but operate in very different niches.
- For investors who want potential upside without abandoning financial discipline, consider screening for growth candidates with resilient metrics using the 617 high quality undiscovered gems.
- If capital preservation is near the top of your checklist, filter for businesses with steadier risk profiles and more resilient fundamentals through the 227 resilient stocks with low risk scores.
- Income focused portfolios can benefit from a curated pool of high yield payers, so review companies that combine 5%+ payouts with robust fundamentals using the 158 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com