
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Cullen/Frost Bankers (CFR) Fairly Valued After Its Recent Pullback?
Cullen/Frost Bankers (CFR) is back in focus after commentary highlighting its unexciting sales trends, lagging earnings per share growth compared with banking peers, and a forward price to book multiple of 2.2x.
Recent trading has been choppy for Cullen/Frost Bankers, with the share price slipping 4.6% over the past month after a 9.6% gain across the last 90 days and a 24.55% year to date share price return. The 1 year total shareholder return of 27.65% and 3 year total shareholder return of 92.79% suggest longer term holders have seen much stronger compounding than short term price moves might imply. This helps frame today’s US$159.64 level and the current 2.2x forward P/B as a reassessment of future growth and risk rather than a simple reaction to one headline.
Scan how Cullen/Frost Bankers compares with other financially solid opportunities by reviewing our curated list of solid balance sheet and fundamentals (23 results) for ideas beyond a single regional bank.
Cullen/Frost Bankers trades at US$159.64, with analyst targets and intrinsic estimates pointing higher. The real puzzle is where fair value sits inside that spread after the recent pullback.
Most Popular Narrative: 8% Undervalued
Cullen/Frost Bankers screens as modestly undervalued on the most widely followed narrative, with a fair value estimate of about $174.43 against the $159.64 close, which puts the recent pullback in a different light when stacked against long term earnings and capital return assumptions.
Significant investments in technology and digital banking modernization over the last several years are beginning to yield operating efficiencies and will further lower expense growth relative to revenues, aiding improved profit margins and long-term earnings power from 2026 onward.
See why 4 investors see Cullen/Frost Bankers as 8% undervalued.
Result: Fair Value of $174.43 (UNDERVALUED)
Still, the Cullen/Frost Bankers story can break if Texas takes a hard hit, or if rising funding costs squeeze net interest margin more than expected.
Find out about the key risks to this Cullen/Frost Bankers narrative.
Another View On Cullen/Frost Bankers’ Valuation
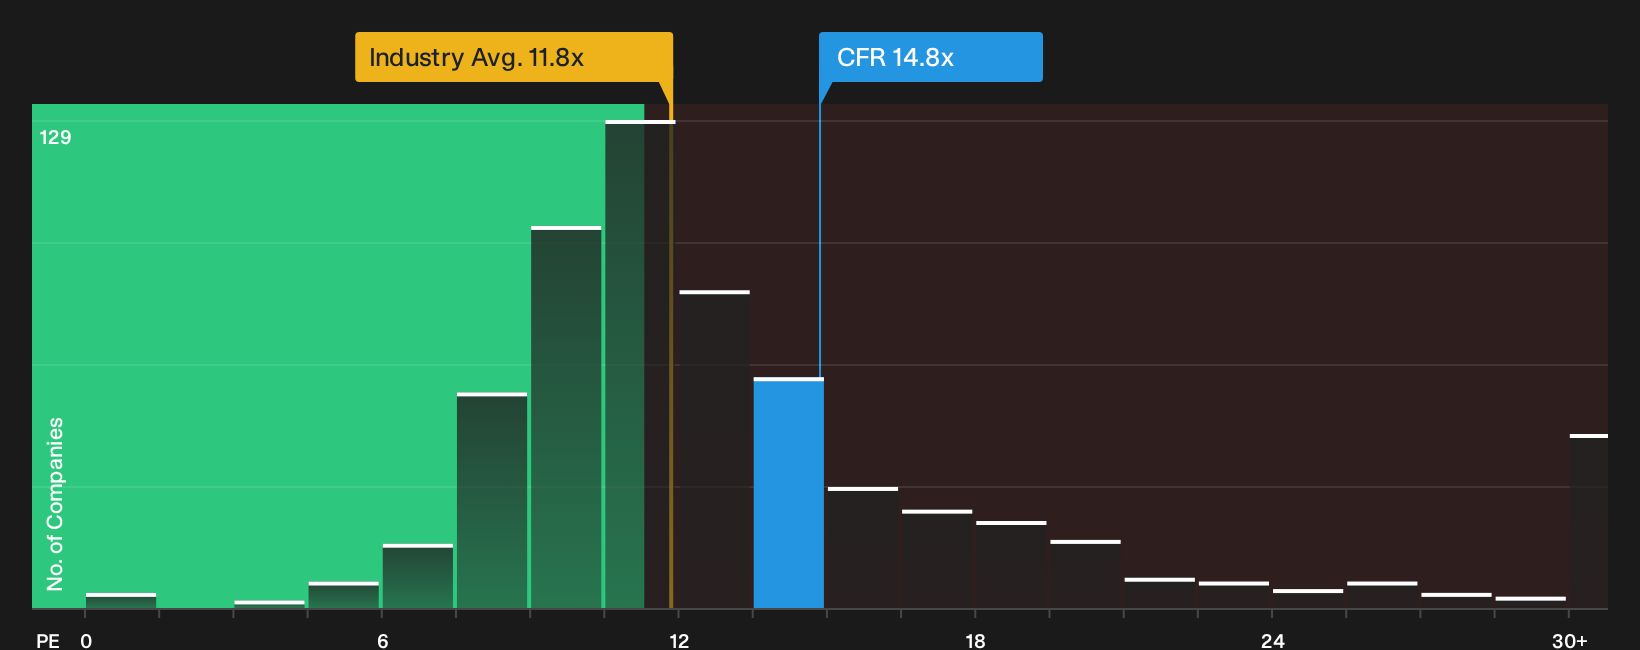
That 8% gap to the US$174.43 fair value is one story. The P/E ratio tells a tougher one. Cullen/Frost Bankers trades on 14.8x earnings, while the US Banks industry averages 11.8x and the peer group sits near 10.4x, with a fair ratio also at 11.8x. Put simply, the stock carries a richer multiple than both sector norms and the fair ratio that the market could move toward. This raises the question of whether you see this as quality worth paying up for or valuation risk that needs a bigger discount.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Cullen/Frost Bankers after all that, or leaning one way already? Move quickly, review the full picture, and weigh the 3 key rewards.
Looking For More Investment Ideas Beyond Cullen/Frost Bankers?
If Cullen/Frost Bankers has you thinking harder about price, quality, and risk, use this moment to widen your hunting ground with focused screeners.
- Target potential mispricings by scanning a curated set of 29 high quality undervalued stocks that pair solid fundamentals with more attractive entry points.
- Strengthen the income side of your portfolio by reviewing 6 dividend fortresses that aim to balance yield with balance sheet support.
- Turn caution into an edge by filtering for 30 resilient stocks with low risk scores that may help smooth returns when markets get jumpy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com