
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DroneShield (ASX:DRO) Could Be 36% Undervalued As New CFO Steps In
Leadership change at DroneShield and why it matters
DroneShield (ASX:DRO) has announced a finance leadership reset, with experienced technology executive Rebecca Lowde set to become CFO while long-serving finance chief and Joint Company Secretary Carla Balanco prepares to depart.
Recent trading has been choppy for DroneShield, with the share price down about 37% over the past 90 days and about 48% year to date, even after a 3.61% 7 day share price return and the CFO appointment news. That short term weakness sits against a very large 5 year total shareholder return. This suggests that the market may be reassessing growth prospects and risk after a strong multi year run rather than reacting only to this leadership change.
Scan how other defence and security hardware plays with similar transformation stories stack up against DroneShield by reviewing the curated list of solid balance sheet and fundamentals (12 results).
The share price has already given back a lot of that multi year gain, yet revenue is still growing and the business is loss making. Is most of DroneShield’s potential already captured in A$1.72, or is there further upside potential in the current price?
Most Popular Narrative: 36% Undervalued
On the most followed narrative, DroneShield screens as undervalued, with a fair value of A$2.70 against the last close at A$1.72. This frames the CFO transition inside a much bigger growth and risk debate.
Surging demand for counter-drone technologies is being driven by ongoing geopolitical instability and heightened security threats, as evidenced by record global and NATO-aligned defense spending and an escalating number of large procurement contracts in DroneShield's pipeline. This is positioning the company for robust, sustained revenue growth.
See why 201 investors see DroneShield as 36% undervalued.
Result: Fair Value of A$2.70 (UNDERVALUED)
Still, DroneShield’s story can change quickly if large defence contracts are delayed or cancelled, or if rising R&D spending weighs more heavily on profitability.
Find out about the key risks to this DroneShield narrative.
Another View: DroneShield looks expensive on sales multiples
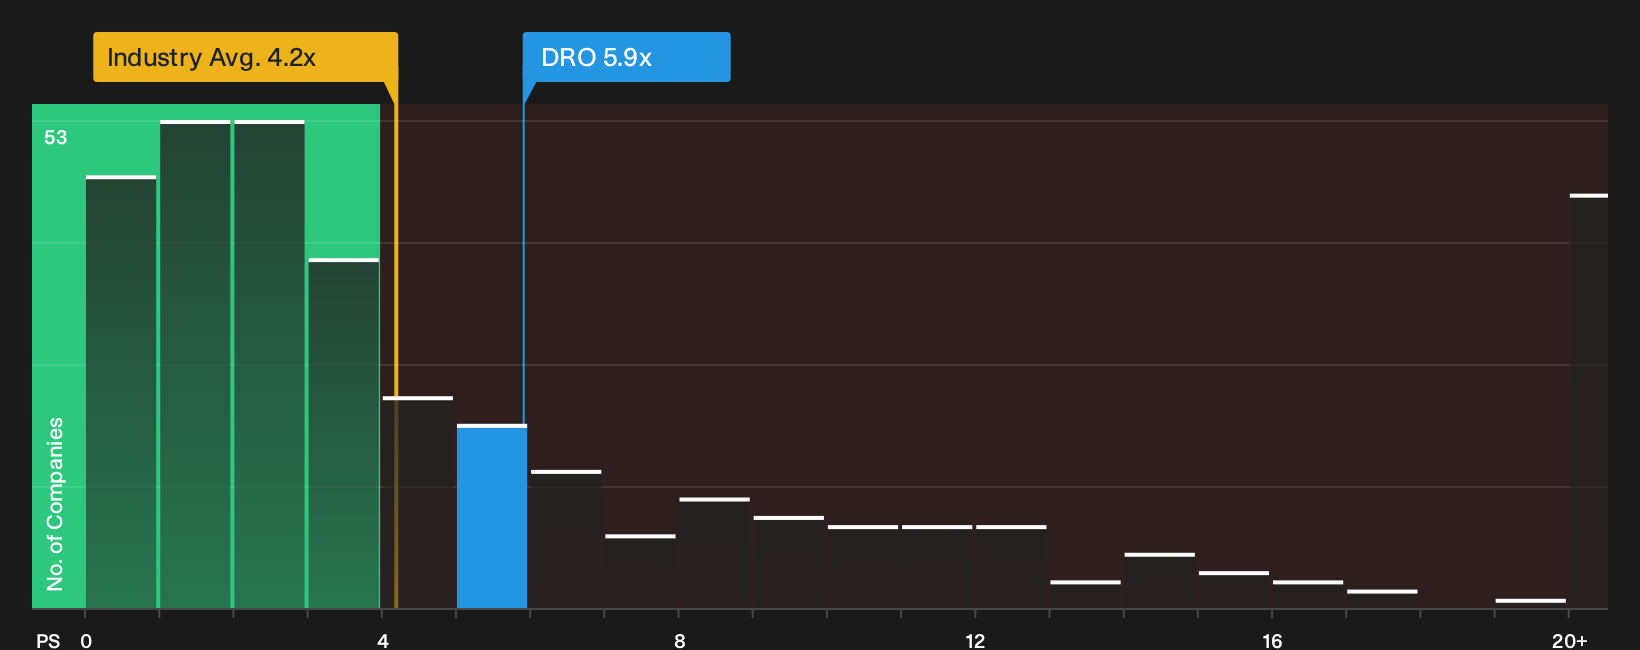
That A$2.70 fair value sits awkwardly beside the current revenue based view. DroneShield trades on a P/S of 5.9x, which is higher than both the global Aerospace & Defense peer average of 4.2x and an estimated fair ratio of 5.5x. If growth or margins slip, this may leave limited room for error in the A$1.72 price.
Our valuation work using this sales ratio points to a rich setup relative to sector peers, the broader industry and the fair ratio that the market could move towards over time. This raises questions about whether expectations have run ahead of fundamentals. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on DroneShield can create noise, so move quickly, review the underlying numbers, and judge the optimism for yourself with the 1 key reward.
Looking for more DroneShield sized investment ideas?
If DroneShield has you thinking harder about risk, reward and timing, do not stop here. Use focused screeners to spot what others might be missing.
- Target value opportunities early by reviewing the 6 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience in your holdings and run through the 7 resilient stocks with low risk scores before the next bout of volatility tells you what you should have owned.
- Get ahead of the crowd and scan the 15 high quality undiscovered gems before capital chases the same small pool of high quality ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com