
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global's Top Undervalued Small Caps With Insider Action For September 2026
In September 2026, global markets have been navigating a challenging landscape marked by heightened geopolitical tensions and rising oil prices, contributing to inflationary pressures and impacting small-cap indices like the Russell 2000. As investors seek opportunities amid these fluctuations, identifying small-cap stocks with strong fundamentals and insider activity can be a strategic approach in this volatile environment.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 39.62% | ★★★★★★ |
| China Aircraft Leasing Group Holdings | 7.2x | 1.0x | 36.36% | ★★★★★☆ |
| Transcontinental | 2.4x | 0.2x | -94.71% | ★★★★☆☆ |
| Franchise Brands | 27.7x | 2.0x | 46.71% | ★★★★☆☆ |
| Primaris Real Estate Investment Trust | 19.0x | 3.5x | 48.69% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 17.29% | ★★★★☆☆ |
| Sagicor Financial | 6.9x | 0.5x | -79.13% | ★★★★☆☆ |
| Firan Technology Group | 35.8x | 2.7x | 25.08% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -219.06% | ★★★☆☆☆ |
| Hong Fok | 23.7x | 6.8x | 30.56% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
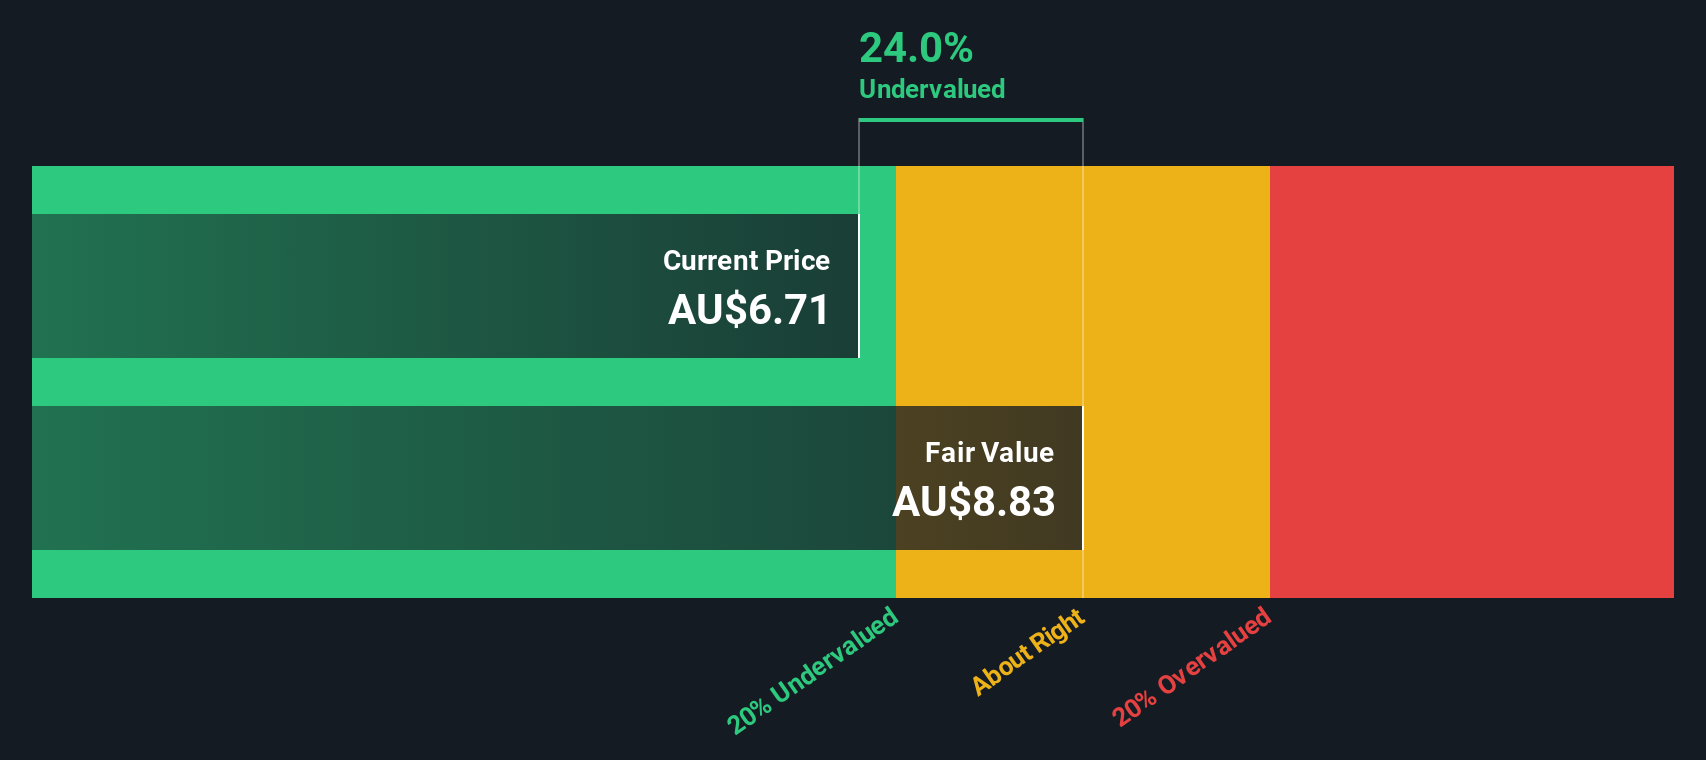
Mader Group (ASX:MAD)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Mader Group specializes in providing staffing and outsourcing services, with a market capitalization of A$1.21 billion.
Operations: The company generates revenue primarily through its Staffing & Outsourcing Services, with recent figures reaching A$1.00 billion. The cost of goods sold (COGS) accounts for a significant portion of expenses, totaling A$805.49 million in the latest period. Operating expenses and non-operating expenses further impact profitability, with operating costs recorded at A$104.02 million and non-operating expenses at A$26.26 million for the same period. The gross profit margin has shown variation over time, recently reported at 19.54%.
PE: 19.6x
Mader Group, a small company focused on strategic growth, is actively pursuing acquisitions to enhance its capabilities and market presence. With insider confidence reflected in recent share purchases, the company plans to repurchase up to A$30 million worth of shares by September 2027. For fiscal 2027, Mader projects revenue of at least A$1.13 billion and net profit after tax of A$72.5 million. This aligns with their strategy of leveraging organic growth alongside targeted acquisitions for accelerated expansion.
Bukit Sembawang Estates (SGX:B61)
Simply Wall St Value Rating: ★★★☆☆☆
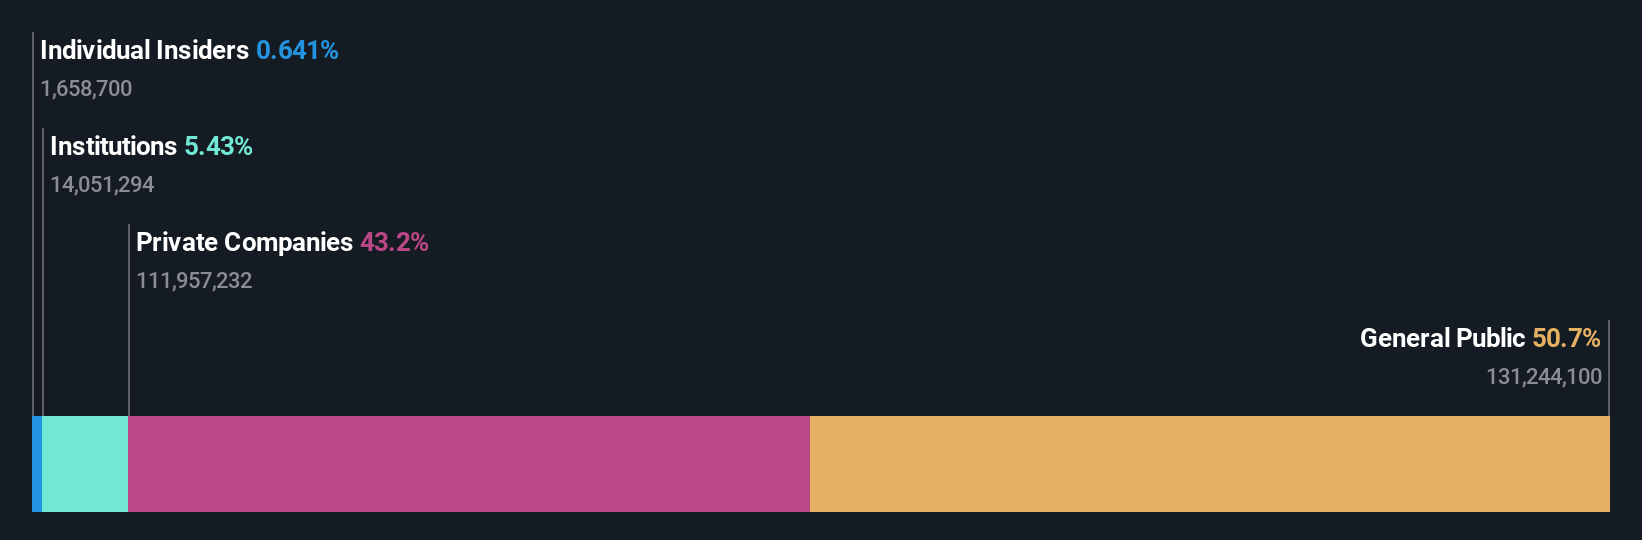
Overview: Bukit Sembawang Estates is primarily engaged in property development, with additional operations in hospitality and investment holding, and has a market capitalization of approximately SGD 1.17 billion.
Operations: The company's primary revenue stream is derived from property development, contributing SGD 334.80 million, alongside smaller segments such as hospitality and investment holding. The cost of goods sold (COGS) significantly impacts the gross profit margin, which has shown a varied trend over time, reaching 47.64% in March 2026. Operating expenses and non-operating expenses also influence the net income margin, which was recorded at 37.23% in March 2026.
PE: 8.8x
Bukit Sembawang Estates, a smaller player in the property sector, recently announced an 18-cent special dividend per share for FY ending March 2026. This signals potential value despite forecasts of declining earnings by 6% annually over the next three years. Insider confidence is evident with Chien Shih Lee purchasing 26,400 shares valued at approximately S$116,157. The company relies on external borrowing but maintains high-quality earnings. Leadership changes include the retirement of long-serving Chairman Koh Poh Tiong.
Transcontinental (TSX:TCL.A)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Transcontinental is a Canadian company primarily involved in retail services and printing, with operations generating revenue from these segments, and it has a market capitalization of approximately CA$1.46 billion.
Operations: The company generates revenue primarily from Retail Services and Printing, with the latter contributing CA$1.07 billion. The gross profit margin has shown variability, reaching 25.71% in April 2018 before declining to 15.51% by October 2023. Operating expenses have remained a significant component of costs alongside non-operating expenses and depreciation & amortization charges over the periods analyzed.
PE: 2.4x
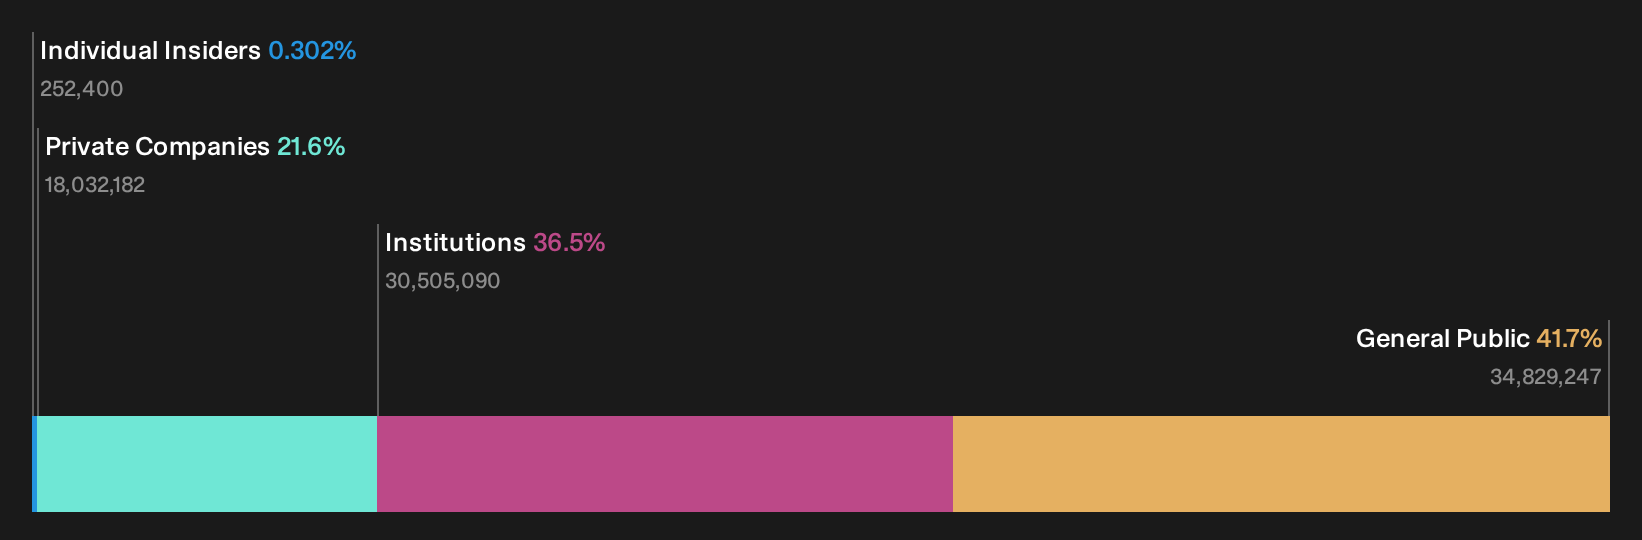
Transcontinental, a smaller company in its sector, recently reported third-quarter sales of C$306 million, up from last year's C$294.9 million. However, net income slightly decreased to C$36.5 million from C$38.7 million previously. Despite this dip, insider confidence is evident as they purchased shares between June and August 2026. The company's reliance on external borrowing poses risks despite its steady dividend of C$0.05 per share announced for October 2026 payouts. Earnings are projected to decline by an average of 47% annually over the next three years, suggesting challenges ahead amidst potential value opportunities for discerning investors.
- Get an in-depth perspective on Transcontinental's performance by reading our valuation report here.
Gain insights into Transcontinental's past trends and performance with our Past report.
Seize The Opportunity
- Dive into all 111 of the Undervalued Global Small Caps With Insider Buying we have identified here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com