
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Discovering Undiscovered Gems in Global Markets September 2026
As global markets navigate a landscape marked by heightened geopolitical tensions and inflationary pressures, small-cap stocks have faced particular challenges with indices like the Russell 2000 dropping significantly. Despite these headwinds, opportunities remain for investors seeking potential growth in undiscovered gems that can thrive amid economic shifts and evolving market dynamics. Identifying such stocks often involves looking for companies with strong fundamentals, innovative business models, or unique competitive advantages that position them well even in uncertain times.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Alexandria Group Oyj | 5.79% | 6.84% | 8.17% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Chengtun Mining Group (SHSE:600711)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Chengtun Mining Group Co., Ltd. operates in the non-ferrous metal mining sector both within China and internationally, with a market capitalization of approximately CN¥32.68 billion.
Operations: Chengtun Mining Group generates revenue primarily from its non-ferrous metal mining operations. The company's financial performance is influenced by its cost structure and market conditions in the mining sector. Net profit margin trends provide insights into its profitability over time, reflecting the balance between revenue generation and cost management.
Chengtun Mining Group, a promising player in the mining sector, has shown robust earnings growth of 39.8% over the past year, outpacing the industry average of 23.3%. The company's net income for H1 2026 reached CNY 1.80 billion, up from CNY 1.05 billion a year ago, with basic earnings per share increasing to CNY 0.595 from CNY 0.341. Despite its high net debt to equity ratio of 52.9%, Chengtun's interest payments are well covered by EBIT at a healthy multiple of 10.2x, indicating strong operational efficiency and financial management within this small-cap space.
- Navigate through the intricacies of Chengtun Mining Group with our comprehensive health report here.
Explore historical data to track Chengtun Mining Group's performance over time in our Past section.

Hengyi Petrochemical (SZSE:000703)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Hengyi Petrochemical Co., Ltd. is engaged in the production and sale of chemical fiber products both domestically and internationally, with a market capitalization of approximately CN¥60.99 billion.
Operations: Hengyi Petrochemical generates revenue primarily from its Chemical Fiber Industry, contributing CN¥66.55 billion, followed by the Petrochemical Industry at CN¥53.79 billion and Supply Chain Services at CN¥4.54 billion.
Hengyi Petrochemical, a relatively smaller player in its sector, has showcased remarkable financial performance recently. The company's earnings skyrocketed by 19,322% over the past year, outpacing the Chemicals industry's growth of 3.2%. Despite a high net debt to equity ratio of 140.1%, interest payments are well covered with an EBIT coverage of six times. Trading at about 45% below estimated fair value suggests potential undervaluation compared to peers and industry standards. Recent dividend announcements highlight shareholder returns with CNY 9 per 10 shares declared for interim profit distribution in September 2026, reflecting robust profitability and strategic capital management.
- Get an in-depth perspective on Hengyi Petrochemical's performance by reading our health report here.

PFISTERER Holding (XTRA:PFSE)
Simply Wall St Value Rating: ★★★★★☆
Overview: PFISTERER Holding SE specializes in manufacturing and selling cable fittings, insulators for overhead lines, and components for energy networks and renewable energy generation, with a market cap of €1.24 billion.
Operations: The company's primary revenue streams include High Voltage Cable Accessories (€312.89 million) and Overhead Lines (€137.51 million), with Medium Voltage Cable Accessories contributing €84.68 million and Components adding €124.60 million to the total revenue.
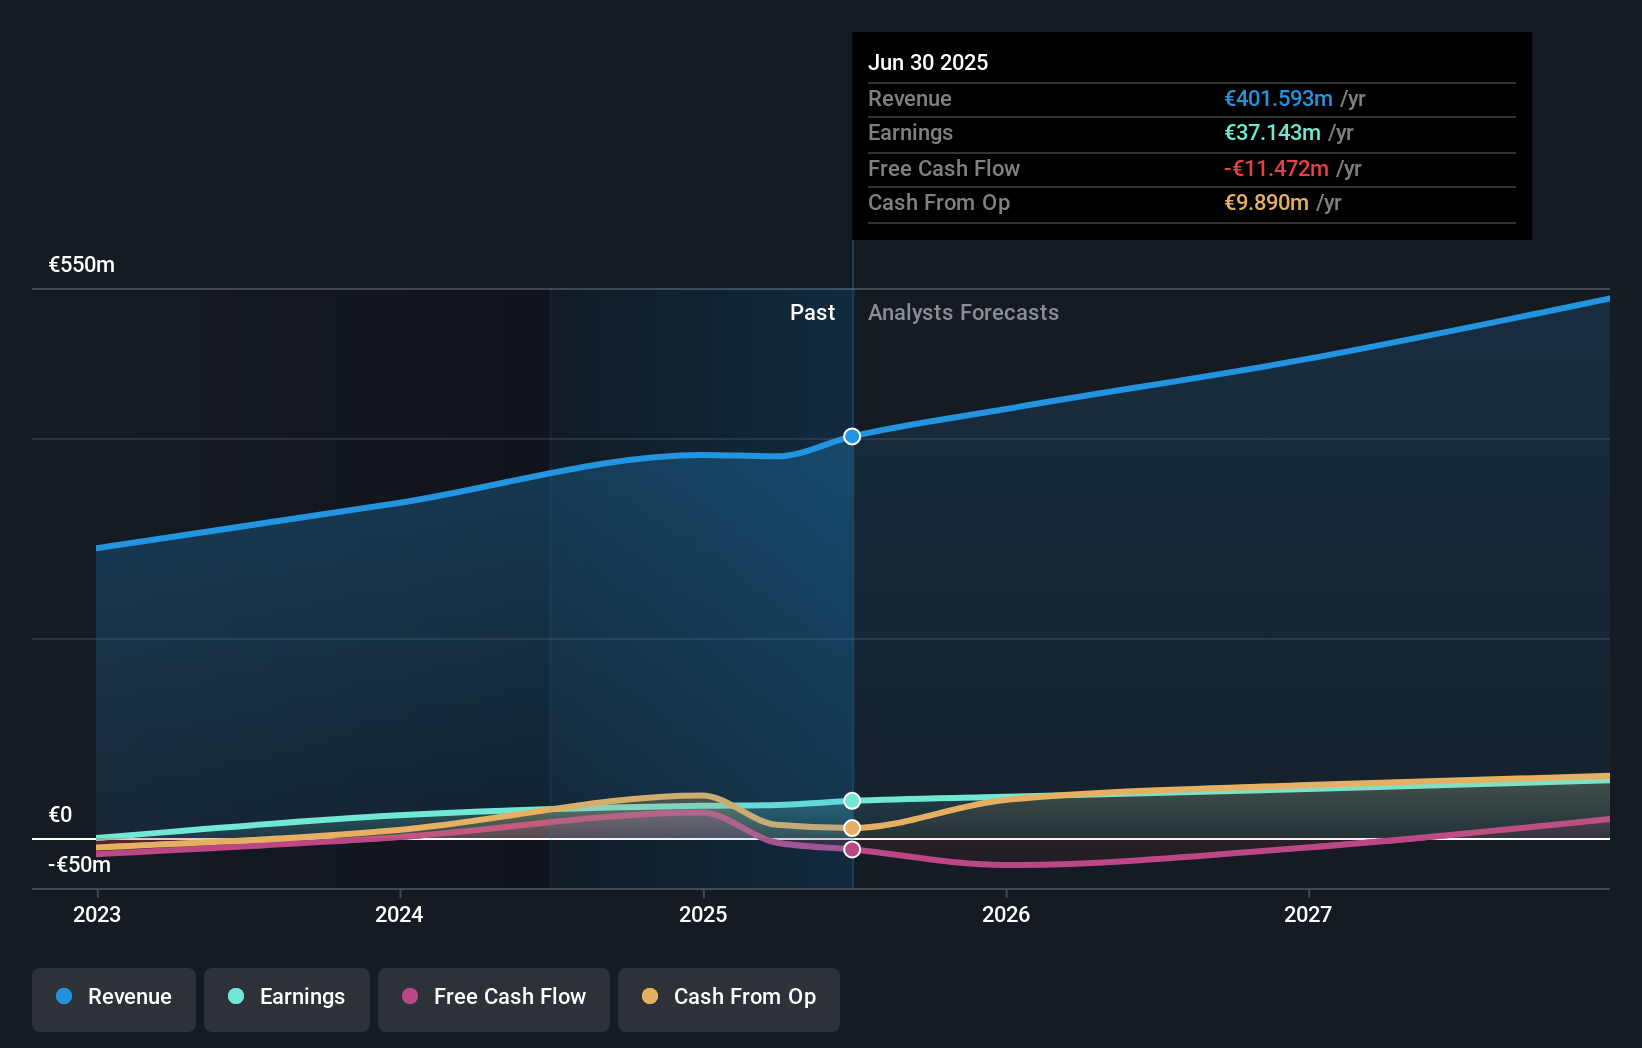
PFISTERER Holding has been making waves with its strategic expansions and robust financial performance. The company recently reported a significant increase in sales, reaching €256.7 million for the first half of 2026, up from €213.56 million the previous year, while net income jumped to €37.94 million from €21.43 million. Earnings per share also saw an uptick to €2.09 compared to last year's €1.38. With a keen focus on enhancing its production capabilities in both the U.S and Czech Republic, PFISTERER is positioning itself as a formidable player in the electrical industry by boosting local manufacturing and reducing delivery times through its "Local-for-Local" strategy—an approach that seems likely to enhance operational efficiency and market responsiveness significantly.
Make It Happen
- Embark on your investment journey to our 163 Global Undiscovered Gems With Strong Fundamentals selection here.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com