
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AMDS Approval Could Be A Big Test For Artivion Stock (AORT)
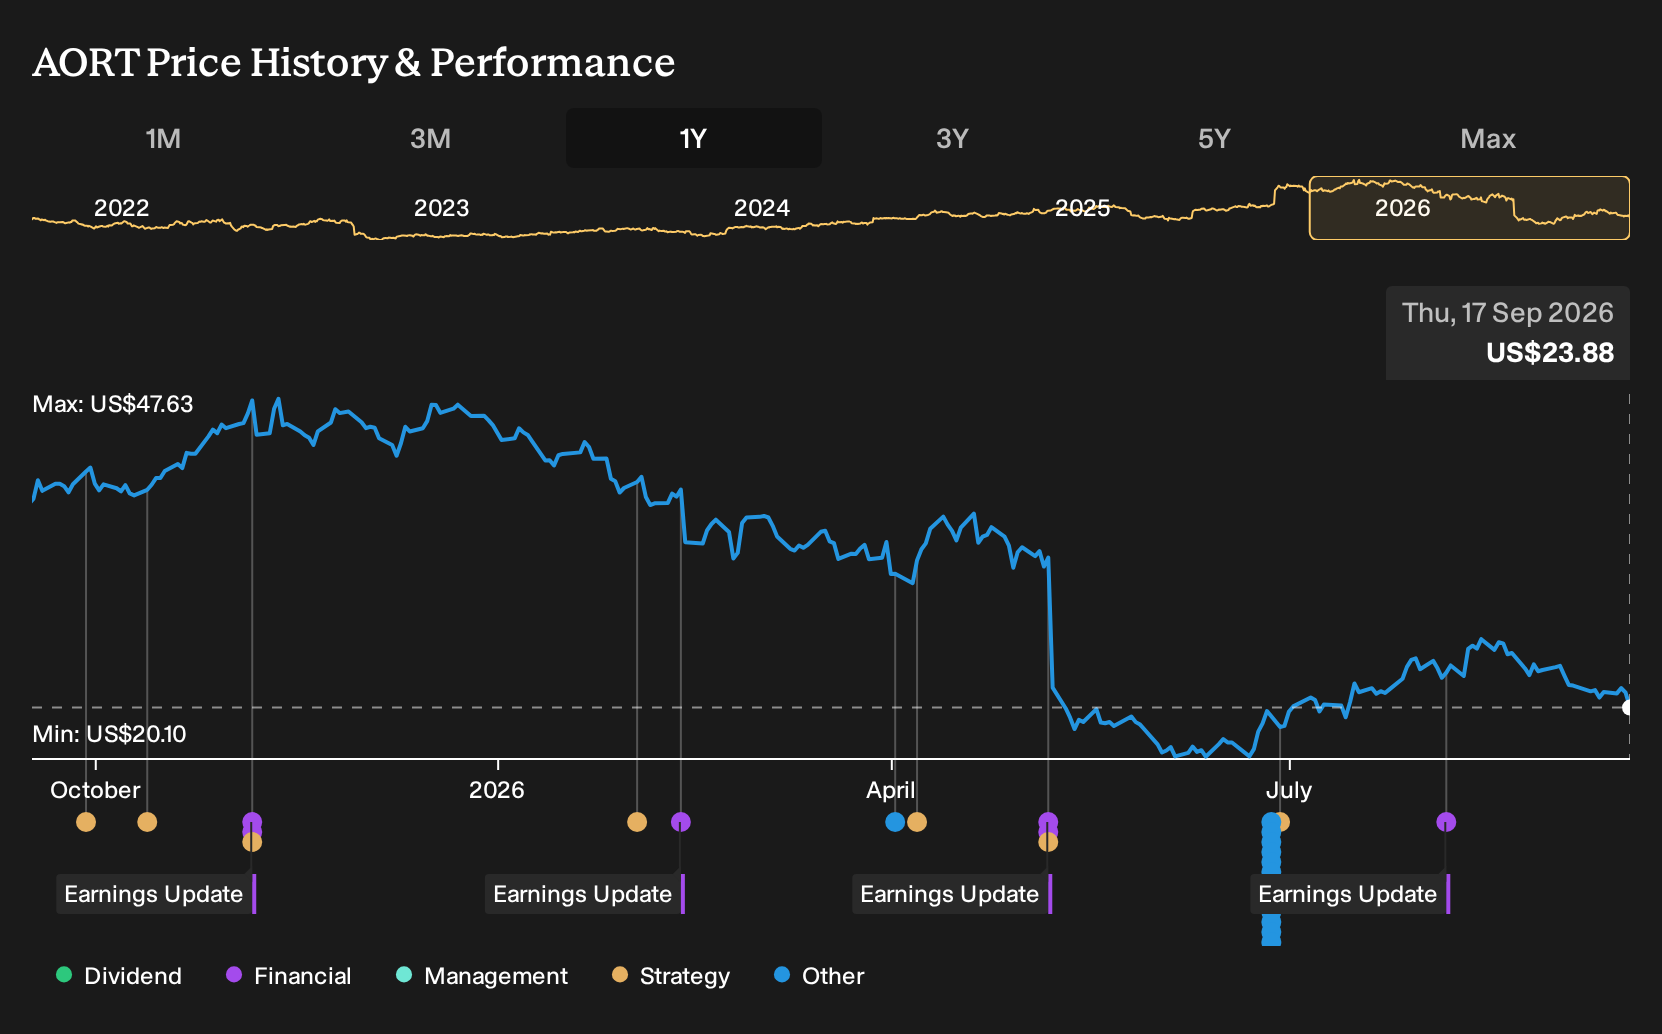
- Artivion reported second quarter 2026 revenue growth of 11% but moved from a profit a year earlier to a net loss of US$13.5 million, while completing the Endospan acquisition and securing FDA approval for the AMDS Hybrid Prosthesis.
- The FDA clearance of AMDS and the integration of Endospan give Artivion what management describes as the only complete aortic arch portfolio. However, full year revenue guidance was reiterated, which underlines ongoing cost and profitability pressures.
- We will now examine how Artivion's investment narrative is affected by the AMDS approval alongside a net loss in spite of double digit revenue growth.
Look beyond Artivion and compare its growth versus profitability trade off with other medtech names using our curated list of list of solid balance sheet and fundamentals (23 results).
Artivion Investment Narrative Recap
To own Artivion, you need to believe that its specialized aortic and heart valve portfolio can translate steady revenue growth into consistent profitability, despite the current net loss. The recent 11% quarterly revenue increase alongside a US$13.5 million loss keeps that core question wide open. The near term depends on whether new products like AMDS and the acquired Endospan line can scale without further eroding margins.
The biggest short term catalyst is execution on the combined aortic arch offering in the U.S. and Europe, where physician adoption and procedure volumes matter more than headlines. The main risk is that integration costs, regulatory spend and debt servicing keep outpacing gross profit, which would limit flexibility for future R&D and any further portfolio expansion.
The most relevant update here is the FDA approval of the AMDS Hybrid Prosthesis. That clearance gives Artivion a full aortic arch suite when combined with Endospan products, which is exactly where much of the growth narrative has been anchored. The product range now matches the story investors have been hearing for several years.
For catalysts, the key factor is how quickly AMDS usage builds within existing accounts and whether it meaningfully pulls through On X valves and other grafts. Execution risk sits on the other side of that coin. Slower than expected adoption, reimbursement pushback, or higher than planned support costs would weigh on margins and delay any improvement in earnings quality.
Artivion's current earnings of $11.7 million are set against analyst expectations for $44.7 million by 2029. This implies roughly a 3.8x increase in profit, based on forecast annual revenue growth of 10.6% and projected 2029 revenues of $619.8 million.
Discover why Artivion's fair value suggests a 76% potential upside to its current price before other investors narrow the gap.
Exploring Other Perspectives
Some of the most optimistic analysts were already treating AMDS as the main accelerator for Artivion, projecting about 12.3% annual revenue growth and earnings of roughly US$49.3 million by 2029. You might see those targets as ambitious after a US$13.5 million loss, or as a starting point that could shift once this new approval is fully digested.
Explore another Artivion fair value estimate, including one that suggests as much as 76% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Artivion research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Artivion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Artivion's overall financial health at a glance.
Looking For More Investment Ideas Beyond Artivion?
If Artivion has sharpened your view on risk, growth, and profitability trade offs, it can help to widen the lens and compare it with other businesses that fit specific criteria on balance sheet strength, valuation, and income potential.
- For readers who want financial resilience front and centre, start with a list of solid balance sheet and fundamentals (23 results) that can better withstand shocks than more fragile peers.
- If value is your priority, scan a curated set of 29 high quality undervalued stocks that combine quality fundamentals with prices that do not fully reflect those traits.
- Income focused investors can put yield and stability side by side by reviewing 6 dividend fortresses that aim to pair higher payouts with more durable cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com