
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
EverCommerce (EVCM) Dropped, So What Is Behind The Fresh Attention?
EverCommerce (EVCM) has put a larger repurchase program on the table, expanding its equity buyback authorization by an additional $25 million to $325 million and extending the plan through December 31, 2027, a move closely watched by investors.
Set against that larger buyback, EverCommerce’s recent share price moves have been mixed, with the stock falling 3.4% on the day to US$7.68 yet rising 17.6% over the past week after a 23.1% decline over 30 days. The 33.5% drop in the year to date share price return and the 36.8% slide in the 1 year total shareholder return suggest longer term momentum has been weak, so this repurchase extension is landing in a period in which investors have been reassessing both risk and the value they place on the business.
Compare EverCommerce’s buyback move with other software players by scanning 29 high quality undervalued stocks that could be setting up for their own sentiment reset following recent price pressure.
EverCommerce is buying back more stock while trading around US$7.68, and analyst targets and intrinsic estimates sit meaningfully higher. How wide is that valuation gap, and what does the fair value range really look like?
Most Popular Narrative: 41% Undervalued
Against EverCommerce’s last close at $7.68, the most followed narrative anchors fair value at $13.00, which paints a wide valuation gap and puts the new buyback in a different light for anyone tracking long term compounding.
Analyst consensus sees embedded payment adoption as a margin lift, but with only low single-digit percentage penetration at top payment solutions that are growing total payment volume by over 12% year over year, there is potential for explosive payments-driven operating leverage, with payments potentially comprising well above 30% of consolidated revenue over time, driving gross margin and EBITDA margin expansion well above current expectations.
See why 0 investors see EverCommerce as 41% undervalued.
Result: Fair Value of $13.00 (UNDERVALUED)
Still, EverCommerce’s dependence on small business customers, along with ongoing acquisition execution risk, could quickly challenge this upbeat narrative if conditions or integrations disappoint.
Find out about the key risks to this EverCommerce narrative.
Another View On EverCommerce’s Valuation
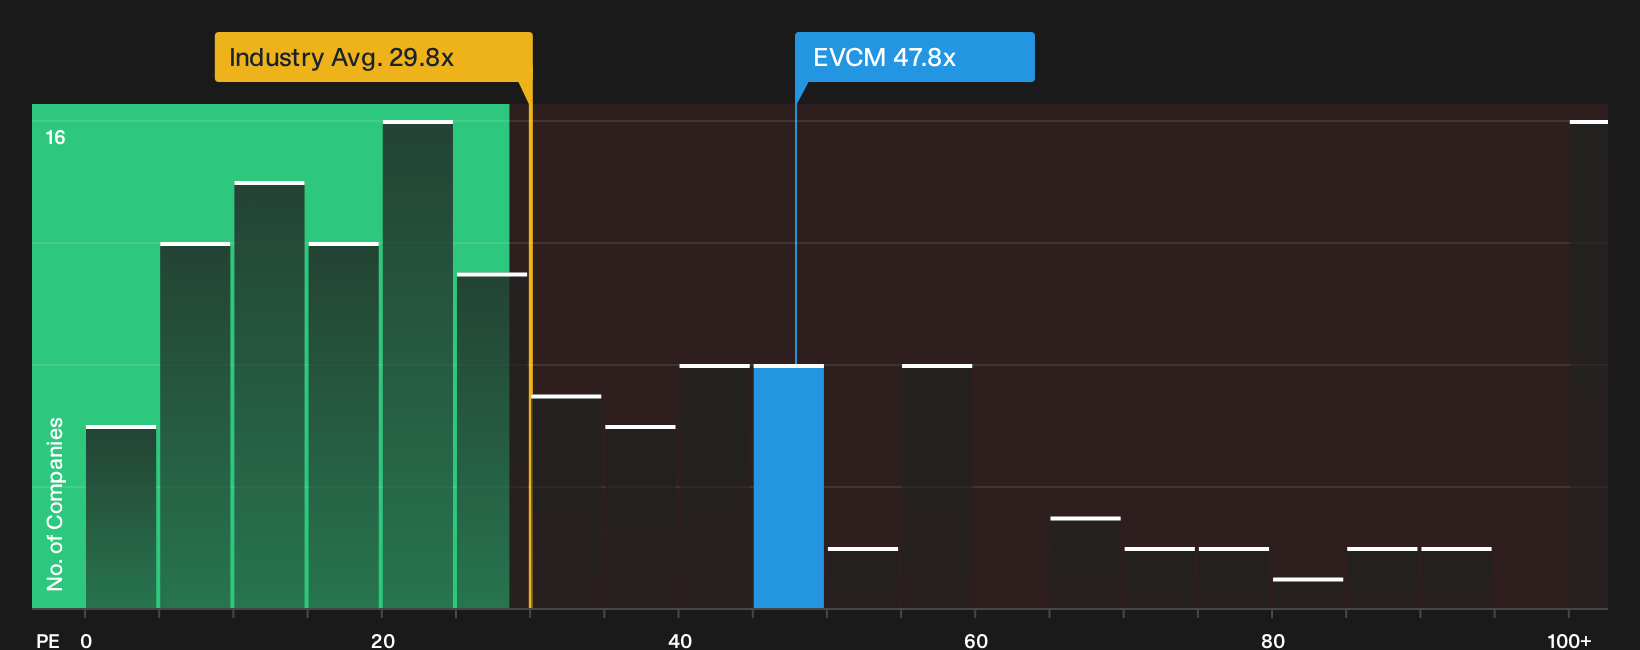
Multiples tell a different story for EverCommerce. The stock trades on a P/E of 47.8x versus 30.3x for the US Software industry and 25.2x for peers, while the fair ratio sits at 37.6x. That rich premium suggests less cushion if the bullish narrative stumbles. Which story do you trust?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around EverCommerce can either be noise or a turning point. Consider reviewing the figures yourself, assessing the situation promptly, and weighing 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond EverCommerce?
If EverCommerce has sharpened your focus on pricing and risk, consider broadening your watchlist with a few targeted stock ideas that can play different roles in a portfolio.
- Target potential mispricings by scanning companies screened as 29 high quality undervalued stocks that combine solid fundamentals with more attractive entry points.
- Build a steadier income stream by checking out 6 dividend fortresses that concentrate on higher yielding payers with staying power.
- Strengthen your downside protection by reviewing 30 resilient stocks with low risk scores designed to highlight businesses with more resilient risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com