
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Fortescue (ASX:FMG) Still Undervalued As It Appeals The Record Compensation Ruling?
Why Fortescue’s Legal Appeal Matters For Investors
Fortescue (ASX:FMG) has challenged a record A$150.3 million Federal Court compensation ruling to Pilbara traditional owners, even after paying the full amount within 24 hours, keeping legal and relationship risks firmly in focus.
At around A$16.73, Fortescue’s 30 day share price return is down 7.36% and the 90 day move is down 15.29%, while the 1 year total shareholder return is down 5.47% but still up 64.71% over five years. This points to weaker recent momentum on top of a much stronger longer term outcome.
Scan the iron ore sector beyond Fortescue by exploring other miners and related producers through our curated list of 16 top copper producer stocks.
With Fortescue shares weaker over the past quarter but still well ahead over five years, the key question now is whether to step in at A$16.73 or wait for a lower entry as the valuation becomes more attractive next.
Most Popular Narrative: 3% Undervalued
On the most followed view, Fortescue’s fair value of about A$17.32 sits modestly above the last close at A$16.73. This puts legal appeals, green spending and China exposure at the centre of how investors weigh that gap.
The market appears to be pricing in continued robust iron ore demand from China, driven by a belief in ongoing mega-infrastructure projects and resilient steel consumption. This assumes that elevated Chinese demand can offset global industry headwinds. Should this prove optimistic, Fortescue's future revenue could disappoint.
See why 135 investors see Fortescue as 3% undervalued.
Result: Fair Value of A$17.32 (UNDERVALUED)
Still, that 89% revenue exposure to China and ongoing decarbonisation spending could upset the 3% undervalued thesis if demand or project costs shift materially.
Find out about the key risks to this Fortescue narrative.
Another View On Fortescue’s Value
While the most followed narrative sees Fortescue as about 3% undervalued at A$16.73 against a fair value of A$17.32, the SWS DCF model paints a very different picture. On that cash flow view, Fortescue at around A$16.75 trades well above an estimated future cash flow value of A$10.28, which points to an overvalued outcome instead.
One approach leans on earnings, margins and analyst forecasts. The other leans on long term cash generation. As an investor, which set of assumptions do you trust more, given that the legal, China and decarbonisation debates all feed into those cash flow lines?
Look into how the SWS DCF model arrives at its fair value.
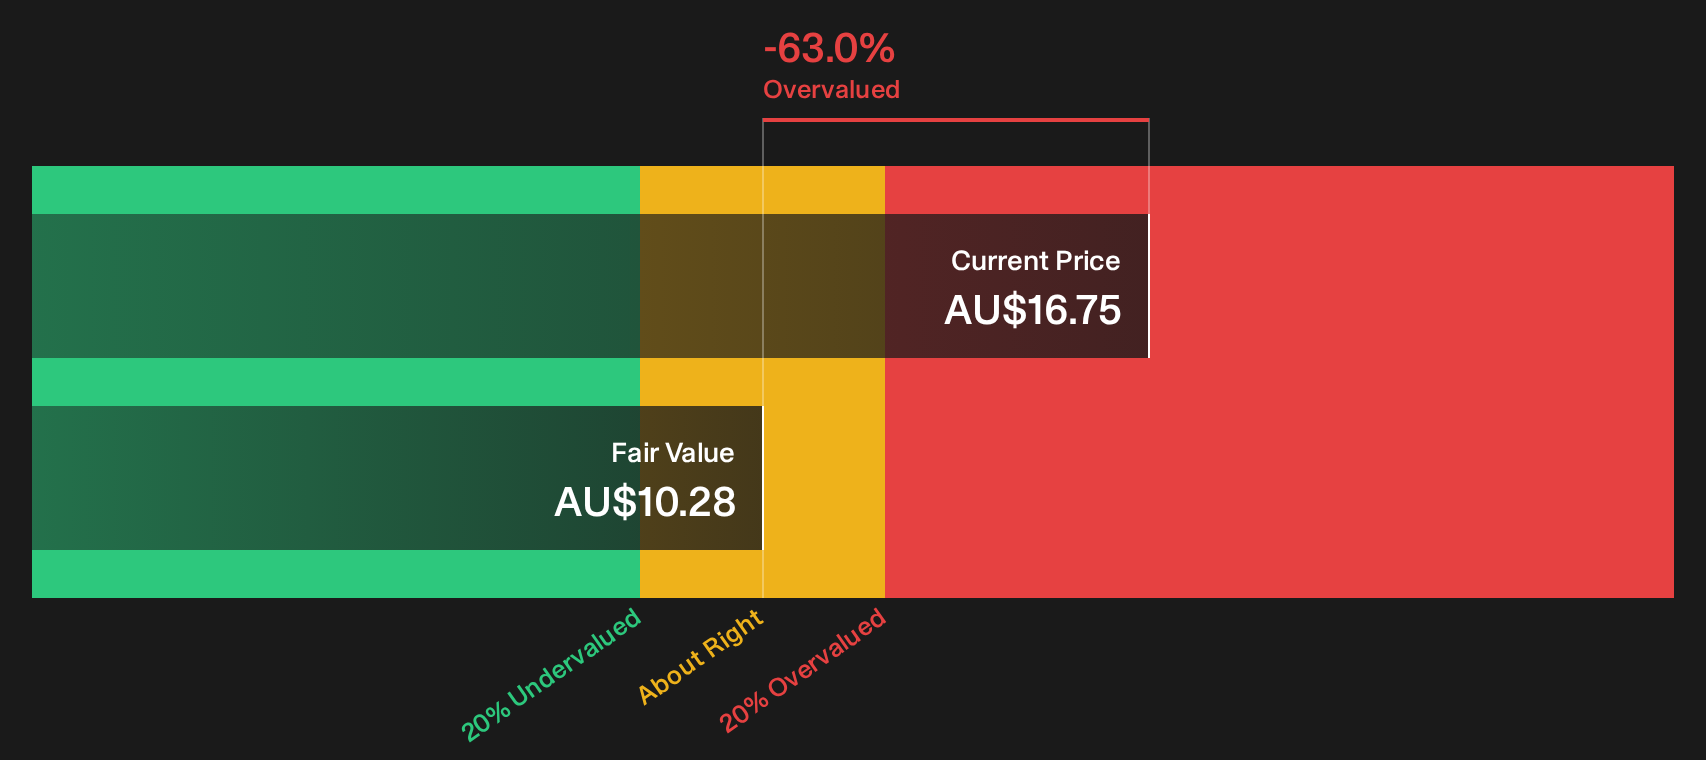
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fortescue for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If Fortescue’s mix of legal overhangs and future opportunities feels finely balanced, treat that as your cue to move fast. Stress test the data yourself and then weigh the 1 key reward and 2 important warning signs.
Looking For More Fortescue-Sized Ideas?
Fortescue’s situation can sharpen your process, so use that momentum to pressure test fresh ideas with clearer balance sheets, income potential and valuation support.
- Target resilience by zeroing in on companies with robust finances and durable operations through our 7 resilient stocks with low risk scores.
- Hunt for mispriced quality and see which businesses combine strong fundamentals with appealing entry points using the 5 high quality undervalued stocks.
- Build a watchlist of potential outperformers by scanning a 15 high quality undiscovered gems that the broader market may not be focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com