
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Nucor (NUE) Could Change Following Earnings Guidance
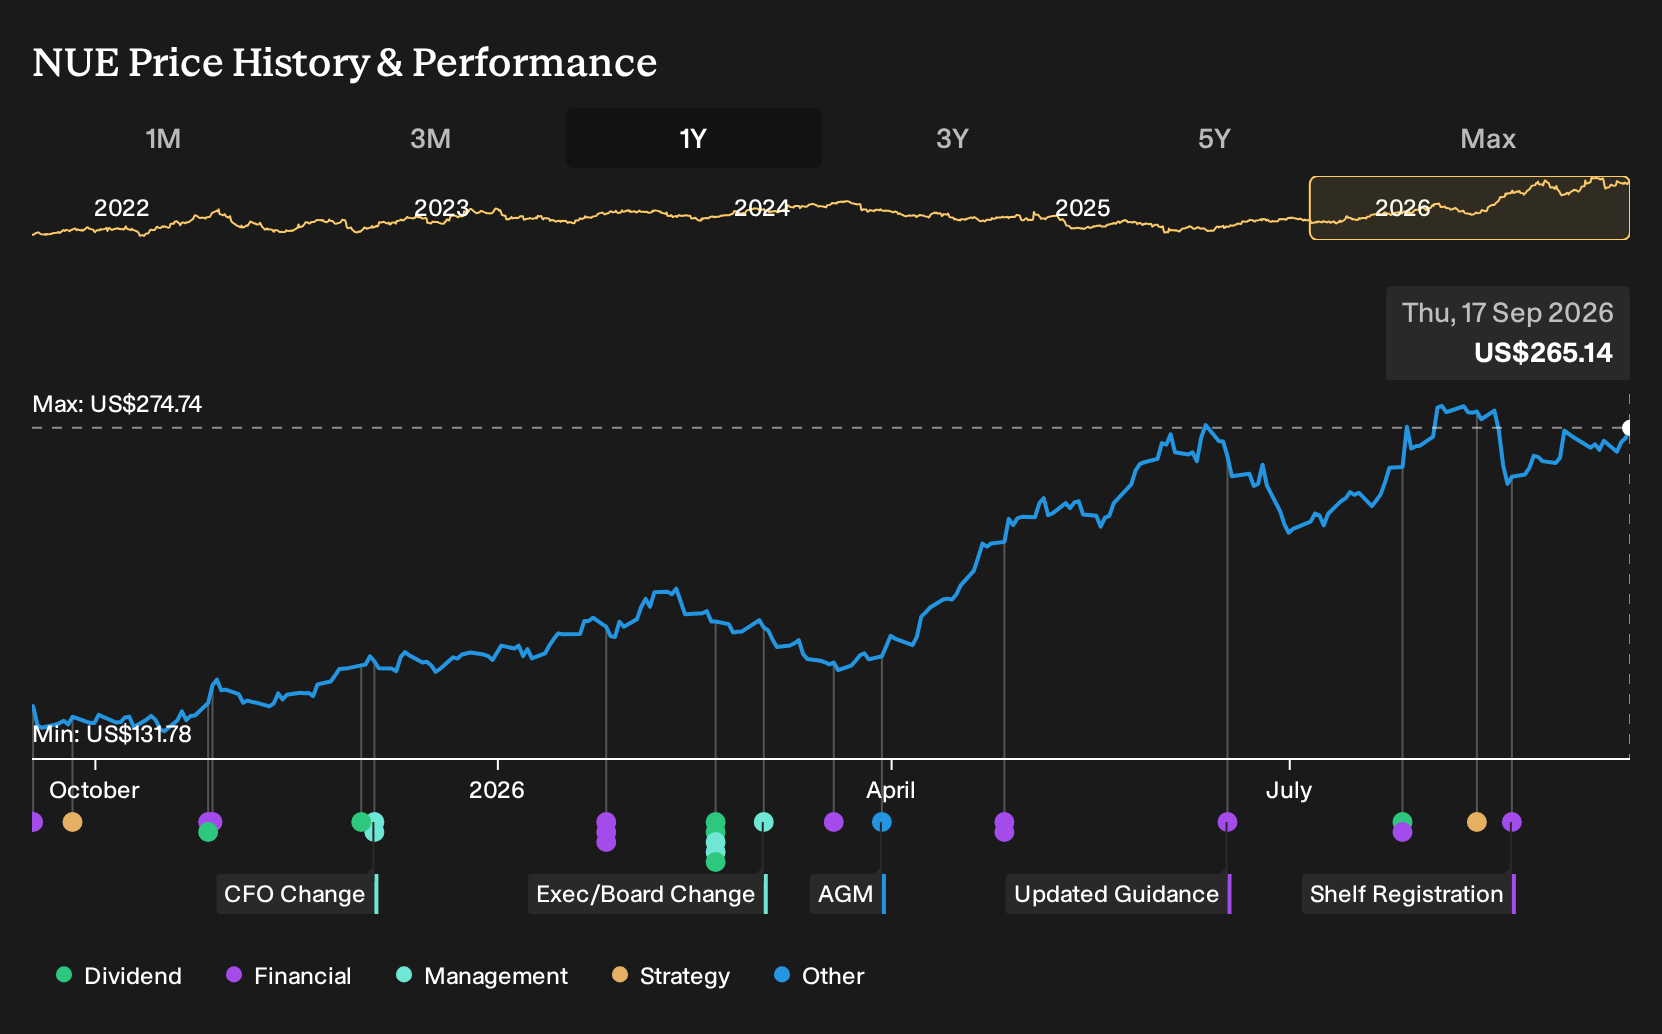
- Nucor issued new earnings guidance for the third quarter ended October 3, 2026, projecting diluted EPS in a range of $5.55 to $5.65.
- The updated EPS outlook gives investors a closer look at Nucor's near term profitability and how current demand and cost conditions are feeding into results.
- The focus now turns to how Nucor's updated earnings range could influence the current investment narrative around its capital reinvestment plans.
Scan beyond Nucor and compare how other steel and capital intensive businesses are priced on cash flow strength using our curated list of 29 high quality undervalued stocks.
Nucor Investment Narrative Recap
To own Nucor, you need to be comfortable with a cyclical steel producer that is pouring a lot of money back into mills, products, and raw materials. The big belief is that this reinvestment and project pipeline will keep utilization and cash generation healthy even when demand swings. The fresh guidance for third quarter EPS of $5.55 to $5.65 gives you a tighter read on near term profitability but does not fundamentally change that longer thesis.
In the near term, the key swing factor remains how well Nucor fills new and existing capacity in an environment where domestic steel demand can stall. The biggest operational risk right now is project execution and cost control on new mills, especially large builds like the West Virginia sheet project, combined with raw material and energy price volatility that can quickly squeeze margins if pricing power softens.
The most relevant context for this new earnings outlook is the earlier work suggesting Nucor's intrinsic value, based on a DCF model, sits well above the current share price. That view leans heavily on future cash flows from the current asset base and the large reinvestment program, not just one quarter's EPS range. The latest guidance mainly helps you judge whether operations are tracking close to those cash flow expectations.
For catalysts, that DCF framework ties directly into the same factors that drive the quarter, such as utilization at steel mills, progress on new micro mills and coating lines, and any change in trade policy that affects import competition. Weakness in these areas, or delays bringing new projects to steady state, would pressure the assumptions behind that valuation work and increase the importance of how Nucor sequences its next round of capital spending.
Nucor Consensus Assumptions And Valuation Anchors
Analysts framing Nucor's story are working off revenue growth of 3.9% a year over the next few years, with profit margins rising from 8.0% today to 11.2% by around 2029. That backdrop feeds into an earnings path that moves from US$2.9b today to a projected US$4.5b by 2029, with a wide spread between the most optimistic forecast of US$5.1b and the most cautious at US$3.8b. To make those figures line up with current price targets, the stock would need to trade on a P/E of 18.1x those 2029 earnings, compared with 21.5x today. The analyst framework also assumes the share count drifts lower by about 0.58% a year and discounts future cash flows at roughly 9%.
Nucor's narrative projects US$40.5b revenue and US$4.5b earnings by 2029. This leans on 3.9% yearly revenue growth and an earnings increase of about US$1.6b from US$2.9b today.
On valuation, the consensus price target of US$283.56 sits only 4.1% above the current share price of US$271.81, which implies analysts broadly see the stock as close to their fair value estimates. Even within that apparently tight gap, the range of targets is wide, from US$231.00 at the low end to US$305.00 at the top. Any view you form on Nucor really depends on how comfortable you are with that 2029 revenue figure of US$40.5b and the implied US$4.5b of earnings. If you think mill utilization, project delivery and trade policy play out differently to the consensus path, then your own sense of value may land well outside that current target band.
Uncover why Nucor's fair value indicates a 7% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternate story around Nucor leans on the West Virginia sheet mill as a major upside catalyst. The most optimistic analysts were already penciling in about US$44.8b of revenue and US$5.1b of earnings by 2029 before this EPS guidance. You can treat this new outlook as a fresh test of that more aggressive path and explore where you agree or disagree.
Explore 3 other Nucor fair value estimates, including one that suggests up to 56% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nucor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nucor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nucor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nucor?
If Nucor has sharpened your thinking on capital heavy businesses, you can use that same lens to compare other opportunities where pricing, cash generation, and balance sheets tell very different stories.
- Target reliable payouts and balance those against earnings quality by scanning a curated group of high yield opportunities through 6 dividend fortresses.
- If capital preservation ranks high for you, consider filtering for companies that score well on resilience and financial risk using 30 resilient stocks with low risk scores.
- For investors looking for strong fundamentals before the broader market pays attention, scan a focused set of under-the-radar opportunities with 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com