
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Adeia (ADEA), Is There More To Its Latest Attention Than Meets The Eye?
Adeia (ADEA) moved back into focus after being named Asia Pacific Outstanding Company of the Year for 2025 to 2026, with its licensing vice president also recognized as Outstanding Executive of the Year.
Against that recognition, Adeia’s share price has slipped over the past month, with a 30 day share price return of 11.06% and a 90 day move down 21.66%, even though the year to date share price return sits at 41.75% and the 5 year total shareholder return is very large at more than 4x.
Scan how Adeia compares with other intellectual property and software licensors by reviewing the hand picked 16 high quality undiscovered gems that share strong fundamentals and under the radar stories.
Bulls point to Adeia’s awards, licensing reach and multi year returns. Bears focus on recent share price weakness and modest headline growth. The valuation work now has to show which side the current price aligns with.
Most Popular Narrative: 42% Undervalued
Adeia’s most followed valuation story pegs fair value at $43 against a last close of $24.92, which puts the spotlight on whether the current price really reflects its licensing potential and patent portfolio.
Adeia is capitalizing on the ongoing proliferation of connected devices and the exponential surge in data generation, which is increasing the need for advanced digital content delivery, storage, and high-performance semiconductor technologies. These trends underpin expanding royalty streams, support sustainable top-line revenue growth, and reinforce long-term earnings stability.
See why 8 investors see Adeia as 42% undervalued.
Result: Fair Value of $43 (UNDERVALUED)
Still, Adeia’s reliance on a concentrated group of licensees and rising litigation costs could quickly challenge the 42% undervalued story if deals or legal outcomes disappoint.
Find out about the key risks to this Adeia narrative.
Another View: Adeia Through The SWS DCF Lens
The analyst narrative refers to a fair value of $43, while the SWS DCF model points to a future cash flow value of $24.20 compared with Adeia’s recent $24.92 price, which appears slightly overvalued. This raises a straightforward question: are you more persuaded by cash flows or by earnings multiples?
Look into how the SWS DCF model arrives at its fair value.
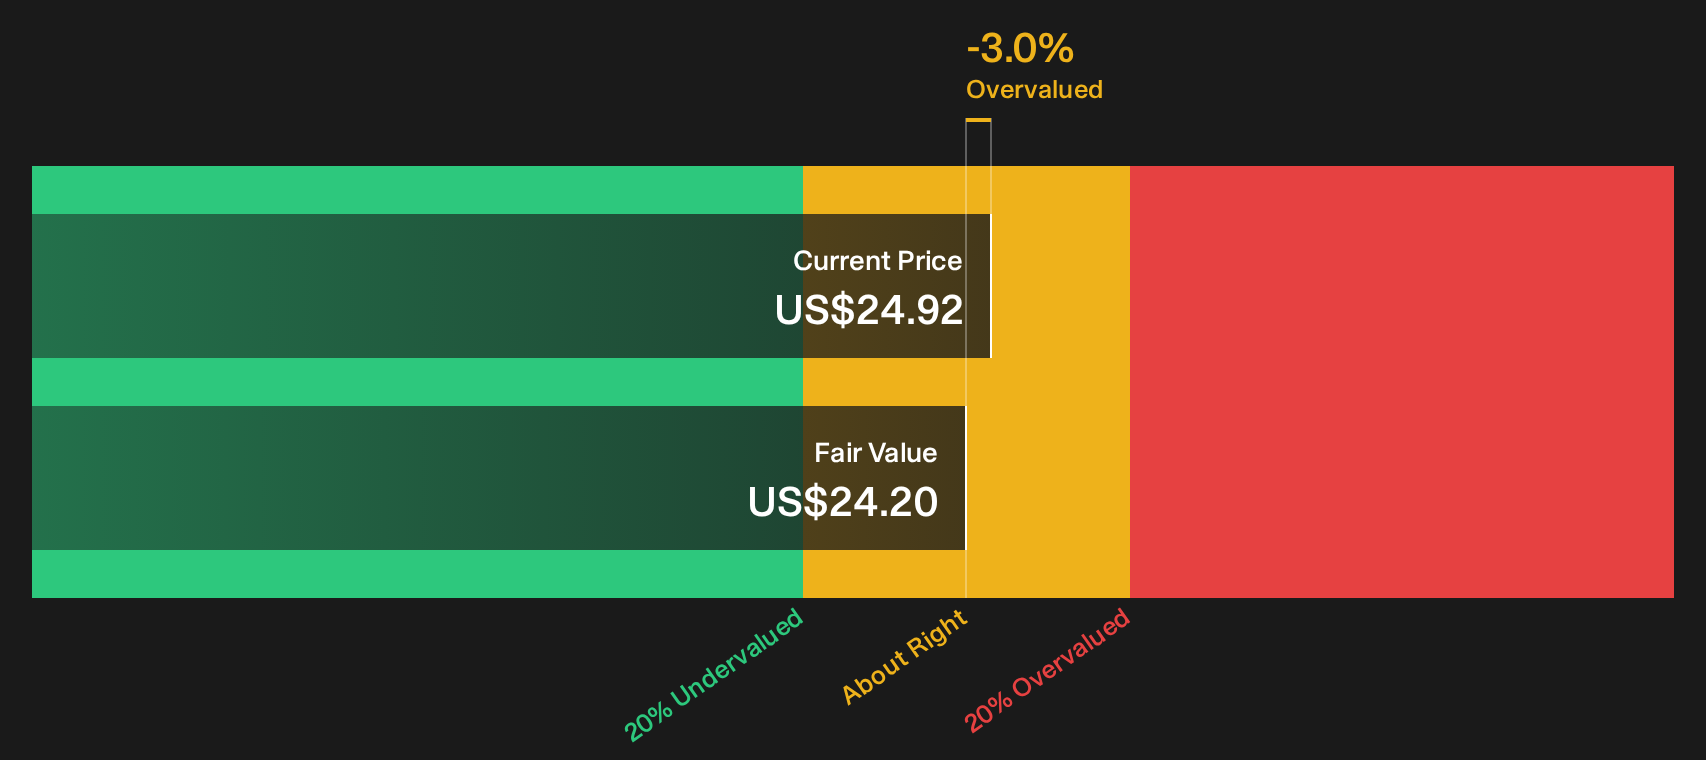
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Adeia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings on Adeia after all that. Act quickly, stress test the numbers yourself, then weigh up the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Adeia?
If you stop with Adeia, you only see one angle. Consider broadening your watchlist with opportunities that match your style.
- Target potential mispricings by scanning a focused set of high quality companies using the 29 high quality undervalued stocks.
- Strengthen your downside protection by filtering for businesses with resilient finances through the 30 resilient stocks with low risk scores.
- Hunt for resilient balance sheets and healthy fundamentals using the curated list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com