
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Redeia Corporación (BME:RED) 18% Above Fair Value Or About Right At €15.09?
Redeia Corporación (BME:RED) has been drawing attention after its latest share price of €15.09, prompting investors to reassess a business that manages Spain’s high voltage grid and related telecom infrastructure.
In the short term, Redeia Corporación’s share price has been broadly flat. A small 1-day gain of 0.33% and a 7-day share price return of 1.28% are offset by a slight 30-day decline of 0.66%. Over longer periods, a 1-year total shareholder return decline of 4.09% contrasts with a 3-year total shareholder return of 13.67% and a 5-year total shareholder return of 7.03%, which together indicate modest long term compounding alongside recent weakness.
Scan beyond Redeia Corporación and size up other grid and infrastructure players with the curated 37 power grid technology and infrastructure stocks shaping the future of electricity transmission and related services.
Bulls point to Redeia Corporación’s regulated grid, steady revenue base and telecom add ons, while bears focus on the recent share price drift and modest value score. Which side do the current valuation signals back up?
Price-to-Earnings of 16.9x: Is it justified?
On earnings, Redeia Corporación trades on a P/E of 16.9x, which places the current €15.09 share price between signals of potential value and areas of caution when set against peers and internal cash flow metrics.
The P/E ratio compares the share price to earnings per share. For a regulated grid operator like Redeia Corporación, it gives a quick read on how much investors are paying for each euro of current profits in a relatively steady, utility style business.
On one side, the stock is described as good value when measured against an estimated fair P/E of 18.4x and against a peer average P/E of 27.6x. That suggests the market is not pricing Redeia Corporación as highly as some comparable utilities and that the P/E could move closer to the fair ratio level if sentiment or earnings support it.
On the other side, the same P/E of 16.9x is described as expensive compared to the broader European Electric Utilities industry average of 15.5x. In other words, investors are currently paying a richer multiple than the sector as a whole even though the SWS fair ratio work points to 18.4x as a level the valuation could trend towards over time.
Explore the SWS fair ratio for Redeia Corporación.
Result: Price-to-Earnings of 16.9x (ABOUT RIGHT)
Still, Redeia Corporación faces risks if regulators squeeze allowed returns or if telecom and international projects require heavier spending than current earnings can comfortably support.
Find out about the key risks to this Redeia Corporación narrative.
Another view on Redeia Corporación’s value
The P/E picture suggests Redeia Corporación is roughly fairly valued, but the SWS DCF model paints a different story. On that framework, the share price of €15.09 sits above an estimated future cash flow value of €12.79, which implies limited cushion if expectations slip.
For investors, that gap raises a practical question. Is the current price rewarding a steady regulated grid franchise, or leaning too heavily on cash flows that may prove harder to deliver in full?
Look into how the SWS DCF model arrives at its fair value.
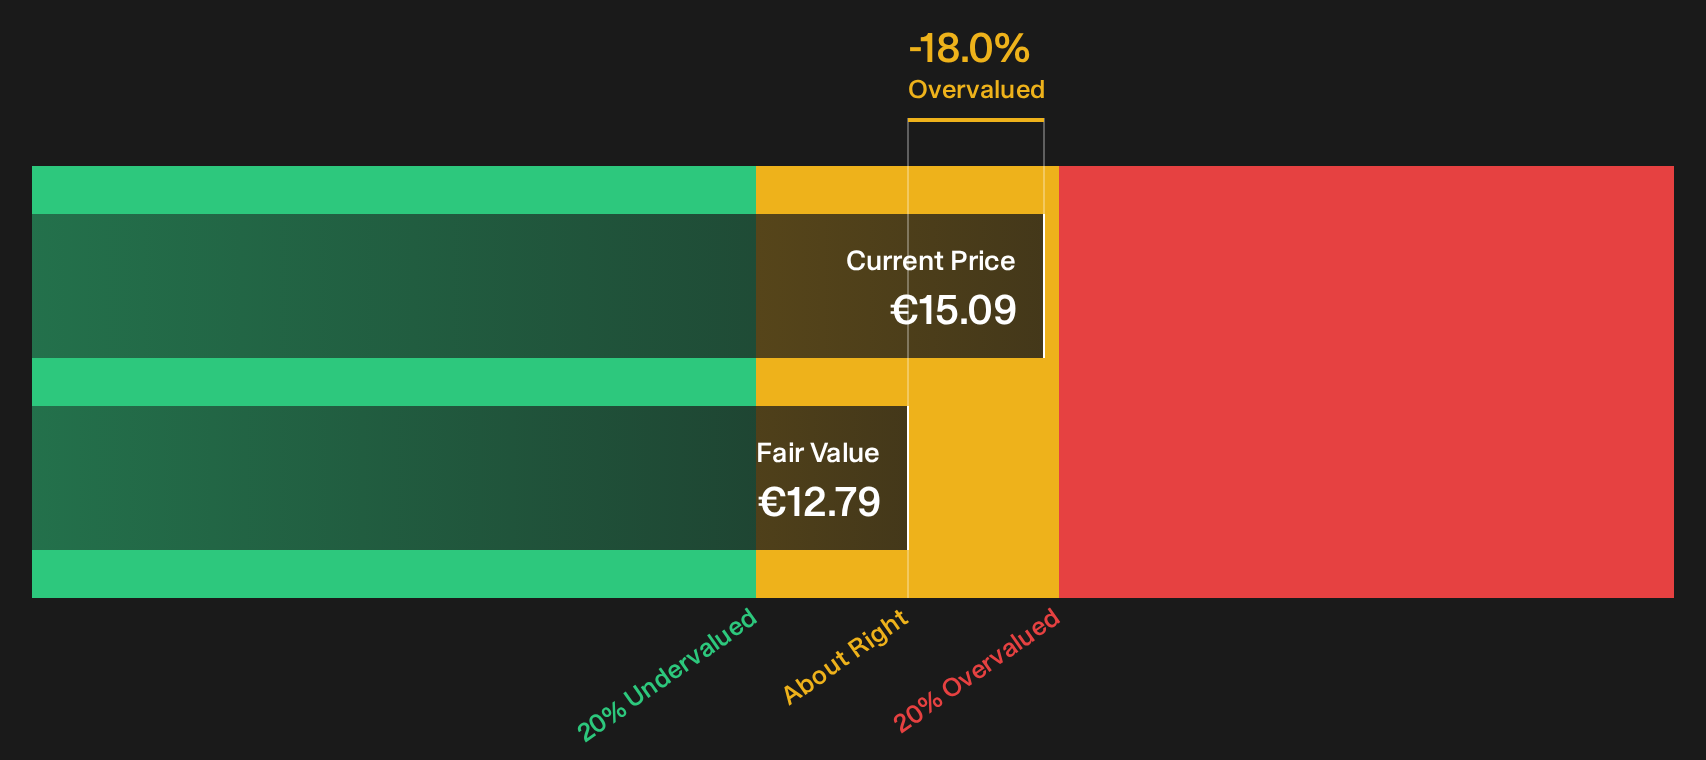
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Redeia Corporación for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Redeia Corporación’s price and cash flow story can pull you in both directions, so move quickly, review the core numbers, and weigh the trade off between caution and optimism using the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Redeia Corporación?
If Redeia Corporación has you thinking more broadly about where to put fresh capital, use the screener to quickly surface other focused opportunities that fit your style.
- Target resilience first by checking companies on the 227 resilient stocks with low risk scores that aim to balance upside with tighter risk controls.
- Hunt for potential mispricing and review the 173 high quality undervalued stocks that highlight businesses trading below their assessed quality.
- Prioritise financial strength by scanning the list of solid balance sheet and fundamentals (196 results) so you are not leaving sturdier opportunities on the table.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com