
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 U.S. Insurance Stocks Built to Benefit From Higher Bond Yields
Interest rates have climbed again, the Fed has lifted the benchmark range to 3.75% to 4%, yet longer Treasury yields have eased a touch and the bond market now offers income levels many investors have not seen in years. That mix turns higher-for-longer yields from a headline into a potential fork in the road for your portfolio. This article explains how that backdrop relates to three U.S. insurers and annuity providers exposed to this news, and why their stories may matter for your next move.
The three insurers highlighted below are only a sample, since the full screen surfaced another 7 U.S. life and annuity companies with equally compelling interest rate stories that are not covered here. To see the broader field and identify which profiles fit your risk and income goals, analyze the U.S. Insurers & Annuity Providers Benefiting from Higher-for-Longer Yields screener.
CNO Financial Group (CNO)
Overview: CNO Financial Group offers health, life, and annuity products to U.S. middle-income pre-retirees and retirees, heavily linking outcomes to investment spreads.
Operations: CNO generates about US$4.6b in revenue, mainly from U.S. health insurance of US$2.0b, life insurance of US$1.1b, and annuities of US$683m.
Market Cap: US$5.1b
CNO Financial Group sits squarely in the higher-for-longer yield story, since its retirement-focused policies give it substantial investment float that is constantly being reinvested as bonds mature.
"Many in this set invest policyholder and annuity float into bond portfolios, so a higher-for-longer interest-rate backdrop could potentially improve reinvestment yields and margins for some, but individual exposure and outcomes will vary."
For CNO, the real test is how one unseen pressure on profitability develops as management leans into this rate backdrop.
That pressure point is exactly where the story gets interesting, and the full narrative for CNO Financial Group unpacks how higher-for-longer yields could reshape CNO Financial Group’s profit engine and risk profile.

F&G Annuities & Life (FG)
Overview: F&G Annuities & Life focuses on U.S. annuity and life products that give investors direct exposure to how higher-for-longer yields feed into reinvestment returns on policyholder float.
Operations: F&G Annuities & Life reports US$6.1b of revenue from life insurance, with the full amount attributed to Bermuda operations.
Market Cap: US$3.0b
F&G Annuities & Life offers a focused way to track how higher-for-longer policy rates can filter into bond portfolio yields and policyholder guarantees through its annuity-heavy book.
"F&G has launched a Registered Index-Linked Annuity (RILA) product, gaining entry into the fast-growing RILA market. The company is onboarding new distribution partners and expects medium-term RILA sales to reach billions, which could significantly boost future revenue."
The key factor to watch is how one underappreciated funding and investment mix choice shapes long-run spreads if rate momentum slows.
If that funding mix intrigues you, go straight to the full narrative for F&G Annuities & Life for details on how F&G Annuities & Life could turn reinvestment spreads into accelerating earnings power.

MetLife (MET)
Overview: MetLife is a global insurer that uses life, annuity, benefits, and asset management franchises to turn premium float into long-term investment income.
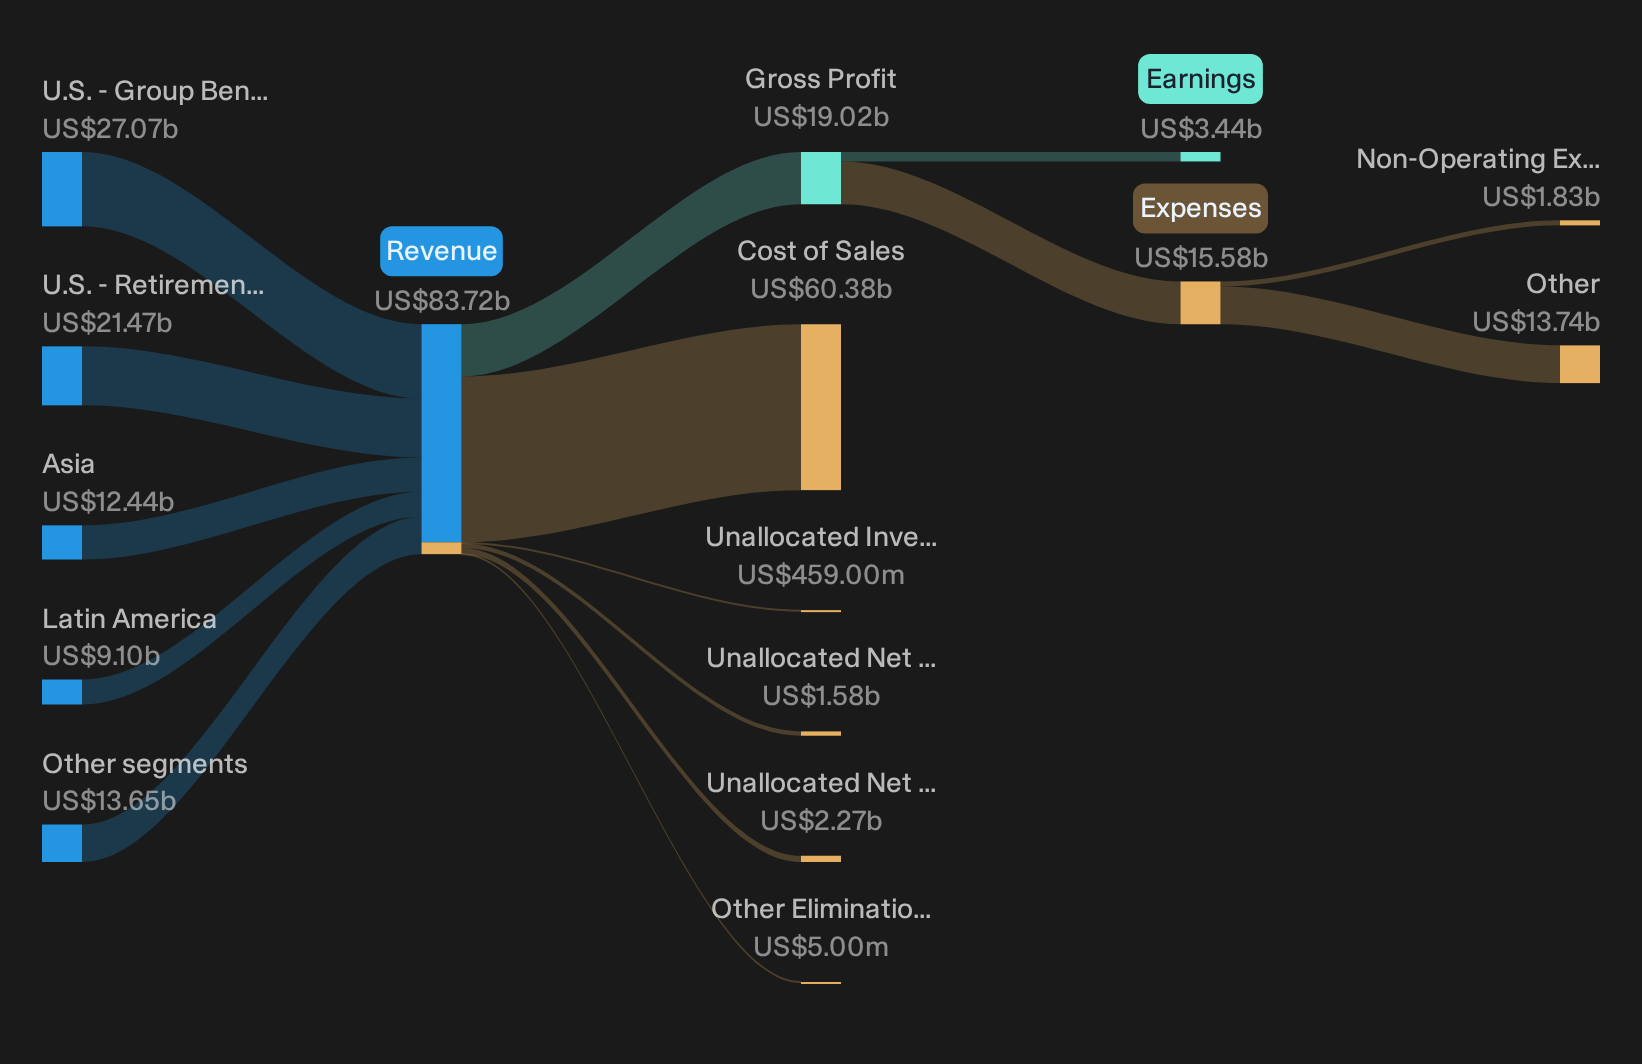
Operations: MetLife generates most of its revenue from U.S. Group Benefits of US$27.1b and U.S. Retirement and Income Solutions of US$21.5b, alongside sizeable Asia and Latin America contributions.
Market Cap: US$61.8b
MetLife fits this higher-for-longer yield theme because its large life and annuity franchises constantly recycle policyholder float into bond portfolios that reset with today’s richer income levels.
"Many in this set invest policyholder and annuity float into bond portfolios, so a higher-for-longer interest-rate backdrop could potentially improve reinvestment yields and margins for some, but individual exposure and outcomes will vary."
For MetLife, what happens when one funding and reinvestment choice shifts will do a lot to decide how much of that spread potential actually reaches future margins.
That reinvestment choice is the hinge, and the full narrative for MetLife shows how MetLife’s spread engine, capital flexibility, and risk pockets could be quietly accelerating in this rate regime.
Seeking Fresh Alternatives Before The Crowd
Market momentum shifts fast, and the cleanest breakout setups rarely stay under the radar for long. Scan fresh ideas before the window drops out of reach, and consider acting while the opportunity is still available.
- Spot resilient dividend income plays before yields get caught by the crowd by running the 6 dividend fortresses while the pricing and coverage mix still looks fresh.
- Look for under-the-radar growth stories with strong balance sheets using the 16 high quality undiscovered gems while these potential compounders remain less widely followed.
- Focus on financially sound operators through the list of solid balance sheet and fundamentals (23 results) so you can prioritize fundamentals, which can be important for managing risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com