
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Supply Deals Change Almonty Industries Stock Narrative
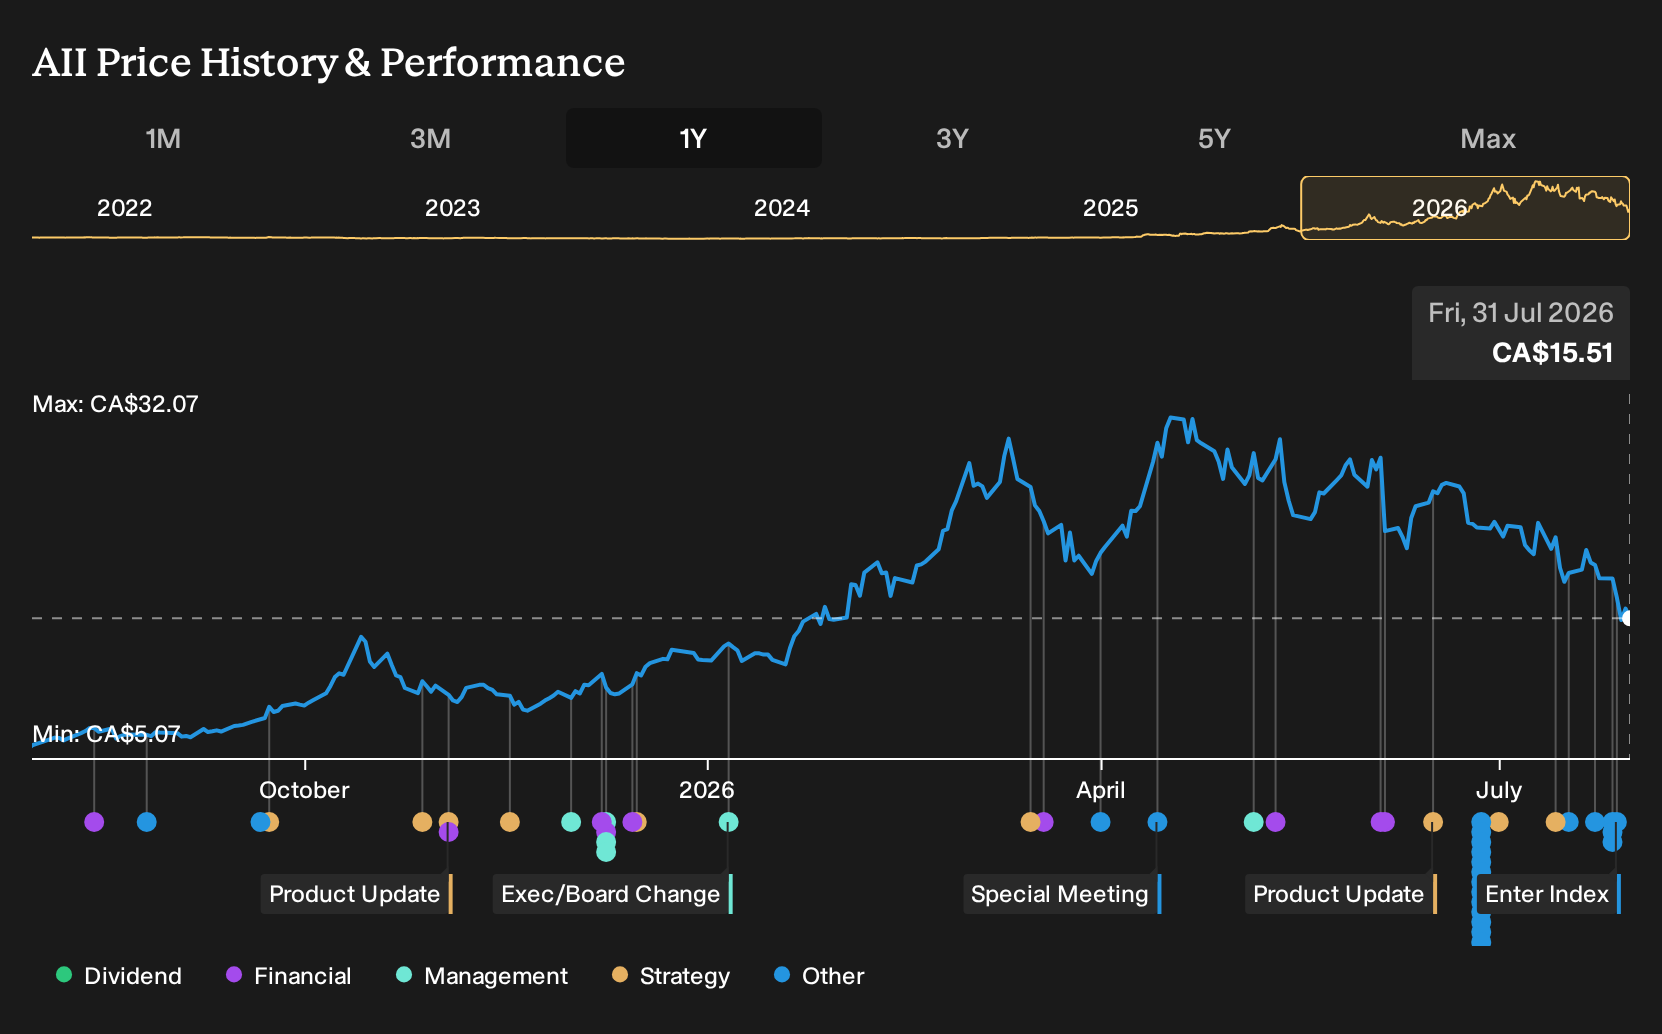
- Almonty Industries entered a multi-year take-or-pay tungsten concentrate supply agreement with Wolfram Bergbau und Hütten AG for tailings retreatment at the Los Santos Mine in Spain and also formed a joint venture with the Government of Rwanda, which contributed the Shyorongi concession and a mobile processing license for a 25% stake in Almonty Rwanda.
- These moves expand Almonty Industries' tungsten feed sources across Europe and Africa using tailings retreatment and small-scale Rwandan supply, while aligning with upcoming United States rules that increase the importance of documented non-Chinese tungsten origin for defense procurement.
- We will now look at how Almonty Industries' investment narrative could be affected by these new tungsten supply and recycling agreements.
What Is Almonty Industries' Investment Narrative?
For Almonty Industries, the big-picture belief is simple. You need to think traceable, non-Chinese tungsten supply can stay valuable as Western defense and technology buyers tighten origin rules. The Los Santos take-or-pay contract and the Rwanda joint venture speak directly to that. Together they point to a plan that leans on recycling, tailings retreatment and smaller sources rather than betting everything on one large, capital heavy mine build.
Short term, the key swing factors are execution and funding. Restarting Los Santos and building out Almonty Rwanda both require capital, while ALM’s liabilities are entirely from higher risk borrowing and the P/E of 53.1x is already rich versus peers. Tungsten prices have moved sharply and the stock has been volatile, so these contracts may help support the story, but they do not remove the core operational and balance sheet pressures.
Even so, there is a more awkward angle once you look at how those high non cash earnings interact with...
There's only one way to know the right time to buy, sell or hold Almonty Industries. Head to Simply Wall St's company report for the latest analysis of Almonty Industries's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community supplies two fair value estimates for Almonty Industries, ranging from about 25.81 to 41.71, which is a wide band for such a small sample. Those views were all formed before the Rwanda joint venture and the Los Santos take or pay deal. Use that gap as a prompt to compare several viewpoints yourself.
Explore another Almonty Industries fair value estimate, including one that suggests it could be worth just $25.81!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Almonty Industries research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Almonty Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Almonty Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Almonty Industries?
If the Almonty Industries story has you thinking about how to position your portfolio around quality, risk and valuation, it can help to line it up against a wider bench of businesses using the Simply Wall St Screener.
- For investors who want stability first and volatility second, check out a 30 resilient stocks with low risk scores that may better match a cautious approach.
- If you care most about underlying financial strength, start with a list of solid balance sheet and fundamentals (23 results) to see which businesses pair resilient finances with cleaner balance sheets.
- When you want to go off the beaten path, scan a 16 high quality undiscovered gems that might offer strong fundamentals without already being crowded trades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com