
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Endeavour Mining Stock Faces Higher Royalties Risk In West Africa
- Endeavour Mining, a London headquartered gold producer with multiple mines across West Africa, now faces rising royalty and tax demands from governments including Côte d’Ivoire and Senegal. This is increasing uncertainty around its long term cost base.
- The push for higher state take directly targets one of Endeavour Mining’s less visible constraints, namely the durability of its margin structure as government charges evolve.
- We will now see how Endeavour Mining's investment narrative is affected by the prospect of structurally higher West African royalty and tax burdens.
Compare Endeavour Mining’s political risk exposure with a curated 36 elite gold producer stocks that operate under different regulatory regimes and see how concentration in West Africa fits into your portfolio.
Endeavour Mining Investment Narrative Recap
For an investor to stay with Endeavour Mining, the core belief is that a concentrated West African portfolio can keep converting gold output into healthy cash flow, even as older pits mature and new projects like Assafou and Lafigué come on. The recent royalty and tax push directly challenges that view by putting more pressure on all in sustaining costs.
The key near term swing factor is how efficiently Endeavour Mining can offset higher government take through mine optimisation and project sequencing at sites such as Sabodala Massawa and Ity. The biggest current risk is that rising fiscal burdens arrive just as ore grades trend lower, which would squeeze margins more than investors are assuming.
There have been no fresh corporate announcements disclosed alongside this news, so the most relevant reference point is still the existing project and optimisation pipeline that analysts focus on, especially Sabodala Massawa and Assafou. Those projects are central to expectations for higher output and a stronger margin mix over the next few years.
This new tax and royalty backdrop makes execution on those assets even more important. If Endeavour Mining keeps unit costs low at its Tier 1 projects and maintains high quality earnings and strong return on equity, the group has more room to absorb fiscal creep. If delays or cost slippage occur instead, the regulatory burden becomes much harder for the business to absorb.
Endeavour Mining is framed on consensus estimates to reach about US$5.9b in revenue and US$1.6b in earnings by 2029. That path assumes revenue expands at roughly 7.4% a year and profits rise by about US$760.1m from current earnings of US$839.9m.
Uncover why Endeavour Mining's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
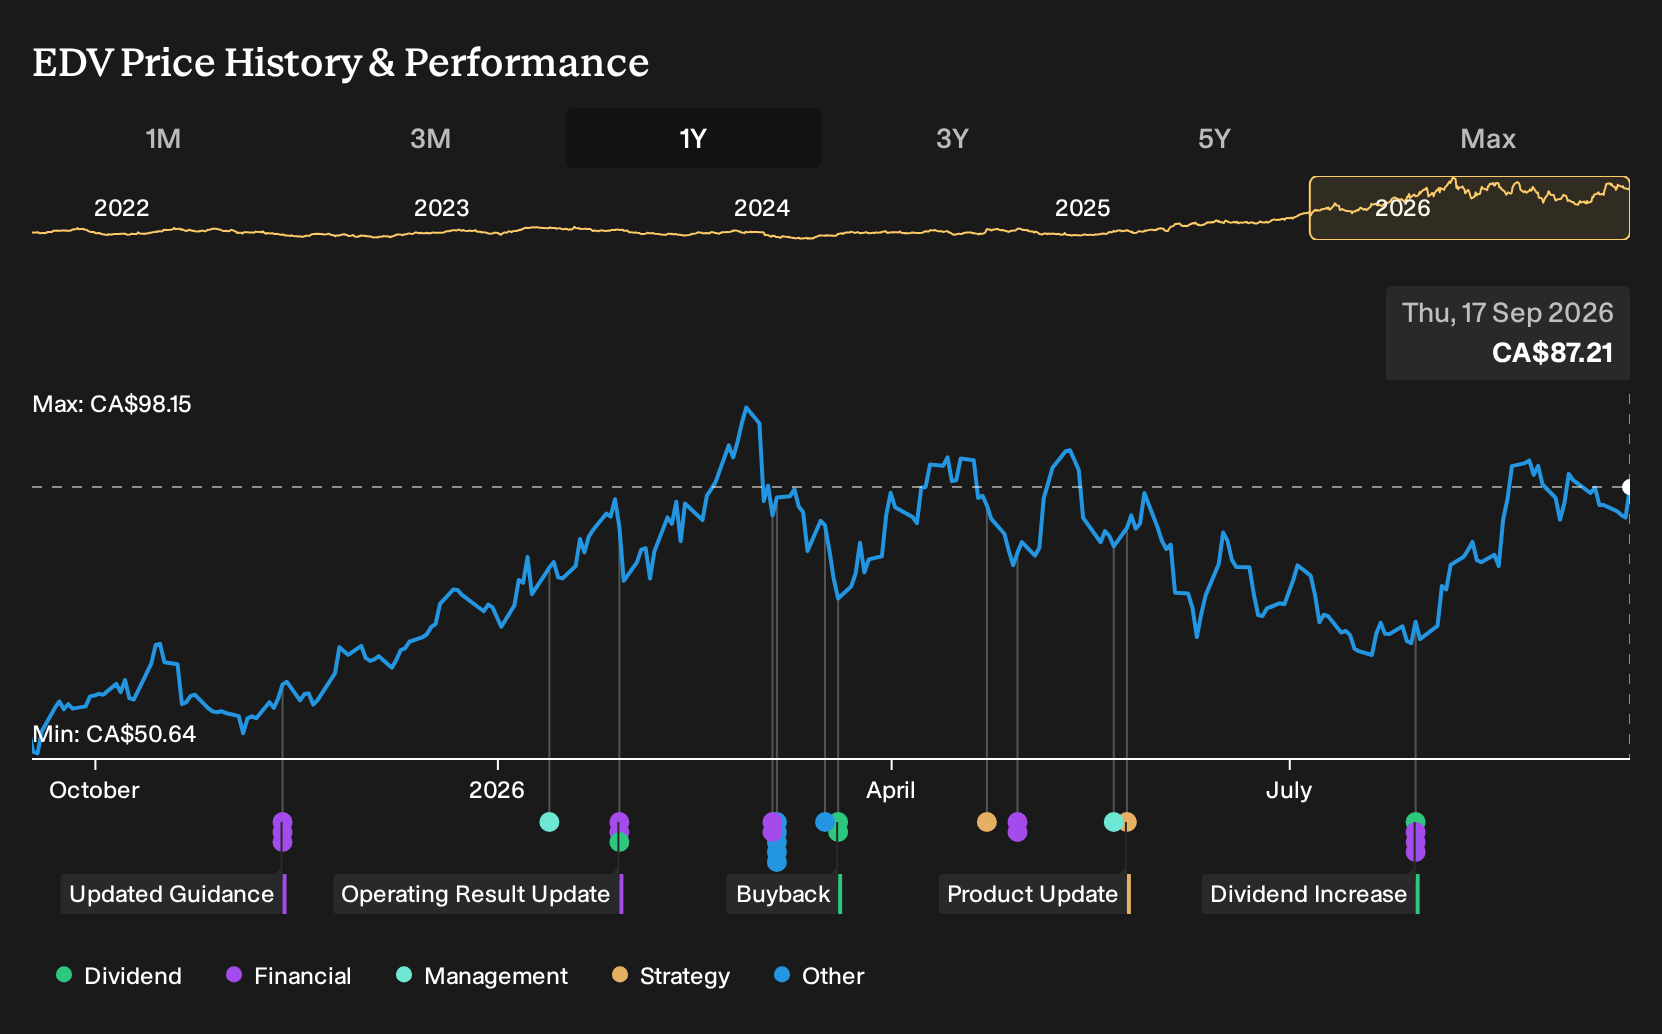
Exploring Other Perspectives
Some of the most optimistic analysts focus on exploration upside rather than tax risk. They were pencilling in revenue of about US$7.8b and earnings of roughly US$2.6b by 2029, compared with the broader consensus of US$5.9b and US$1.6b. Those forecasts came before this royalty debate, so you may see views shift from here.
Explore 3 other Endeavour Mining fair value estimates, including one that suggests a potential upside of as much as 105% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and instincts.
- A great starting point for your Endeavour Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Endeavour Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Endeavour Mining's overall financial health at a glance.
Looking for more Endeavour Mining style investment ideas?
Once you have a view on Endeavour Mining, it can help to widen the lens and compare it with other opportunities that fit different roles in your portfolio.
- If you want to focus on companies that combine valuation appeal with stronger fundamentals, consider starting with a 3 high quality undervalued stocks.
- For readers who care more about balance sheet strength and financial resilience, filter the market using a list of solid balance sheet and fundamentals (7 results) to see which businesses meet your standards.
- If you are hunting for under followed opportunities with solid financial profiles, cast a wider net with a 9 high quality undiscovered gems that might complement or contrast with your view on Endeavour Mining.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com