
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IDC: In the second quarter, China's industrial PC shipments increased 16.8% year-on-year, and the growth rate hit a new high in the past five quarters
The Zhitong Finance App learned that the latest data from the International Data Corporation (IDC) shows that in the second quarter of 2026, shipments in the Chinese industrial PC market increased 16.8% year-on-year, and the growth rate hit a new high in the past five quarters. However, behind the impressive data, market participants are facing more complex cyclical challenges: this round of growth also includes real increases brought about by AI transformation, and upfront demand generated by short-term fluctuations in supply and demand, making it impossible to determine future trends through simple linear extrapolation. Manufacturers need to penetrate data and adjust their business strategies, and shift from pursuing large-scale growth to improving order quality and product competitiveness.
Q2 market recovery: double growth with a high growth rate of 16.8%
In 2026, China's industrial PC market shipped 1.189 million units in Q2, up 16.8% year on year; the first half of the year accumulated 2.254 million units, up 11.9% year on year, showing a trend of high year-on-year growth.
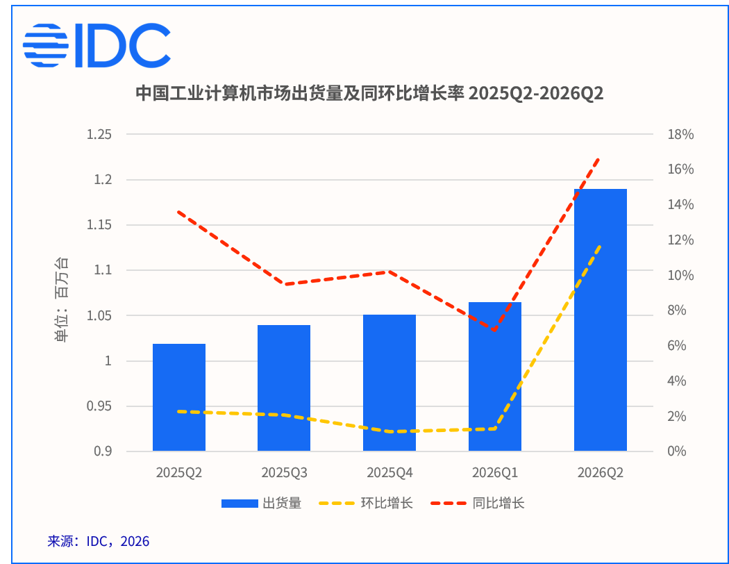
IDC believes that this round of growth is driven by two completely different drivers, which also determines the lack of structural stability in market growth:
The first is the real increase brought about by AI edge computing power, which is sustainable in the long term. As the industry accelerates into a new stage centered on smart devices, the edge side computing power gap continues to expand; with their high stability advantages, industrial PCs can support multi-step, long-term localized AI tasks, and provide reliable end-side computing power for core scenarios such as manufacturing. The long-term trend of intelligent industrial transformation has brought a solid bottom line of growth to the industrial PC market.
Second, there are short-term variables to be wary of, ahead of demand in anticipation of price increases. Faced with rising core component prices and uncertain delivery dates, downstream customers concentrated on locking in advance, causing some orders to essentially be an early withdrawal of 2027 demand. Overall, the high growth rate in the first half of 2026 was driven by a combination of factors. When formulating business plans for 2027, manufacturers should not directly use the current growth rate as a linear extrapolation.
In-depth analysis of the cycle: three factors dominate the differentiation of the industry's growth pace
The high growth in the second quarter was supported by both short-term and long-term dynamics, but looking at the lengthening of the full year or even the three-year cycle, the pace of industry growth did not continue linearly. The triple changes in the supply and demand pattern, industrial chain supply, and downstream capital expenditure are reshaping the cyclical logic of the industrial PC market.
IDC predicts that the Chinese industrial PC market is expected to ship 4.489 million units in 2026, with a market size of about 12.0 billion yuan; the compound growth rate from 2026 to 2030 is 13.1%, and it will reach 7.355 million units in 2030. Among them, about 2.235,000 units are expected to be shipped in the second half of 2026. Compared with the first half of the year, a slight decrease of 0.8% month-on-month, growth momentum has shown signs of marginal leveling off. The tight supply of CPUs, PCBs, and Power ICs is the core reason for the slowdown in growth. Delivery times for leading manufacturers have been extended to half a year; although the release of backlog orders will be delayed until 2027, order momentum has weakened marginally, and the order shipment ratio of leading manufacturers in China has dropped to 1.21, the lowest level in major regions in the world.
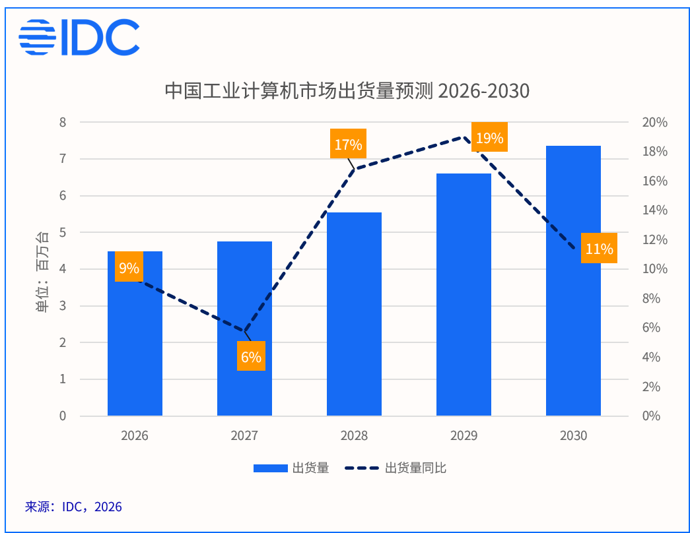
Specifically, three factors have combined to influence the growth rate of the industrial computer market:
High growth in the first half of the year was mixed with significant upfront demand, which overdrew subsequent growth momentum. The increase in the price of memory chips and the lengthening of the delivery cycle prompted customers to prepare goods in advance, essentially overdrawing market demand for subsequent years. In 2027, the market will need to absorb this portion of orders released early. The underlying reason behind this is a structural imbalance between supply and demand in the global storage industry under the AI supercycle: the three original manufacturers continue to shift wafer production capacity to high-margin HBM, while HBM consumes about three times that of general-purpose DRAM, continuously squeezing production capacity in mature processes, and the current price increase cycle is expected to continue until the end of 2027.
The supply bottleneck lasted longer than expected, and orders were delayed backwards on a large scale. Core materials such as CPUs, PCBs, and power ICs are in short supply. Production capacity of leading manufacturers is saturated, and order delivery times are as long as half a year. The 2026-2027 global mature process is at a bottleneck stage where the old production capacity is full and the new production line has not yet been put into operation. The additional production capacity will not form effective output until 2028, and a large number of orders have been delayed as a result.
The pace of capital expenditure in the manufacturing industry is changing, and the medium- to long-term growth momentum is shifting. The automation market in the first half of 2026 showed structural differentiation with OEMs leading the way and the process industry under pressure. After equipment renewal funds were released during the year, the growth momentum of the project-based market declined as there was a lack of additional capital expenditure of the same scale from 2027 to 2028.
IDC Action Proposals: Three Dimensions to Restructure Business Strategies
Taken together, the combination of the three factors of forward demand overdraft, extended supply bottlenecks, and capital expenditure shifts means that the high growth of the industry is difficult to simply and linearly continue. Manufacturers need to break out of traditional annual planning and make targeted adjustments in the three dimensions of business planning, product value, and business structure to cope with cycle fluctuations.
Restructure the annual business plan and abandon the logic of linear deduction: in response to the risk of cycle mismatch caused by demand forecasting, the first action is to break the inertia of traditional planning. Abandon the traditional model of using annual shipments and backlog orders to linearly extrapolate next year's performance, the orders in hand for the first half of 2026 were structurally split into three types: actual AI immediate demand, routine equipment updates, and preparation before price increases. Independent calculation assumptions and business models were constructed for each type of order. Avoid using this year's high shipments and high backlog orders directly as the basis for 2027 performance, and fully reserve buffer space for the decline in the industry cycle. Predicting the year-on-year growth rate of the industry in the first half of 2027 is likely to be under pressure. Emergency plans for production scheduling, material procurement, and inventory control need to be formulated in advance to achieve active risk control and avoid delays in passive production cuts and inventory adjustments after orders fall.
Relying on edge AI scenarios to build product premium capabilities: In the face of rising costs in the industrial chain and long-term pressure of supply constraints, enterprises need to break out of the internal volume of hardware construction and create differentiated value. High-end high-performance models need to break out of the competitive logic of simple hardware configuration and focus on edge AI core tracks to create differentiated value. By optimizing the computing power configuration, deepening the adaptation of segmented scenarios, and improving the supporting software stack, we create the core capability for stable AI operation in the long process of device localization, and form differentiated value support recognized by customers, so as to achieve reasonable product premiums.
At the same time, we rely on implementation scenarios and software support service revenue to continuously verify the authenticity and sustainability of product premiums and get rid of homogenous competition at low prices.
Balanced product structure and strengthened cross-cycle hedging capability: In order to hedge against industry cycle fluctuations and the operating risks of a single business, a balanced product structure is the core support for cross-cycle development. Avoid the business risks of investing heavily in a single product line, and build a diversified, anti-cycle product portfolio system. Relying on the scale advantage of standardized general-purpose models, the market share is stabilized through orderly cost transmission, and price increases are not blindly followed; making full use of the cycle mismatch characteristics of project-based customized orders, AI scenario business, and traditional equipment renewal business to achieve business complementarity and hedging.
The optimal management structure is: AI high-performance models contribute to core gross profit growth, standardized models guarantee business scale and stable cash flow, and a flexible pace of new product iteration to hedge against industry growth pressure brought about by the current lengthening equipment renewal cycle and enhance the overall operating stability of the enterprise.