
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Russian Oil Disruption Altering The Investment Case For CVR Energy Stock (CVI)?
- Recent coverage argues that CVR Energy could benefit from past disruptions to Russian oil supply, as tighter global crude availability supports refining economics across its petroleum, renewables, and fertilizer operations.
- An important angle is how CVR Energy’s mix of traditional refining, renewable fuels, and nitrogen fertilizer ties its cash generation directly to changing product spreads and feedstock flows when global oil trade is disrupted.
- This article now explores how CVR Energy's investment narrative might shift as Russian supply risks reshape expectations for refining margins.
Scan how CVR Energy fits into a wider energy trade by lining it up against 37 power grid technology and infrastructure stocks poised to benefit from evolving supply shocks and infrastructure demand.
CVR Energy Investment Narrative Recap
Owning CVR Energy means believing the refining, renewables, and fertilizer mix can turn volatile product spreads into consistent cash generation as operations run more smoothly. The key short term swing factor is refinery uptime. With no further major turnarounds planned until 2027, higher throughput could matter more than any single headline about Russian crude flows.
The biggest near term risk is still operational and regulatory, not the latest oil trade disruption. Recent downtime, higher RIN costs, and the loss of the Blenders Tax Credit have already pressured results, with a Q1 2025 net loss of US$105 million. If RFS costs stay high or downtime reappears, that pressure could persist despite supportive refining margins.
One development that ties most directly into this backdrop is the Coffeyville refinery distillate recovery project. Management expects it to lift distillate yield by about 2% by the end of the third quarter. For an investor watching Russian supply disruptions, that extra diesel and jet output is where CVR Energy lines up most clearly with tighter global balances.
Higher distillate recovery also matters for compliance and cost control. More diesel production can spread fixed costs over additional barrels and may reduce RIN obligations per unit, which is important given recent RIN price pressure. If that project delivers as described and downtime stays contained, it could be one of the sharper operational levers in the near term CVR Energy story.
CVR Energy's current analyst playbook points to revenues of US$7.1b and earnings of US$386.3m by 2029. This path is built on a forecast 5.7% yearly decline in revenue and an earnings step up of about US$317m, from US$69.0m today to the 2029 consensus figure.
Uncover why CVR Energy's fair value indicates a 42% potential downside to its current price, which leaves little room for error.
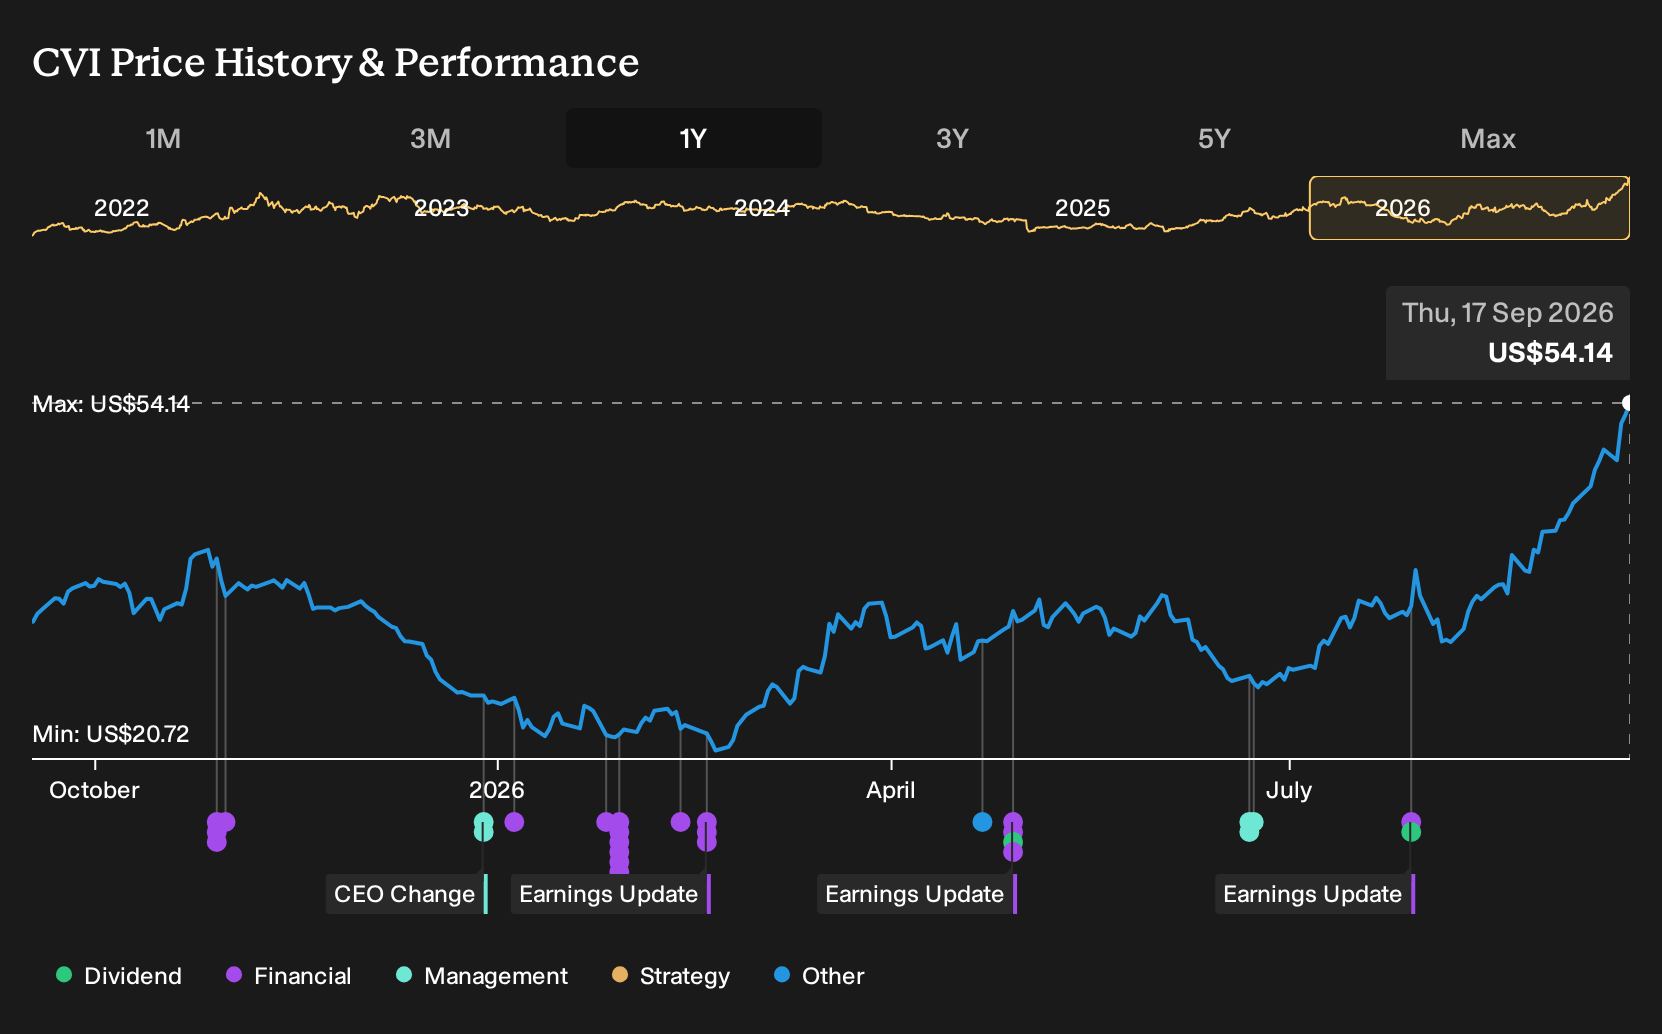
Exploring Other Perspectives
One alternate view focuses less on Russian supply tightness and more on long term fuel demand for CVR Energy. The most cautious analysts were already modeling steeper revenue pressure, with forecasts around US$6.5b of sales and US$294.6m of earnings by 2029. That cohort is materially more pessimistic, and fresh headlines could push expectations even further apart.
Explore 4 other CVR Energy fair value estimates, including one that suggests there could be as much as 46% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CVR Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CVR Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CVR Energy's overall financial health at a glance.
Looking For More CVR Energy Investment Ideas?
If CVR Energy has sharpened your thinking about refinery risk and reward, it can help to set it beside other businesses with very different profiles. Use the Simply Wall St Screener to build a watchlist that reflects how you see risk, balance sheet strength, and income potential.
- For investors who want potential mispricing plus quality, scan a curated 29 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- If capital preservation and steadier profiles matter more to you right now, filter for 30 resilient stocks with low risk scores that score well on resilience and financial risk metrics.
- Income focused investors can round out their research by checking a 6 dividend fortresses that might complement or contrast with CVR Energy's cash return profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com