
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 European Growth Stocks Insiders Own With Up To 97% Earnings Growth
As European markets navigate inflation concerns and rising energy prices, the focus on growth stocks with substantial insider ownership has intensified. In this environment, companies that demonstrate robust earnings potential and strong internal confidence can offer intriguing opportunities for investors seeking to align with insiders who have significant skin in the game.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.6% |
| MilDef Group (OM:MILDEF) | 10.3% | 31.1% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 58.6% |
| KebNi (OM:KEBNI B) | 12% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 60.7% |
| CD Projekt Red (WSE:CDR) | 35.2% | 47.9% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 29.8% |
Here we highlight a subset of our preferred stocks from the screener.
Bilia (OM:BILI A)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Bilia AB (publ) operates as a full-service supplier for car ownership across Sweden, Norway, Luxembourg, and Belgium, with a market cap of SEK14.05 billion.
Operations: The company's revenue segments include Car - Sweden at SEK20.03 billion, Car - Norway at SEK7.99 billion, Service - Sweden at SEK6.95 billion, Service - Norway at SEK2.69 billion, Car - Western Europe at SEK3.74 billion, Service - Western Europe at SEK837 million, Fuel at SEK806 million, and Corporate Functions contributing SEK1.40 billion.
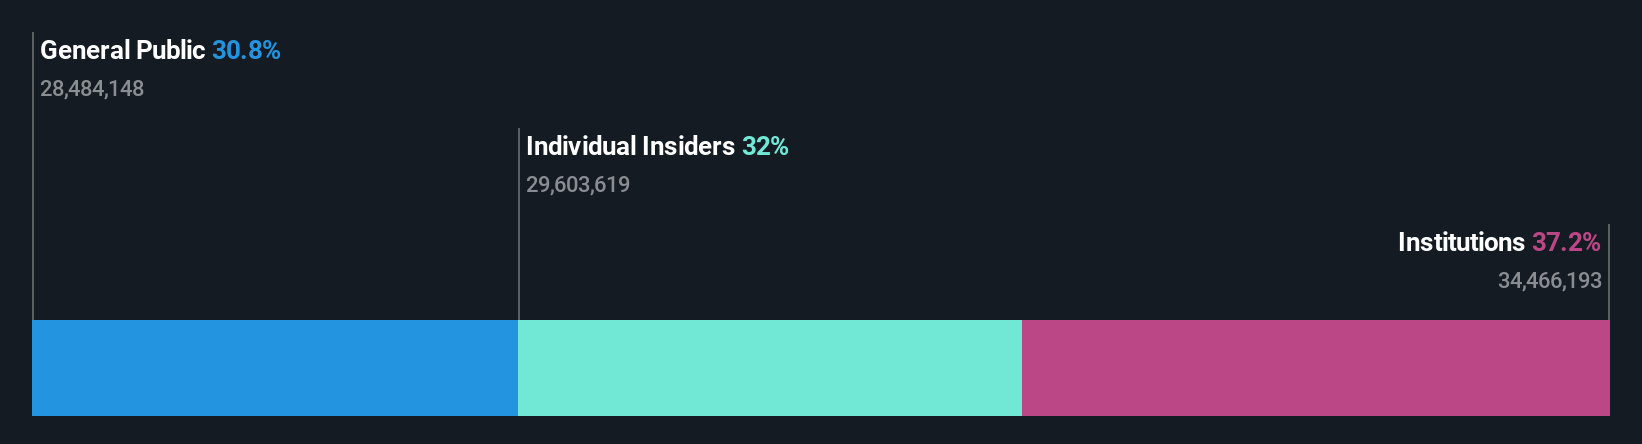
Insider Ownership: 32.6%
Earnings Growth Forecast: 15.5% p.a.
Bilia AB exhibits strong growth potential with forecasted earnings growth of 15.5% annually, outpacing the Swedish market's 7.3%. Despite a high level of debt, its recent financial performance shows improvement, with Q2 net income rising to SEK 230 million from SEK 192 million year-on-year. Trading at a significant discount to estimated fair value enhances its appeal, though insider ownership details are limited and dividend sustainability is questionable due to inadequate free cash flow coverage.
- Navigate through the intricacies of Bilia with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Bilia shares in the market.
Embracer Group (OM:EMBRAC B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Embracer Group AB (publ) is an international developer and publisher of PC, console, mobile, VR, and board games with a market capitalization of approximately SEK18.73 billion.
Operations: The company's revenue segments include PC, console, mobile, VR, and board games for the international games market.
Insider Ownership: 11.1%
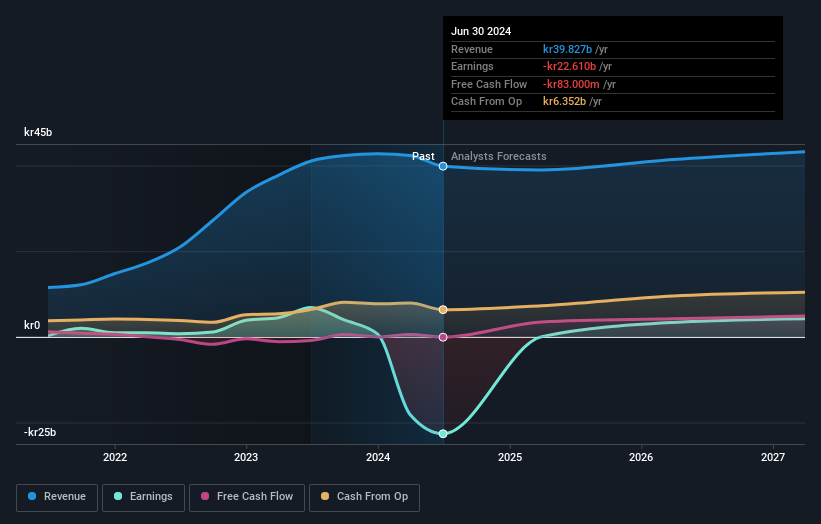
Earnings Growth Forecast: 97.7% p.a.
Embracer Group shows promising growth potential, with earnings expected to grow 97.69% annually and profitability anticipated within three years, surpassing average market growth. Recent earnings indicate a positive turnaround, with Q1 net income at SEK 39 million from a previous loss. Revenue rose to SEK 4 billion year-on-year. Trading below fair value adds appeal despite low forecasted return on equity (7.5%), and insider activity remains stable without significant recent trading changes.
- Click here and access our complete growth analysis report to understand the dynamics of Embracer Group.
- According our valuation report, there's an indication that Embracer Group's share price might be on the cheaper side.
Stadler Rail (SWX:SRAIL)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Stadler Rail AG is a company that manufactures and sells trains across various regions including Switzerland, Germany, Austria, Europe, the Americas, and the CIS countries with a market cap of CHF2.99 billion.
Operations: Stadler Rail generates revenue through its segments of Signalling (CHF210.99 million), Rolling Stock (CHF3.52 billion), and Service & Components (CHF1.09 billion).
Insider Ownership: 14.9%
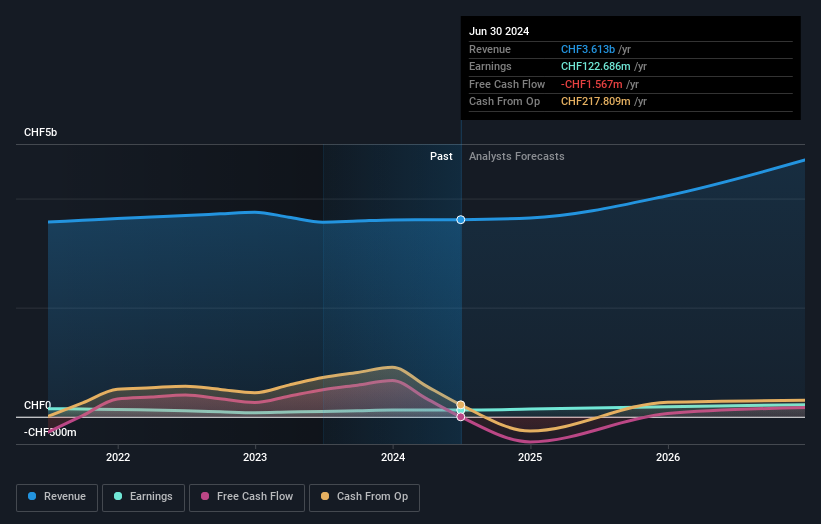
Earnings Growth Forecast: 28.8% p.a.
Stadler Rail demonstrates strong growth potential, with earnings forecasted to rise 28.79% annually, significantly outpacing the Swiss market. Recent half-year results show sales climbing to CHF 1.97 billion and net income doubling from the previous year. However, revenue growth is slower than ideal at 7.2% annually but still above market average projections. Trading well below estimated fair value enhances its investment appeal despite high debt levels and recent share price volatility without notable insider trading activity.
- Dive into the specifics of Stadler Rail here with our thorough growth forecast report.
- The valuation report we've compiled suggests that Stadler Rail's current price could be quite moderate.
Summing It All Up
- Click this link to deep-dive into the 216 companies within our Fast Growing European Companies With High Insider Ownership screener.
- Ready For A Different Approach? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com