
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sempra (SRE), What Is Behind The Fresh Attention?
Sempra (SRE) has reignited investor discussion after signing a 20-year LNG supply agreement with Petrobras related to its Port Arthur Phase 2 project, which involves approximately US$12 billion of planned capital spending.
Recent trading tells a mixed story. Sempra’s 1-day share price return of 0.59% contrasts with a 30-day share price decline of 5.74% and a 90-day slide of 9.38%, even as its 5-year total shareholder return of 47.73% keeps the long-term record in focus.
Scan how Sempra stacks up against other potential utility and infrastructure opportunities by reviewing the hand picked 37 power grid technology and infrastructure stocks that is aligned with long term energy demand.
After a solid 5 year record and a fresh LNG deal on the table, Sempra now sits in a very different spot than it did a year ago. Is today’s pullback enough of an entry, or is patience worth more?
Most Popular Narrative: 20.6% Undervalued
On the most followed view, Sempra’s fair value of $103.50 sits well above the recent $82.18 close. This puts the current pullback against a backdrop of fairly modest modeled growth and a relatively low discount rate of 7.11%.
Grid modernization, wildfire hardening, and the integration of renewables and storage in California and Texas will expand the company's regulated asset base and enable approved rate increases, supporting both margins and top-line growth as electrification and decarbonization accelerate.
See why 25 investors see Sempra as 21% undervalued.
Result: Fair Value of $103.50 (UNDERVALUED)
Still, the whole Sempra story can change quickly if regulators squeeze allowed returns in California, or if LNG projects face demand or policy setbacks.
Find out about the key risks to this Sempra narrative.
Another View On Sempra’s Valuation
A different lens tells a very different story. Our DCF model values Sempra at $46.57 per share, well below the recent $82.18 price, which points to the stock trading at a premium rather than at a discount. Which narrative do you trust more: the cash flow math or the market’s optimism?
To understand how this cash flow result is built and where the biggest sensitivities lie, it is worth unpacking the SWS DCF model in more detail Look into how the SWS DCF model arrives at its fair value..
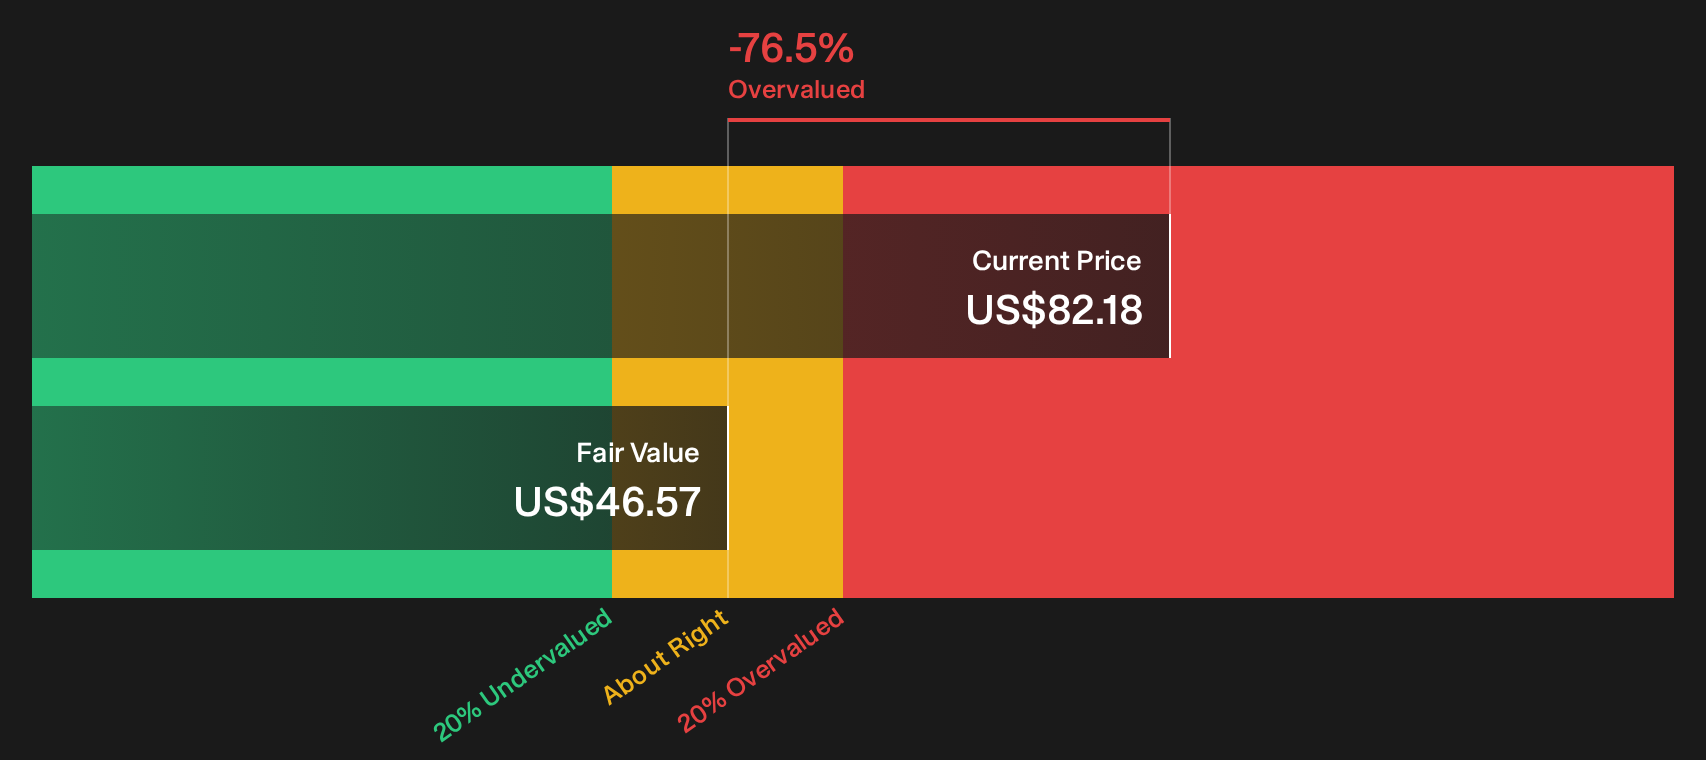
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sempra for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split verdict on Sempra has you on the fence, this may be a moment to act while sentiment is mixed and to test the numbers yourself by considering both risks and rewards. Start by weighing the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Sempra?
Do not stop your research with Sempra. Broaden your watchlist with a few targeted hunting grounds that focus on quality, value, and resilience.
- Zero in on quality for less by scanning the 29 high quality undervalued stocks that filters for companies combining fundamentals with prices that sit below estimated worth.
- Build a steadier income stream by reviewing a curated set of 6 dividend fortresses that focus on higher yields with an eye on sustainability.
- Protect your downside by combing through the 30 resilient stocks with low risk scores that concentrates on businesses with sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com