
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why CONMED (CNMD) Is Back In The Spotlight
Why CONMED Is Back In Focus After A Targeted Device Recall
CONMED (CNMD) moved into the spotlight after a voluntary Class II recall of its Genesys CrossFT Suture Anchor, tied to an incorrect patient implant card that could affect device identification and traceability.
The action covers a single lot and a quantity of 2 units, distributed within Texas but flagged as part of US nationwide distribution records. For investors, the scale looks limited. However, the situation raises practical questions about quality controls inside a business that reported US$1.37b in annual revenue.
Recent trading tells a mixed story for CONMED. The share price is down 6.35% over the past month but up 41.59% over 90 days and 13.84% year to date. By contrast, the 1 year total shareholder return is down 10.29%, with 3 and 5 year total shareholder returns lower again. This suggests that shorter term momentum has improved while longer term holders have seen material value erosion.
Spot potential alternatives to CONMED in the medical devices space by scanning our hand picked 30 resilient stocks with low risk scores that prioritize resilience and balance sheet strength.After a sharp 90 day rebound and a fresh recall hanging over sentiment, the real question for CONMED now is whether the current valuation still compensates you for the product and execution risks ahead.
Most Popular Narrative: 1% Overvalued
CONMED closed at $46.13 against a widely followed fair value estimate of $45.50. The current set up leans slightly ahead of that narrative while still hinging on how well management executes its medtech roadmap.
The accelerating adoption of minimally invasive and robotic-assisted surgeries, combined with CONMED's strong positioning via AirSeal and BioBrace (including expanding use cases and positive clinical feedback), is poised to support durable procedure volume growth and increase recurring revenue, driving sustained top-line growth.
Global mandates and rising legislative momentum around operating room air quality (e.g., smoke evacuation laws across an expanding number of states and international geographies) are significantly expanding CONMED's addressable market for Buffalo Filter, underpinning double-digit growth in this product line and broadening the company's long-term revenue base.
See why 3 investors see CONMED as 1% overvalued.
Result: Fair Value of $45.50 (OVERVALUED)
Still, the CONMED story can change quickly if supply chain setbacks linger or if hospital capital budgets stay tight and weigh on procedure volumes.
Find out about the key risks to this CONMED narrative.
Another View On CONMED’s Valuation
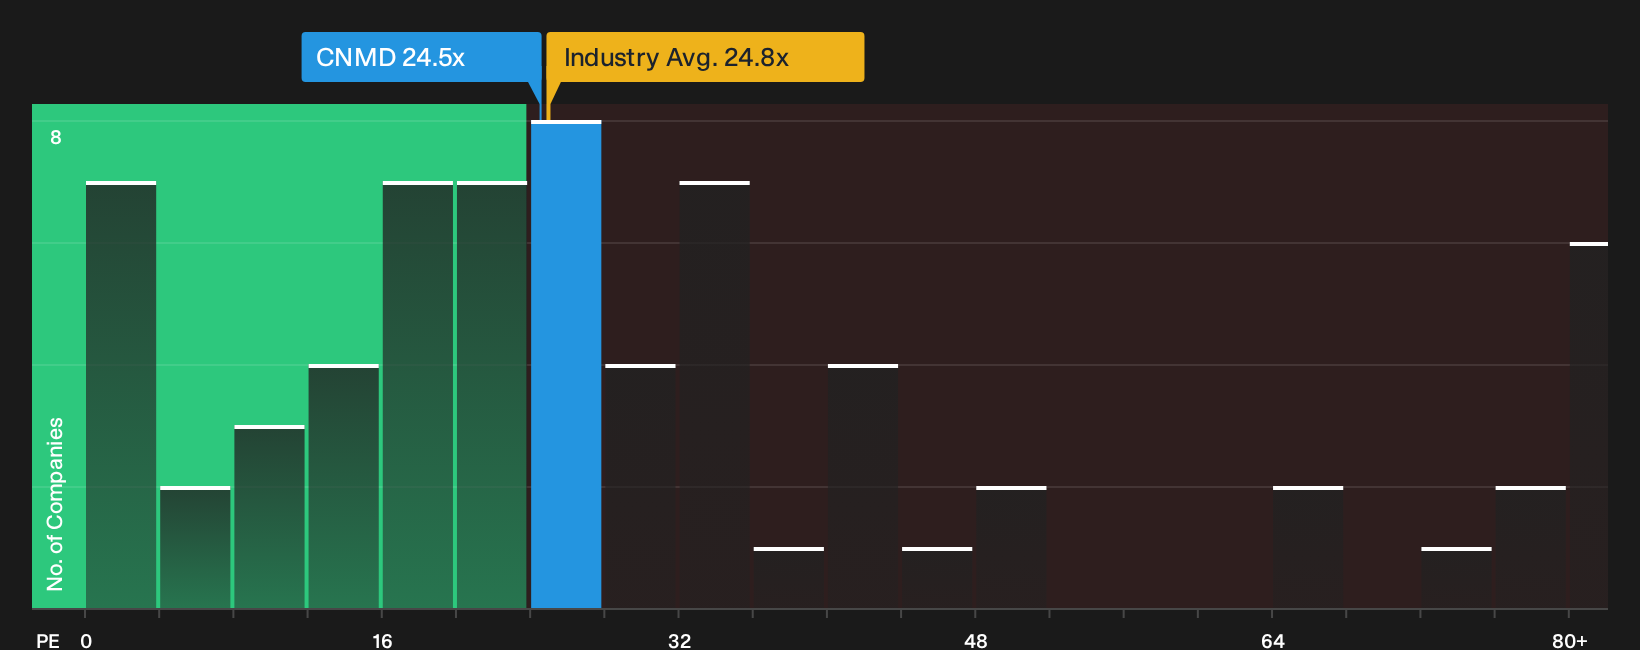
The first take says CONMED is 1% overvalued against a $45.50 fair value. A different lens points elsewhere. On a P/E of 24.5x, the stock trades below the industry on 25.2x and under a fair ratio of 31.9x, which could indicate a valuation that may move if sentiment changes.
That spread cuts both ways. It can signal a margin of safety if earnings forecasts prove accurate, or it can mark a value trap if profit quality or balance sheet risk has a greater impact than expected. Which story do you think the market is really pricing in here, and how long are you prepared to wait for an answer?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around CONMED's recall, valuation and sentiment can pull you in either direction, so move quickly and review the underlying data before forming a view, then weigh the 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond CONMED?
If CONMED has your attention, do not stop here. Broaden your watchlist with a few focused stock lists that can surface opportunities you might otherwise miss.
- Target resilient businesses with strong balance sheets by scanning our list of solid balance sheet and fundamentals (23 results) to help keep financial risk in check while you focus on the upside.
- Hunt for potential value candidates using our hand picked 29 high quality undervalued stocks, which filters for quality fundamentals at prices that may not fully reflect them yet.
- Lock in the income angle by reviewing our curated 6 dividend fortresses, which highlights higher yielding payouts backed by more robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com