
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FedRAMP Partner Expansion Might Change The Case For Investing In Commvault Stock (CVLT)
- Commvault Systems announced that qualified managed service provider partners can now deliver services built on its FedRAMP High Authorized Commvault Cloud for Government. This extends compliant data protection and cyber resilience offerings to U.S. federal agencies and Defense Industrial Base organizations.
- This move gives Commvault a way to scale into regulated public sector workloads through partners, aligning its cyber resilience platform with FedRAMP and CMMC requirements rather than relying solely on direct federal sales channels.
- We will now assess how Commvault's FedRAMP High partner expansion could influence its investment narrative around recurring, compliance driven workloads.
Commvault Systems Investment Narrative Recap
To own Commvault Systems, an investor needs to believe the shift toward subscription cyber resilience and compliance-centric workloads can support durable demand, even as the mix pressures margins. The short term story still hinges on execution in SaaS and managed services, where tighter security requirements create steady but competitive opportunities.
The biggest risk remains margin compression and earnings volatility as the model tilts further to SaaS and large, timing-sensitive deals. The new FedRAMP High partner expansion looks supportive but not transformational in the near term. It broadens routes to market rather than changing the core dependence on recurring cyber resilience workloads.
The Commvault Cloud for Government FedRAMP High partner expansion is the clearest operational bridge between today’s news and the existing catalyst list. It directly ties the platform to regulated public sector workloads where compliance is mandatory, not optional, and where recurring contracts can be sticky once embedded.
This move also concentrates execution risk. Success now depends on MSP partners selling and operating Commvault services effectively, while the firm manages integration costs, keeps margins in its guided low 80% gross range, and avoids overreliance on a handful of large public sector or Defense Industrial Base deals.
Commvault Systems' consensus narrative points to US$1.6b in revenue and US$161.8m in earnings by 2029, based on analysts modelling 10.6% yearly revenue growth. That profit outlook implies an earnings increase of about US$93.5m from US$68.3m today.
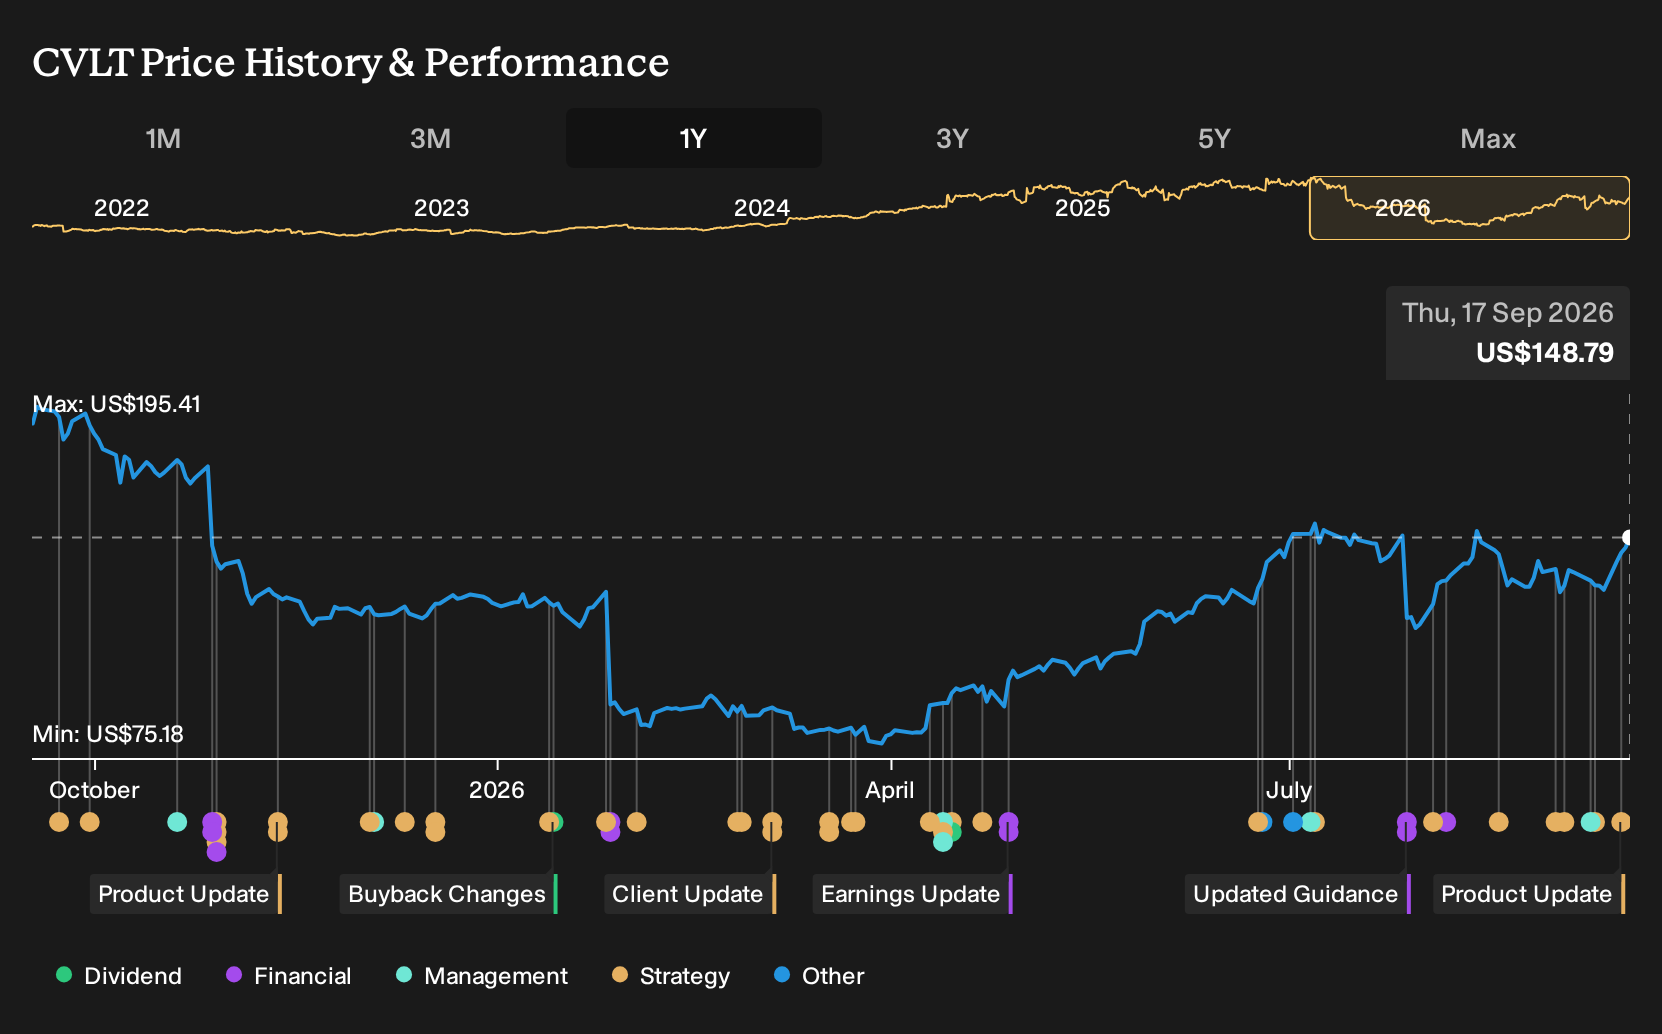
Uncover why Commvault Systems' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts see Commvault Systems less as a margin story and more as a scale play. They were already modelling about US$1.7b of revenue and US$166.2m of earnings by 2029, slightly above consensus, before this FedRAMP High partner move. That more upbeat view leans heavily on faster SaaS and identity resilience traction. This latest public sector push could eventually shift their narrative further or prompt you to question it, depending on how you weigh the execution risk.
Explore 3 other Commvault Systems fair value estimates, including one that suggests as much as 44% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Commvault Systems research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Commvault Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Commvault Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Commvault Systems?
Once you have a view on Commvault Systems, it helps to widen the lens and compare it with other opportunities that match your risk profile and income goals. The Simply Wall St Screener can surface a range of stocks that share traits like resilience, balance sheet strength, or attractive pricing.
- For investors who care most about capital protection and steadier profiles, review a basket of 30 resilient stocks with low risk scores that aim to keep risk scores contained while still offering equity upside.
- If value is your priority, scan a curated set of 29 high quality undervalued stocks that combine stronger fundamentals with prices that sit below fair value estimates based on cash flows and assets.
- For those building an income-focused portfolio, weigh a group of 6 dividend fortresses that pair higher yields with an emphasis on sustainability and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com