
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Deere (DE) Could Be 10% Overvalued On Strong Earnings And Fed Backdrop
What Sparked The Latest Move In Deere
Deere (DE) has swung back into focus after a Q2 earnings surprise, with revenue and profit above expectations, alongside a 2.4% share price gain following the Federal Reserve’s latest interest rate increase.
That earnings surprise slotted into a wider upswing for Deere, with a 30-day share price return of 16.46% feeding into a 46.88% year to date gain, as investors weigh stronger precision agriculture adoption against shifting interest rate expectations and sector risk. At the same time, a 1-year total shareholder return of 45.81% and 5-year total shareholder return of 108.31% point to momentum that has been building rather than fading.
Scan beyond Deere and see how other machinery and infrastructure players are reacting to the same rate backdrop with our curated list of 37 power grid technology and infrastructure stocks.
Deere looks like a powerhouse on recent numbers and share price action. The real tension now is simple: Are investors paying a fair price for that strength, or stretching too far after the latest move?
Most Popular Narrative: 10% Overvalued
The most followed storyline on Deere pegs fair value at $685.19, which sits just below the last close of $685.63, and leans on a richer margin outlook rather than rapid top line expansion.
Global improvements in farm fundamentals outside North America, such as strong dairy profitability and crop yields in Europe, expanding acreage and profits in Brazil, and stable acreage with favorable credit in India, signal a demand recovery for advanced farm equipment, which could reaccelerate Deere's revenue and earnings as end markets inflect positively.
See why 111 investors see Deere as 0% overvalued.
Result: Fair Value of $685.19 (OVERVALUED)
Still, Deere’s story can be knocked off course if tariff costs bite harder than expected or if North America large ag demand remains weak for longer.
Find out about the key risks to this Deere narrative.
Another View On Deere’s Valuation
The popular storyline frames Deere as roughly 10% overvalued around $685, based on analyst targets and profit margin assumptions. A different lens tells a very different story. Simply Wall St’s DCF model estimates future cash flows at $759.71 per share, which puts the current price about 9.8% below that figure and screens as undervalued instead. Which framework do you trust more when real money is on the line?
For a closer look at how those projected cash flows translate into that $759.71 estimate, take a moment to walk through the Look into how the SWS DCF model arrives at its fair value.
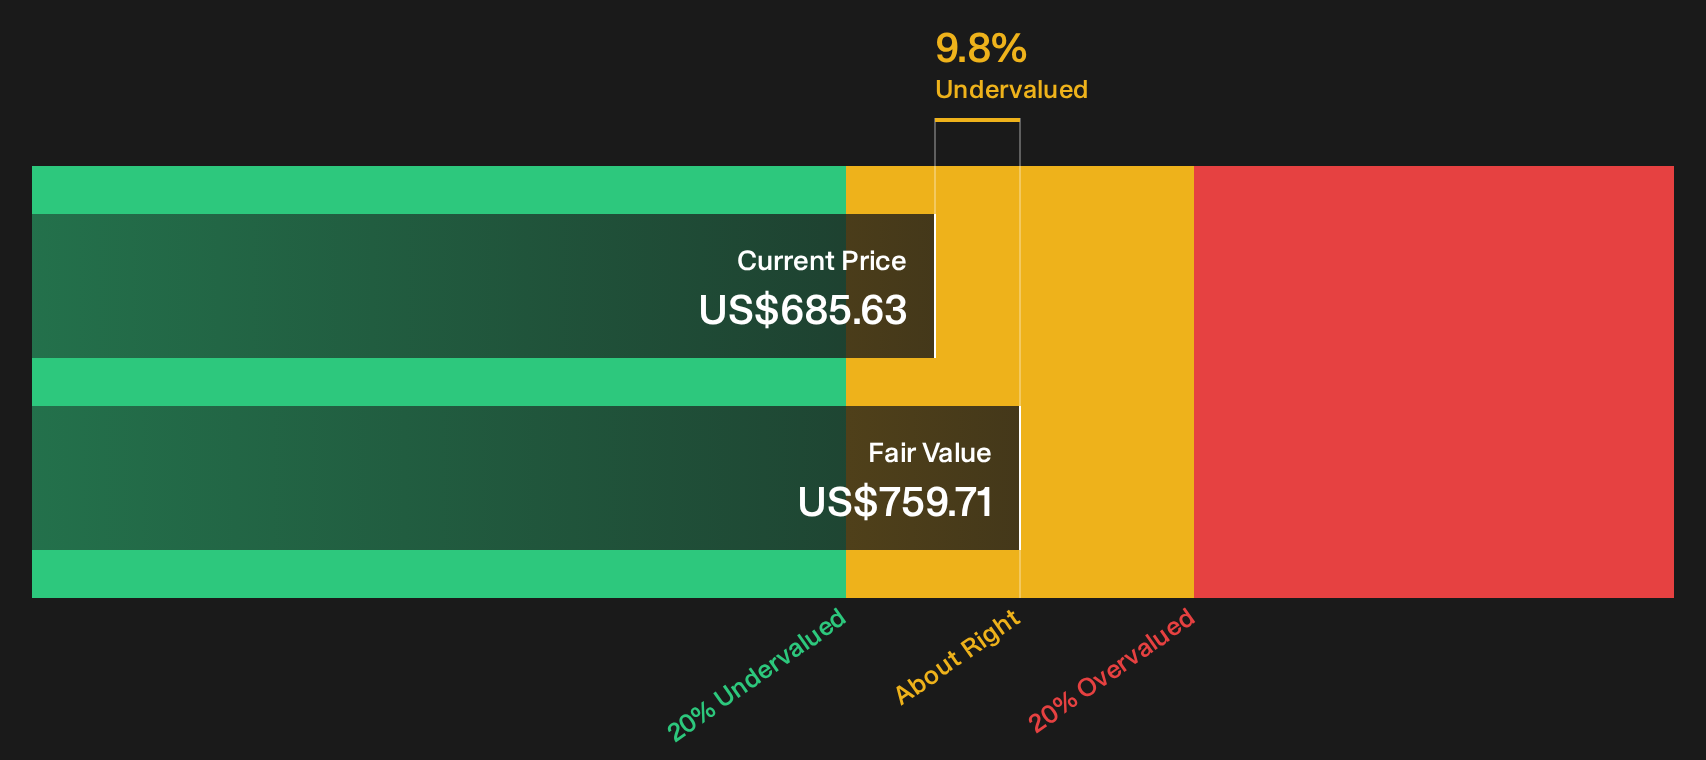
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Deere for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Deere’s value story so far. Check the numbers yourself, weigh both the potential upsides and flagged issues, then review the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Deere?
Do not stop your research with Deere alone. Fresh ideas often come from comparing strong businesses across sectors, risk profiles, and balance sheet strength.
- Spot potential underpriced opportunities early by scanning our 29 high quality undervalued stocks before other investors focus on them.
- Identify income-focused ideas by reviewing the 6 dividend fortresses that could help support a steady cash flow profile.
- Prioritize resilience and capital protection by filtering for 30 resilient stocks with low risk scores that may suit a more defensive approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com