
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hub Group (HUBG) Could Be 21% Below Fair Value On 2026 Loss Warning
Hub Group (HUBG) is back in focus after management flagged an operating loss for the first half of 2026, tied to accounting restatement costs and higher fuel, rail, and drayage expenses.
Hub Group’s share price has fallen 24.7% over the past three months and is down 21.9% year to date. The recent 15.9% one month share price decline suggests momentum has weakened as investors weigh the accounting restatement, leadership changes, and fresh 2026 guidance against the latest 9.3% one year total shareholder return.
Compare how Hub Group’s situation stacks up against other transport and logistics players by scanning a curated list of list of solid balance sheet and fundamentals (23 results) for context on quality and resilience.
Hub Group still runs a sizeable, diversified logistics platform, yet the share price reset and restatement overhang leave a different question in front of you now. Are you paying a fair price for that underlying freight engine today?
Most Popular Narrative: 21% Undervalued
Hub Group's most followed narrative pegs fair value at $42.20, which sits above the latest $33.38 close and frames the recent pullback as a valuation gap rather than just sentiment pressure.
The company's strategy of targeted, accretive acquisitions (e.g., Marten Transport's refrigerated intermodal business), along with a strong balance sheet and cash flow generation, provides catalysts for both inorganic top-line growth and earnings acceleration, as Hub Group leverages synergies, broadens its service offering, and scales differentiated solutions across its national footprint.
See why 2 investors see Hub Group as 21% undervalued.
Result: Fair Value of $42.20 (UNDERVALUED)
Still, the restatement investigations and Nasdaq filing deficiency create real headline risk for Hub Group, and any setback on those fronts could quickly challenge this view that the shares are undervalued.
Find out about the key risks to this Hub Group narrative.
Another View On Hub Group’s Valuation
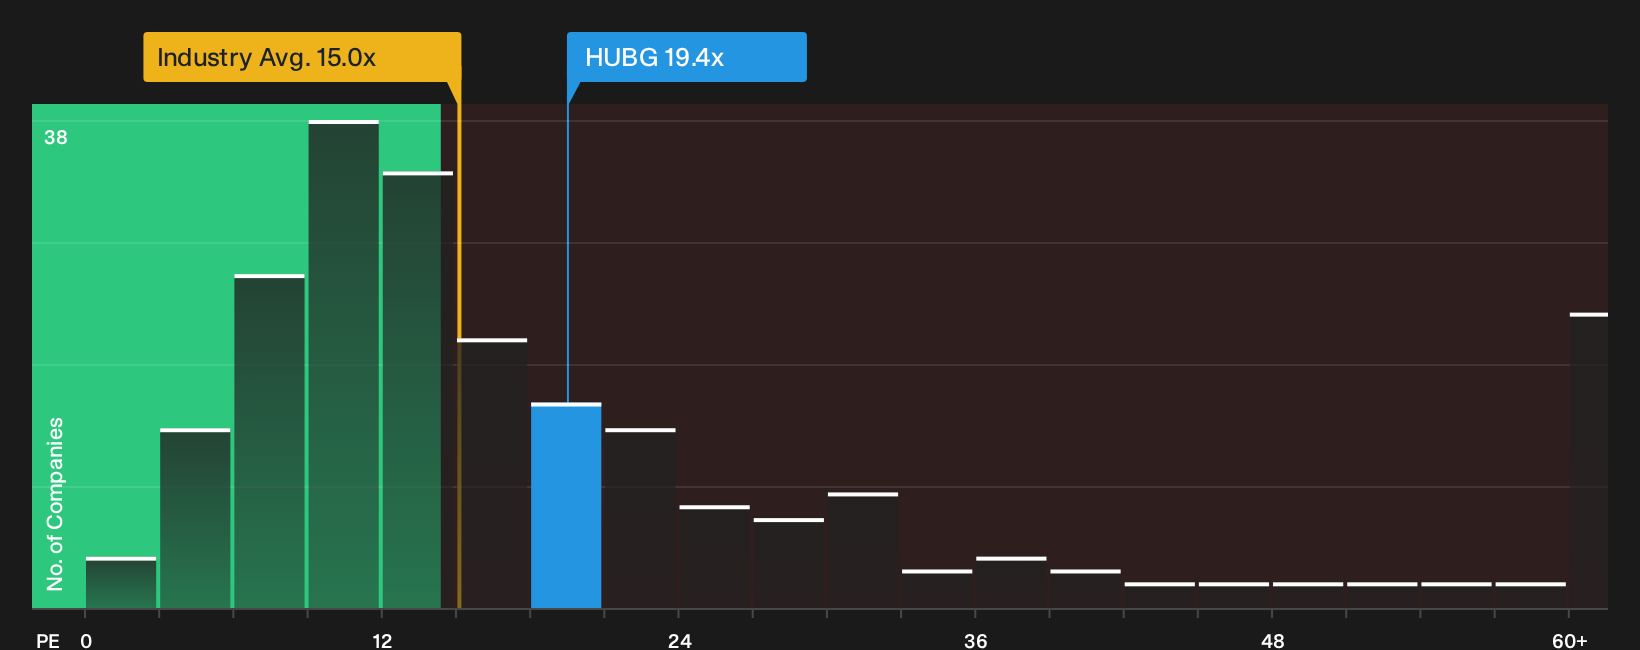
On traditional earnings multiples, Hub Group screens less generous than that 21% undervalued story suggests. The stock trades on a P/E of 19.4x, which is higher than the global logistics industry average of 15x and above its own fair ratio of 13x. That gap points to real valuation risk if the market leans back toward the lower fair ratio instead of the richer peer group. How comfortable are you relying on the more optimistic fair value estimate today?
For a closer look at how earnings and pricing line up, including that gap between the current P/E, peers, and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the combination of restatement risk and valuation debate leave you unsure which side to take on Hub Group right now? Move quickly, review the underlying data for yourself, and consider the potential upside signalled by 2 key rewards
Hunting For More Hub Group Style Ideas?
If Hub Group has you reassessing your watchlist, this is the moment to widen the lens and line up fresh candidates before the next move happens.
- Target resilient balance sheets and solid fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results). This can help anchor your portfolio when conditions change.
- Spot potential mispricings early by reviewing a focused 29 high quality undervalued stocks that highlights businesses where quality and current valuation appear out of sync.
- Stack income potential on top of your core holdings by filtering through a handpicked 6 dividend fortresses built for investors who care about reliability as much as yield.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com