
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Price Hikes Could Be A Big Test For Nebius Stock (NBIS)
- Nebius Group has informed customers that from 1 October 2026 it will raise prices across key on-demand Nvidia GPU and AMD CPU cloud services, including H100 and B300 instances and EPYC Genoa based compute.
- The fresh round of pricing changes, coming only months after earlier increases, highlights how tight AI compute capacity is influencing Nebius Group’s pricing power and cost recovery on heavy data center investments.
- The focus now turns to how Nebius Group's investment narrative is affected by this renewed pricing power on AI infrastructure.
Scan beyond Nebius Group and review how other AI infrastructure players are priced by exploring the hand picked 89 AI infrastructure stocks that are also leaning into tight compute capacity and rising demand.
Nebius Group Investment Narrative Recap
To own Nebius Group, you need to believe that AI cloud demand stays strong enough for the firm to keep filling new GPU capacity and justify heavy data center spending. The recent price hikes and volume reaction point to tight supply rather than a demand problem. The key near term swing factor is how quickly that contracted backlog turns into cash without straining liquidity.
On the risk side, the story still leans on aggressive capex, modest net margins at 3.1%, and very high valuation multiples such as a 44.1x P/S. Any stumble in deploying hardware on time, customer onboarding, or regulatory friction around data sovereignty could hurt utilization and make the current pricing power feel short lived.
The Palantir partnership announced on 8 September 2026 looks tightly linked to the current pricing news. Palantir is naming Nebius Group as its preferred sovereign AI infrastructure partner and plans to pull Nebius compute and inference endpoints inside its own perimeter for eligible commercial clients. That creates a clearer distribution channel into enterprises that want more control over data and models.
This arrangement also intersects directly with Nebius Group’s biggest catalyst and its main risk. Demand visibility could improve as Palantir workloads scale on Nebius clusters, which would help support the heavy investment plan. At the same time, execution becomes more complex because Nebius must deliver modular data center capacity, maintain performance for demanding AI jobs, and do so while competition for those same customers intensifies.
Nebius Group's narrative projects US$30.3b revenue and US$2.4b earnings by 2029. This assumes revenue grows at 181.9% per year and earnings increase by about US$2.36b from US$42.4m today.
Uncover why Nebius Group's fair value indicates a 43% potential upside to its current price that could narrow quickly.
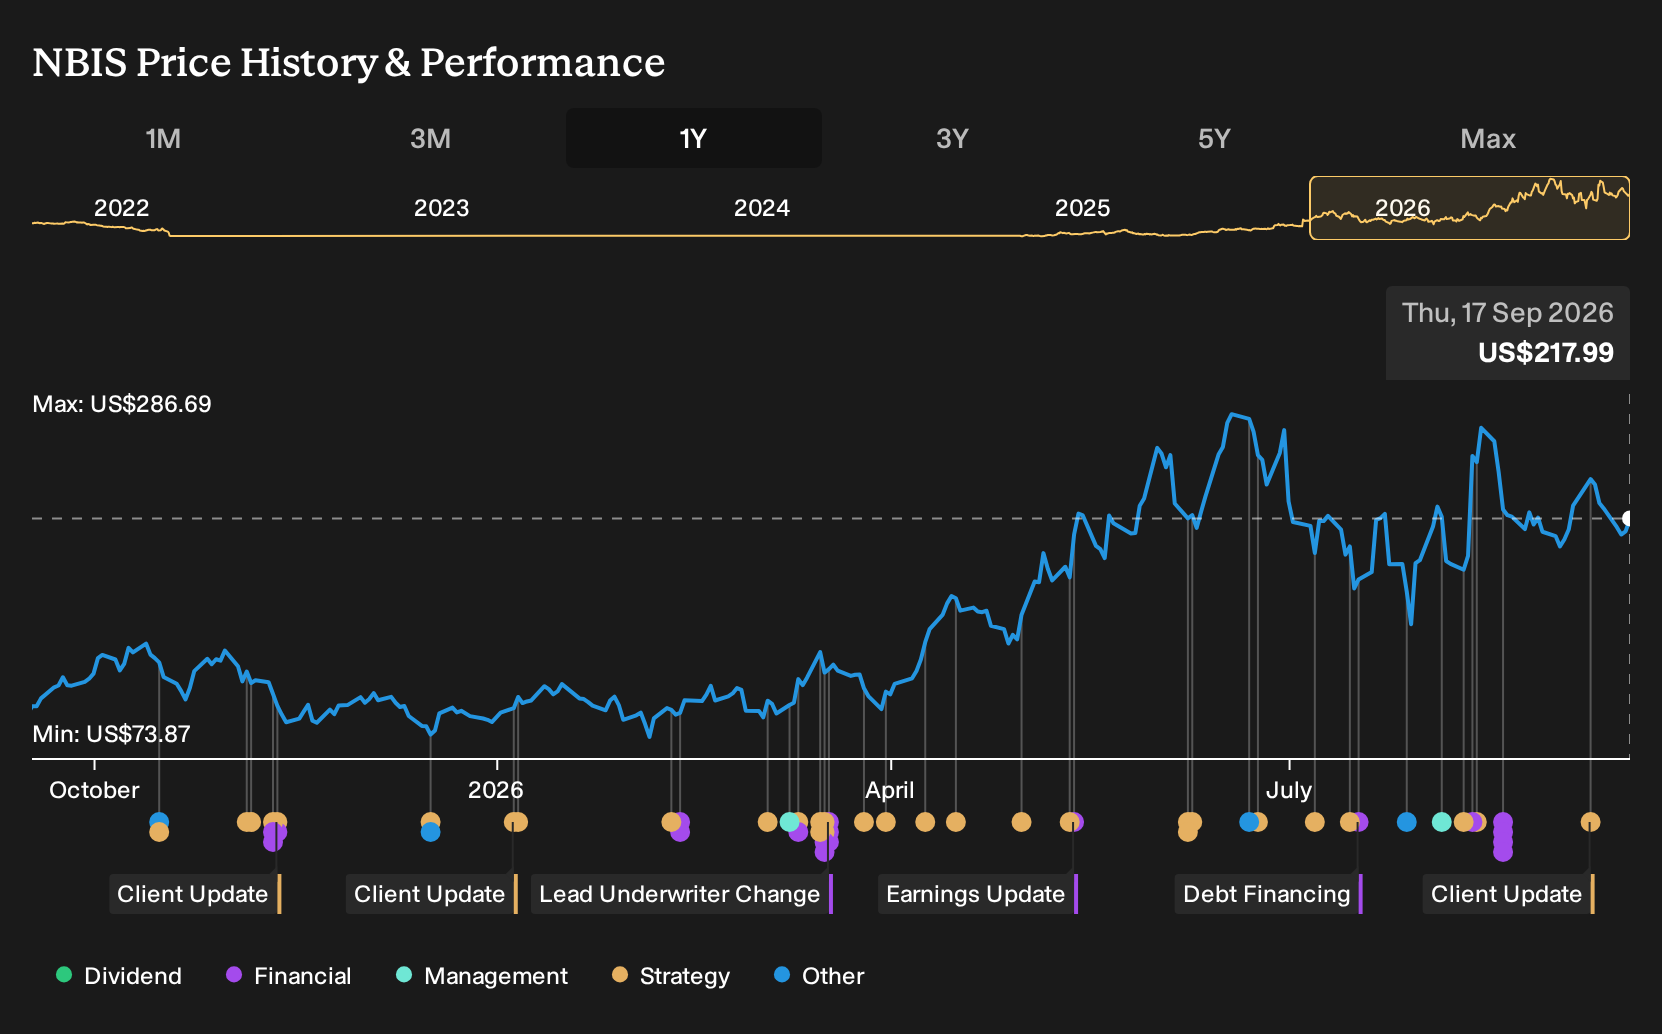
Exploring Other Perspectives
Some of the most optimistic analysts frame the Palantir partnership as the real catalyst. They already projected Nebius Group could reach US$48.5b in revenue and US$1.1b in earnings by 2029, well above the baseline. You can treat today’s pricing and partnership news as a fresh reason to compare those opposing narratives.
Explore 14 other Nebius Group fair value estimates, including one that suggests there could be as much as 90% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nebius Group research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nebius Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nebius Group's overall financial health at a glance.
Looking For More Ideas Beyond Nebius Group?
If Nebius Group has sharpened your interest in AI infrastructure and high growth stories, it can be useful to balance that with other types of opportunities across the market using the Simply Wall St Screener.
- If you want potential mispricings with quality metrics behind them, scan through a curated set of 29 high quality undervalued stocks that combine fundamentals with compressed expectations.
- For investors who care most about balance sheet strength and downside protection, filter for companies in the list of solid balance sheet and fundamentals (23 results) to see which businesses pair robust finances with cleaner risk profiles.
- When you are hunting for future leaders that are not yet widely followed, use the 16 high quality undiscovered gems to surface under-the-radar companies backed by solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com