
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vicor Stock Has The Bull Case Changed After Licensing Deal
- Vicor Corporation recently granted a non-exclusive Vertical Power Delivery license to a new OEM, and it is also expanding ChiP fab capacity in New Hampshire to support growing demand for its AI focused power modules.
- The combination of patent backed VPD licensing that allows sourcing from unlicensed suppliers and new U.S. fabs points to a push for multi source supply security and broader adoption across hyperscale compute customers.
- We will now look at how Vicor's expanded U.S. manufacturing footprint could reshape the investment narrative around its power components.
Scan beyond Vicor and line up other AI infrastructure plays using our curated list of 89 AI infrastructure stocks to see how this licensing and capacity story compares across the sector.
Vicor Investment Narrative Recap
To be comfortable as a Vicor shareholder, you need to believe its AI focused power portfolio, especially Vertical Power Delivery, can turn design wins and licensing into steady product demand that uses its expanding U.S. fab capacity. The new VPD license supports that belief by broadening potential module sourcing and making Vicor’s IP more embedded in AI compute supply chains.
The key near term swing factor remains order stability and backlog quality, given prior signs of weaker book to bill and cancellations. The biggest risk is still underutilized fabs and volatile licensing revenue. This licensing move helps the story, but does not on its own resolve demand uncertainty.
The announcement that Vicor is buying large sites in Merrimack and Hooksett for ChiP Fab 2 and Fab 3 ties directly into the VPD news. Vicor is effectively pairing more flexible VPD licensing with a plan for much larger ChiP output, particularly its MCM current multipliers that sit at the center of VPD based systems.
For you, the connection is straightforward. If AI data center demand for VPD modules and related converters holds up, those New Hampshire fabs can help dilute fixed costs and lift margins over time. If bookings stay choppy and licensing outcomes are uneven, that extra footprint increases the pressure on Vicor’s execution and cost discipline.
Vicor's current consensus narrative points to revenue of US$1.4b and earnings of US$453.8 million by 2029, based on an annual top line growth assumption of 43.7%. That profile uses earnings today of US$145.3 million, which implies an increase of about US$308.5 million to reach the 2029 consensus level.
Uncover how Vicor's fair value indicates a 78% potential upside to its current price, which could narrow quickly if sentiment around Vicor shifts.
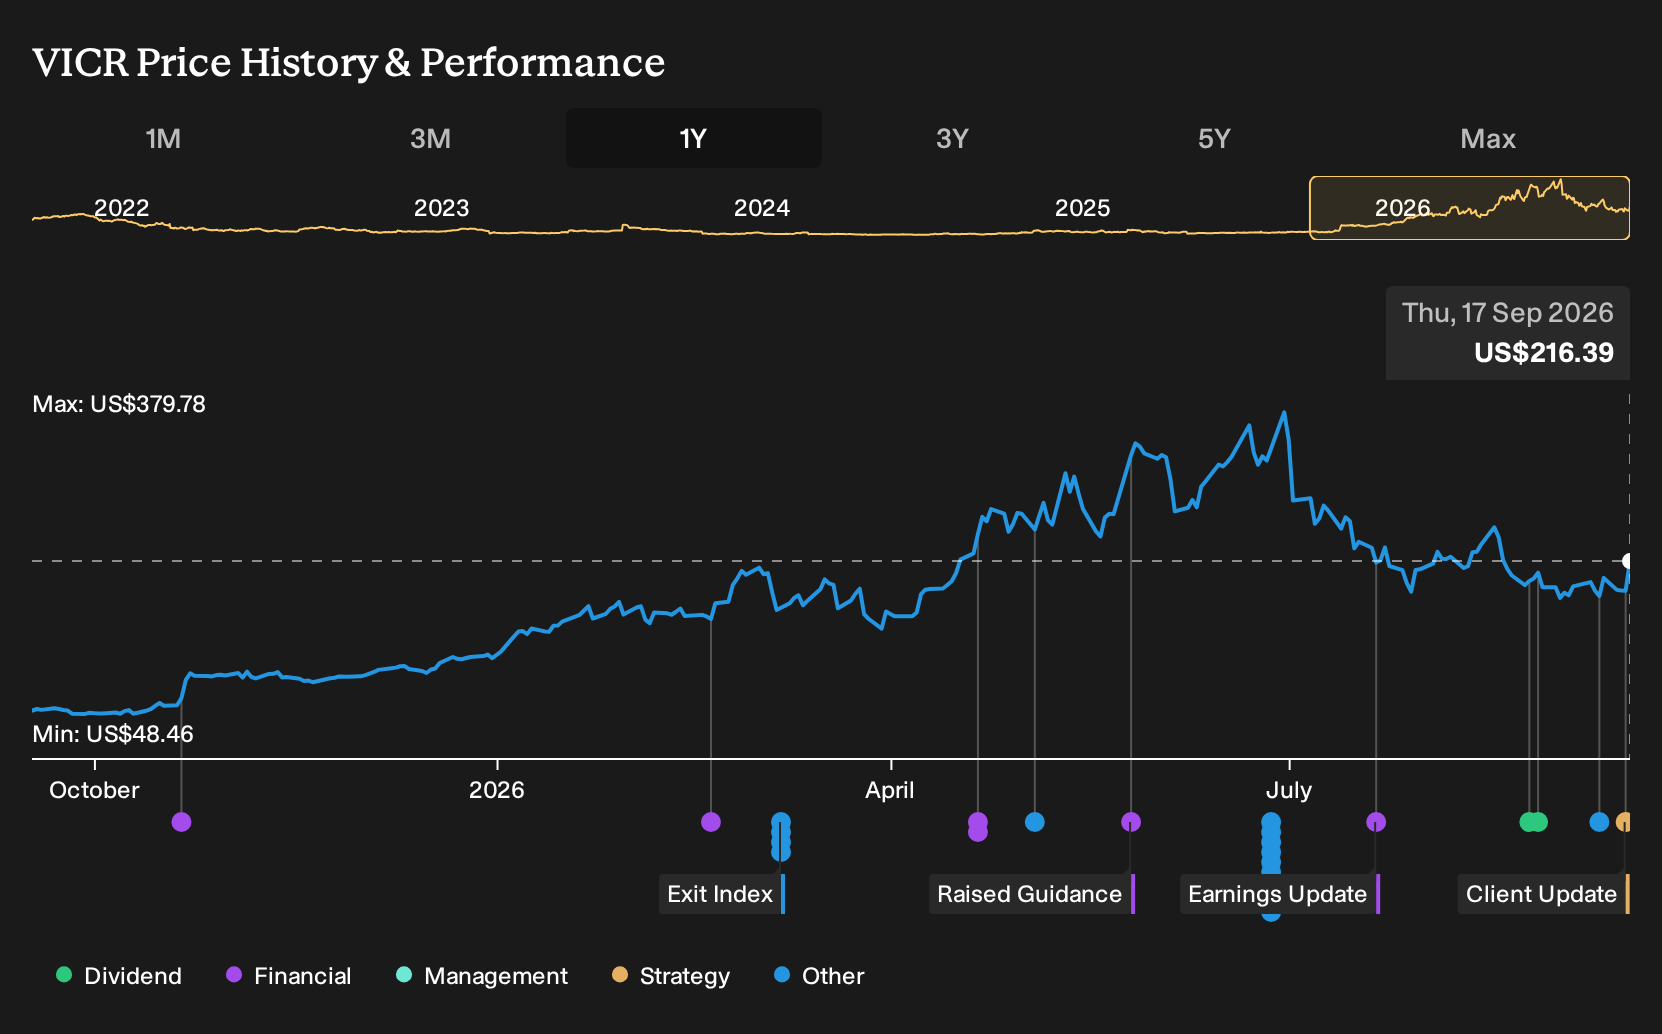
Exploring Other Perspectives
One alternate take focuses on Vicor’s IP licensing as the real swing factor. The most optimistic analysts were already modeling revenue at about US$1.6b and earnings near US$486.1 million by 2029, assuming rapid royalty growth. You can now ask whether this new VPD license and multi source flexibility push those expectations higher or make them look stretched.
Explore 3 other Vicor fair value estimates, including one that suggests as much as 78% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vicor research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vicor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vicor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vicor?
If Vicor has sharpened your focus on high conviction themes, it can help to line it up against a wider field of opportunities using the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, scan a curated group of companies trading below their estimated worth through our 29 high quality undervalued stocks.
- If steady income is your priority, compare dividend payers with robust yields and payout histories by reviewing a focused set of 6 dividend fortresses.
- For those who care most about resilience, filter for businesses with stronger finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com