
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Maase (MAAS) Stock Could Be Overvalued On Fresh AI Services Deals
Maase Inc. has been on a sharp run, and the question now is whether a share price around US$16.20 can still be squared with what its balance sheet is actually worth. With that kind of move on the screen, the issue for investors is how much of Maase’s current market value is supported by its book value rather than short term excitement.
- Over the past year, Maase has returned about 356.3%, which puts a lot of weight on whether its current valuation can be anchored to the equity it has already built up.
- The new AI computing and token based service agreements, together worth over RMB 100 million, may support expectations for higher future profitability that investors could be capitalising into the stock price.
- Maase's multiple only means something next to the competition. See how Maase's 14.4x P/B compares with its peers.
The issue now is whether Maase’s latest price can be reasonably explained by its book value or whether investors are paying far above the net assets on the balance sheet.
If you want context for Maase's AI push and sharp 1 year run, compare it with other 35 AI small caps.
Is Maase Getting Expensive on Book Value?
Price to book fits Maase because the business is being valued partly on the equity it has already built rather than on current earnings.
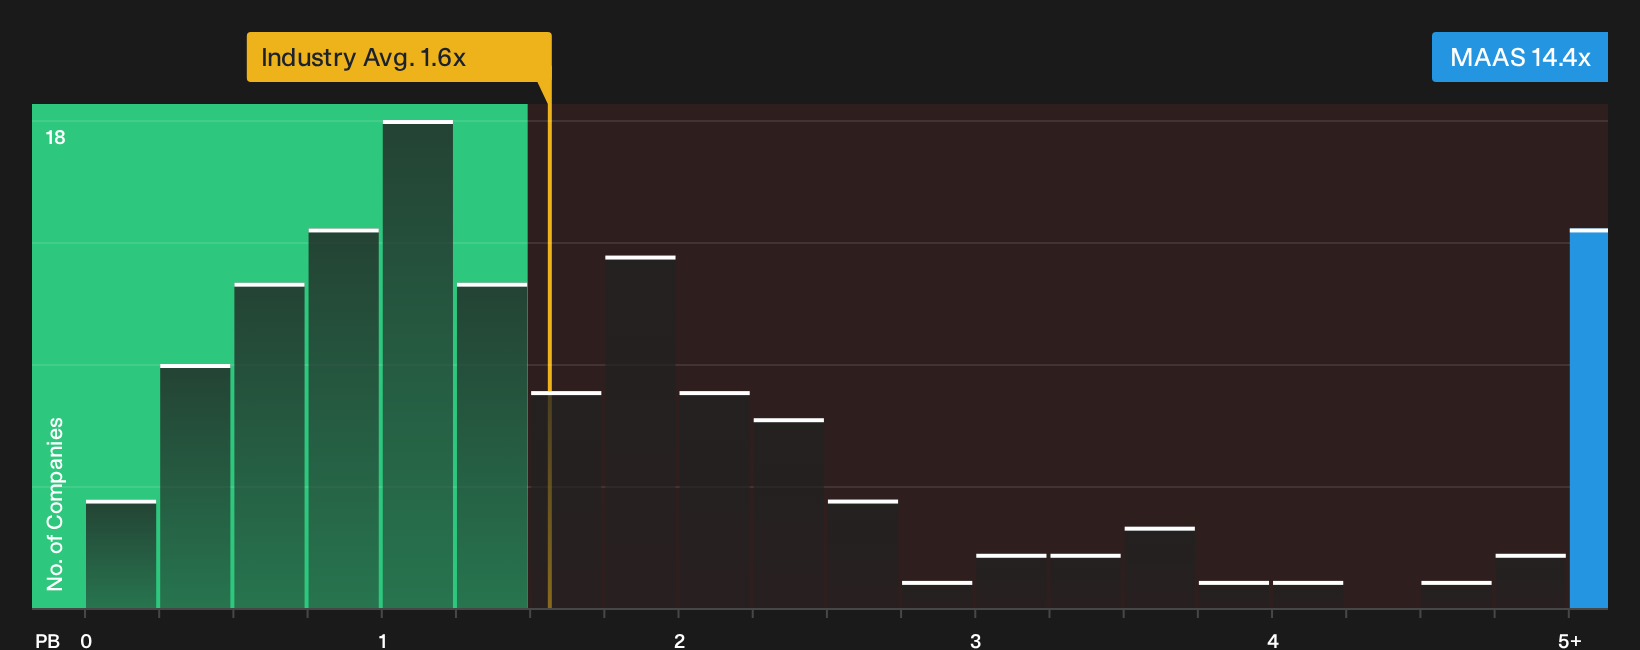
At a P/B of about 14.4x, Maase trades at a large premium to both the broader insurance industry average of 1.6x and a peer group near 6.4x. That gap suggests that investors are paying a high price for each dollar of net assets, which indicates the stock may be overvalued on this yardstick compared with sector norms.
Because Maase has recently signed sizable AI computing and token based service agreements, some buyers may be using those contracts to justify paying far above the balance sheet value in the expectation that these ventures will reshape the business mix. The key question for you is whether that AI push can support such a rich P/B over time or whether expectations have moved ahead of what the current equity base can reasonably support. Explore the numbers behind Maase's P/B valuation.
The Maase Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Maase pick up where the high P/B puzzle leaves off and outline the specific growth, margin and earnings paths that would need to occur for Maase's share price to end up meaningfully higher or lower than it is today. Rather than providing a single valuation output, these scenarios describe the future that figure depends on so you can track how Maase's actual progress compares with that story on the Community page.
A written, number driven narrative on Maase gives you a clear set of assumptions to stress test as the new AI computing and token based agreements move from contract stage to real world cash flow. It becomes a reference point you can revisit as Maase's execution on those AI services either lines up with, exceeds, or falls short of the paths that are laid out.
Share your own Narrative for Maase and set out the assumptions behind your valuation.
Before acting on Maase's valuation, one more factor deserves your attention
Before you lean too heavily on Maase's numbers, it is worth asking who is steering the business and how their pay packets line up with your interests. See who runs Maase and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com