
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CarMax (KMX) Stock Still Looks Rich Against Its Earnings Power
CarMax has delivered a mixed ride for shareholders, with a sharp decline over longer periods but a strong recovery more recently. That kind of whiplash puts the spotlight squarely on one issue for the used car retailer: whether the current share price lines up with what its earnings can reasonably support.
- The stock has fallen 58.9% over the past 5 years, which puts long term capital allocation and the strength of the underlying earnings story under close scrutiny.
- The business depends heavily on converting used vehicle sales and financing operations into consistent profit, so the durability and quality of those earnings can shape how much investors are willing to pay for each dollar of income.
- Your read on CarMax is one view; the desks covering it have another. See what analysts think CarMax's shares could be worth.
The stock's next move may depend on whether CarMax's current earnings justify the valuation investors are placing on the business today.
If CarMax has you questioning what you are really paying for each dollar of earnings, a focused screen of 29 high quality undervalued stocks can give you more starting points for comparison.
Has CarMax Run Too Far on Earnings?
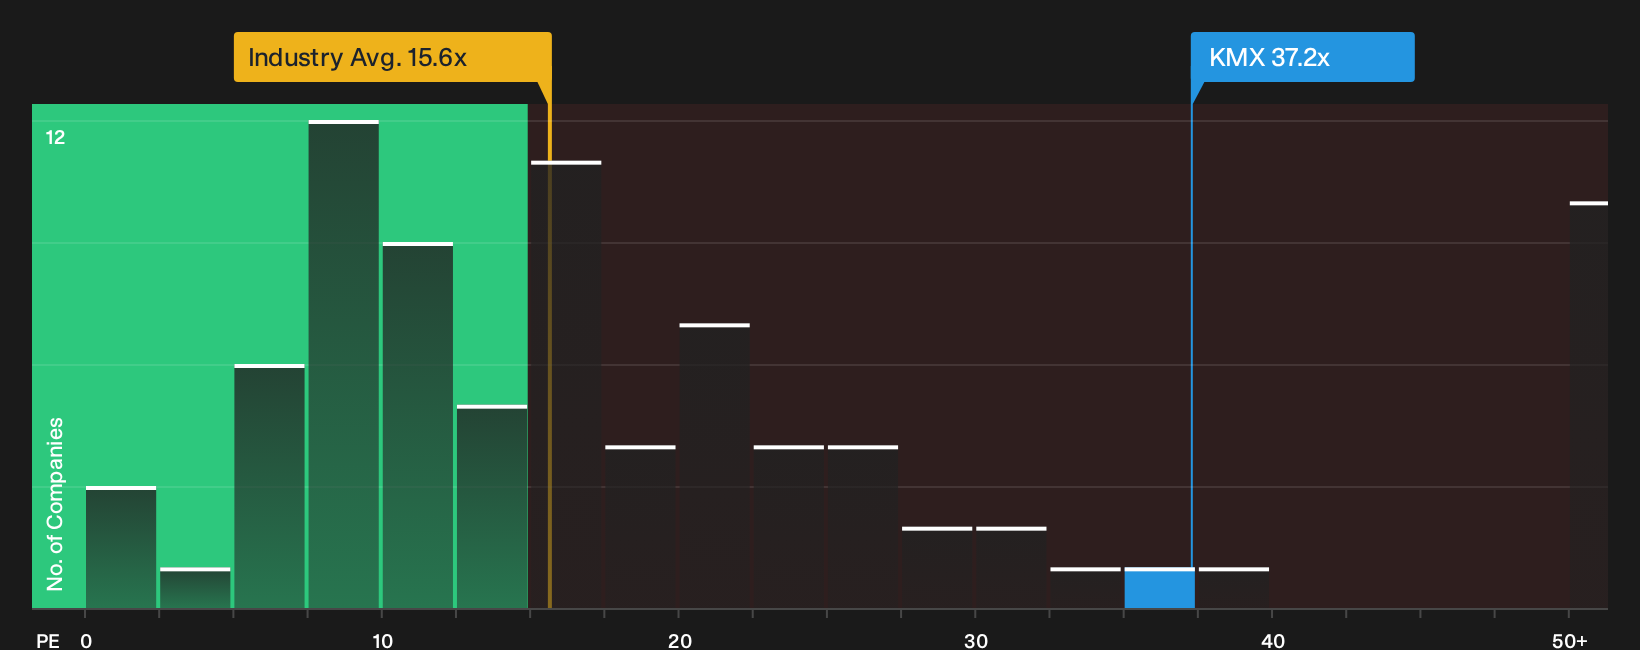
P/E works well for CarMax because earnings are a core focus for how investors judge a retailer that depends on steady used vehicle turnover and financing income. On this lens, the stock trades on a P/E of 37.2x, which is well above the Specialty Retail industry average of 15.6x and also higher than the peer group average of 12.1x.
The Fair Ratio model, which tries to gauge what a more tailored P/E might look like after factoring in CarMax's business profile and risks, still points to a lower figure than where the shares trade now. That gap indicates the stock screens as overvalued on earnings compared with what this framework suggests investors might usually pay for a retailer with similar characteristics. For anyone weighing CarMax today, the question is whether the used car chain's earnings power and business quality justify paying that kind of premium multiple. Explore the numbers behind CarMax's P/E valuation.
The CarMax Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St's Community page pick up where the CarMax valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today. Each CarMax narrative frames fair value as a specific, testable view on the business that you can track over time as new information comes through.
CarMax splits the community, with one camp leaning into a turnaround story and the other stressing execution risks at a full-looking valuation.
Bull case: 29% undervalued
"Significant cost efficiency gains from expanded reconditioning and auction facilities, logistics optimization, and streamlined service operations are driving down cost of goods sold per unit…"
Discover why this Narrative puts CarMax at 29% undervalued.
Bear case: 6% overvalued
"Macroeconomic and competitive pressures challenge CarMax's margins and growth, with rising inventory and loan costs and uncertainties affecting profitability and strategic clarity…"
Explore why this Narrative puts CarMax at 6% overvalued.
Before acting on CarMax's valuation, one more issue deserves attention
CarMax's earnings multiple and competing narratives tell only part of the story. Our research has also flagged specific concerns that investors may want to weigh carefully before making a move. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com