
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SK Hynix (NasdaqGS:SKHY) Stock Still Looks Like A Bargain Despite New ETF Attention
SK Hynix has had a strong run recently, and with the stock closing at US$182.99, the real question now is whether that price still lines up with what its earnings can support. With such a move in a volatile semiconductor market, investors are increasingly asking if the market is paying too much attention to momentum and not enough to the income statement.
- Over the past month the share price has risen 17.6%, which puts fresh pressure on the earnings multiple to justify that kind of short term gain.
- The company is a key holding in a newly launched ETF focused on Korean chipmakers, which can support demand for the shares and may influence how investors think about the durability of its profit cycle.
- The analysts covering SK hynix have run their own numbers. See what analysts think SK hynix's shares could be worth.
The stock's next move may depend on whether the current share price can be explained by SK Hynix's earnings when set against the industry average.
For a broader sense of how SK hynix fits into the chip story, it can help to compare it with other 60 AI infrastructure stocks.
Is SK hynix a Bargain on Earnings?
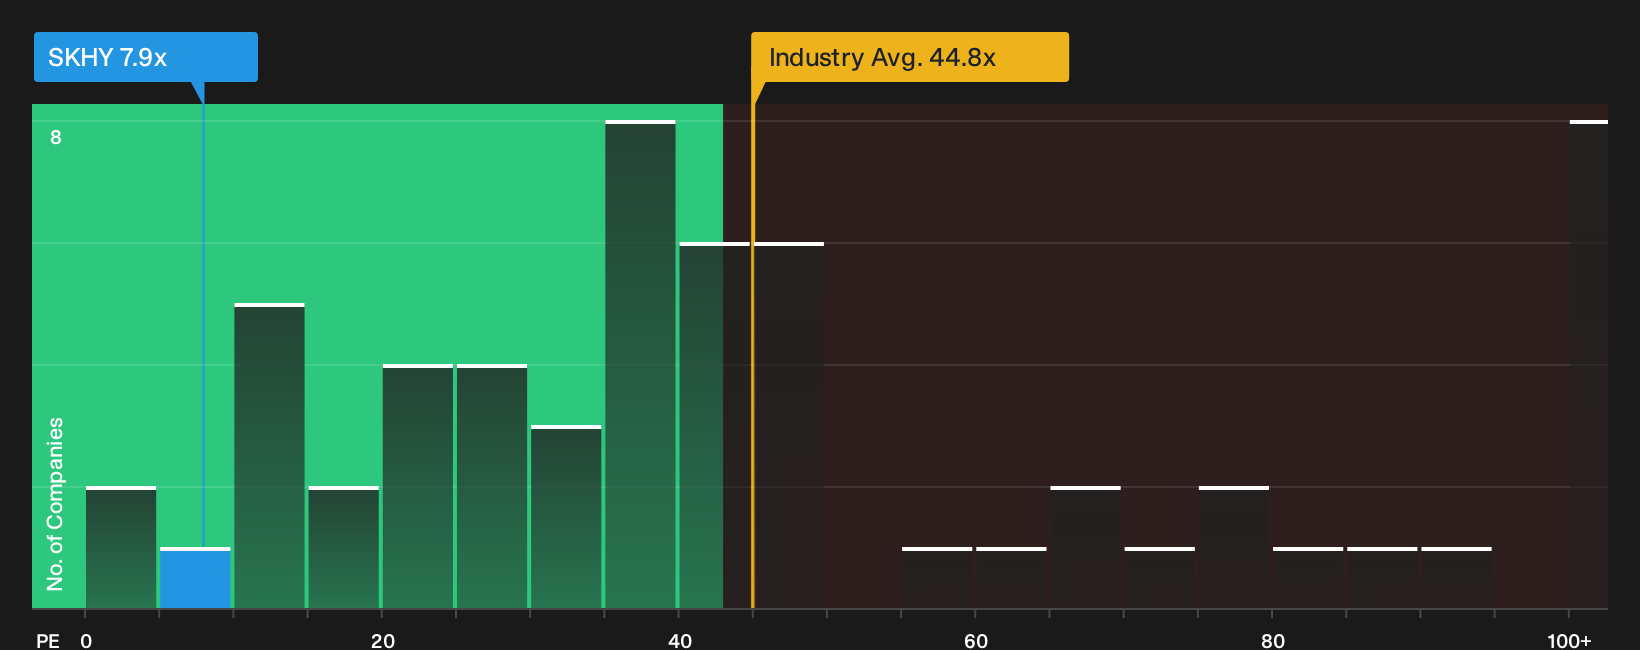
The P/E yardstick fits SK hynix because earnings are the main driver of how investors are framing its chip cycle story right now. On this measure, the stock trades on a P/E of 7.9x, which is far below the broader semiconductor sector average of about 44.8x. That is a steep gap for a large memory producer that plays a central role in Korea’s chip supply chain.
Because the new KCHP ETF is concentrating flows into Korea’s semiconductor leaders, some of that buying power is effectively coming in at what still screens as an undervalued multiple against peers on earnings. The discount to both the industry and the peer group, where the average P/E is roughly 57.6x, suggests the current price reflects a more cautious view of SK hynix’s profit stream than the typical chip stock. This is exactly what the earnings multiple is signaling. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for SK hynix leaves off, explaining in detail the potential paths for growth, profitability and earnings that would need to occur for the stock to be worth significantly more or less than it is today. Rather than ending with a single valuation result, they outline the future assumptions behind that number so you can track over time which expectations are being met and which are diverging on SK hynix's Community page.
A fresh, number driven Narrative on SK hynix gives you a single place to line up the chipmaker's current P/E, its role in the new KCHP ETF and recent KOSPI volatility with your own expectations. You can then see how those assumptions hold up as earnings reports and memory cycle data arrive. It turns headline stories about KCHP flows, index swings and broker targets into a set of explicit inputs that can be updated as actual results come through and sentiment on Korea's semiconductor sector shifts.
Share your own Narrative for SK hynix and set out the assumptions behind your valuation.
One more thing about SK hynix that could change the picture
Before lining up SK hynix purely on its P/E story, it is worth knowing that Simply Wall St’s broader checks have flagged specific areas of concern that some investors choose to weigh heavily. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com