
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Self Service Kiosk Launch Might Change The Case For Investing In Zebra Stock
- Zebra Technologies has launched the KC401 self-service kiosk, a 10 inch, IP65 sealed device designed to handle routine inquiries across retail, hospitality, manufacturing, and healthcare. It integrates with Zebra DNA software and existing CC6000 infrastructure.
- The KC401 and the broader Elo powered portfolio target a specific operational pain point. They are intended to free roughly the equivalent capacity of four store associates per retail location for higher value tasks such as merchandising and in store assistance.
- We will now look at how Zebra Technologies' KC401 self service focus could influence the broader investment narrative around automation.
Zebra Technologies Investment Narrative Recap
For Zebra Technologies, the big picture you need to buy into is straightforward. The business is aiming to turn decades of barcode, mobile computing and printer exposure into a broader automation platform that touches the front of store, the warehouse and the bedside. The KC401 launch fits that direction, but on its own it does not fundamentally change the near term earnings story.
The near term swing factor still sits in execution on hardware demand and the pace of shifting more revenue into software and services, set against a backdrop of softer regions like EMEA and high debt. The largest risk is that new Elo powered self service products add competitive pressure and price tension before cross selling, margin benefits and recurring software attach are clear in reported results.
The most relevant recent development alongside the KC401 is Zebra Technologies’ rollout with University Health, which put its mobile computers and printers deeper into inpatient workflows. That contract indicated that hospitals are willing to embed Zebra into mission critical routines where device downtime quickly becomes a patient care problem.
Putting the hospital deployment next to the KC401 kiosk story provides a clearer view of the potential catalyst path. Management is promoting the same automation thesis across healthcare, retail and industrial settings with more touchpoints, more devices and more software hooks. The potential benefit is greater workflow stickiness and a higher quality mix of recurring revenue over time, while the operational risk is that integration work, R&D spend and competitive pricing could pressure margins before any mix shift fully appears in cash generation.
What The KC401 Implies For Zebra Technologies’ Forecasts
Zebra Technologies' narrative projects US$7.2b revenue and US$991.3m earnings by 2029. This assumes 7.0% yearly revenue growth and requires an earnings increase of about US$452m from current earnings of US$539.0m.
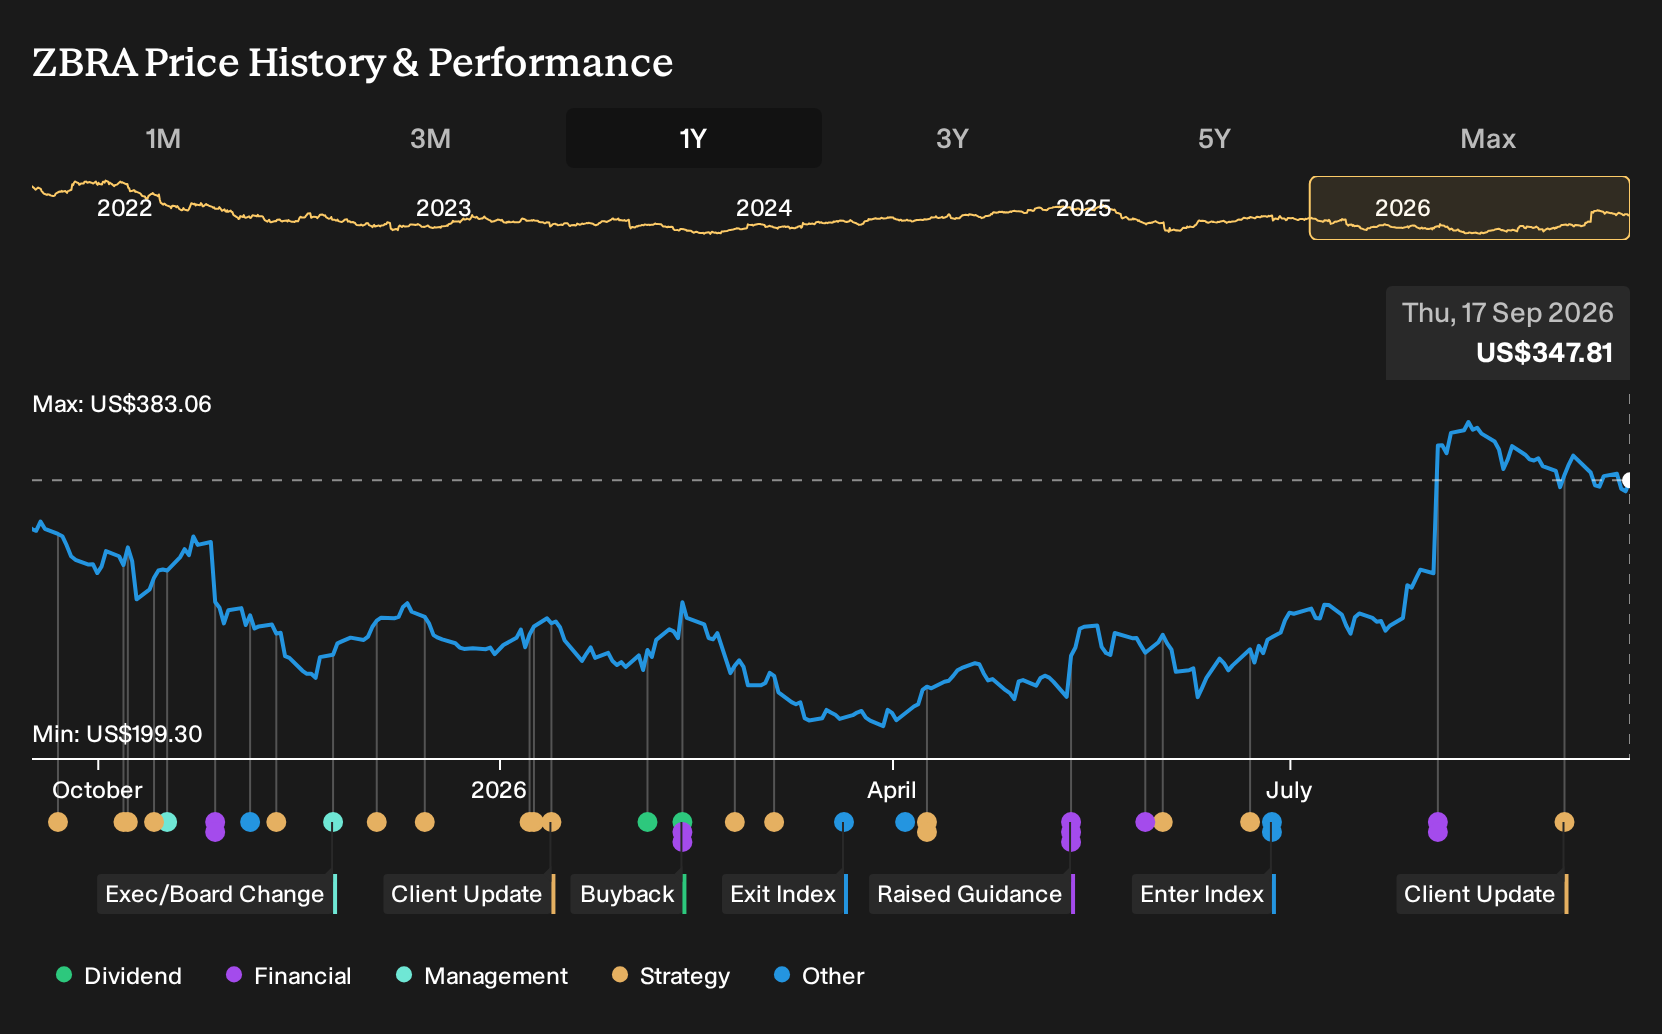
Learn how Zebra Technologies' fair value reflects a 15% potential price difference from its current level before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts already had a stronger automation story in mind for Zebra Technologies, with forecasts of US$7.3b revenue and US$1.1b earnings by 2029. You might read the KC401 launch as extra fuel for that view, even though those projections were set before this news and could still shift meaningfully.
Explore 4 other Zebra Technologies fair value estimates, including one that suggests as much as 53% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zebra Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zebra Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zebra Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Zebra Technologies?
If you want to stress test your thesis on Zebra Technologies, it helps to line it up against other opportunities using the same yardstick. The Simply Wall St Screener lets you filter for very specific traits, so you can compare like for like instead of guessing from headlines.
- If capital preservation is your first filter, start by scanning a group of 11 resilient stocks with low risk scores that pair resilience scores with fundamentals you can quantify.
- For investors hunting for potential mispricings, run a screen across 29 high quality undervalued stocks and see which businesses match your preferred balance of cash flows and balance sheet strength.
- Income focused readers can widen their watchlist by reviewing 6 dividend fortresses that combine higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com