
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UniFirst (UNF) Stock Looks Overvalued On A 60% Three Year Run
UniFirst has delivered strong multi year gains, and the recent share price level puts a spotlight on whether its earnings truly support where the stock trades today.
- The stock has returned 60.2% over the past 3 years. This raises the question of how much of that move is grounded in the underlying earnings power of the business.
- The company’s uniform rental and services model can translate contract wins and route density into earnings. The key issue is how efficiently those revenues convert into sustainable profits.
- The analysts covering UniFirst have run their own numbers. See what analysts think UniFirst's shares could be worth.
The issue now is whether UniFirst's current share price is justified by the earnings it generates today and what those profits may reasonably support over time.
To see how UniFirst's earnings-based story compares with other opportunities, it can help to line it up against companies filtered for 29 high quality undervalued stocks.
Is UniFirst Getting Expensive on Earnings?
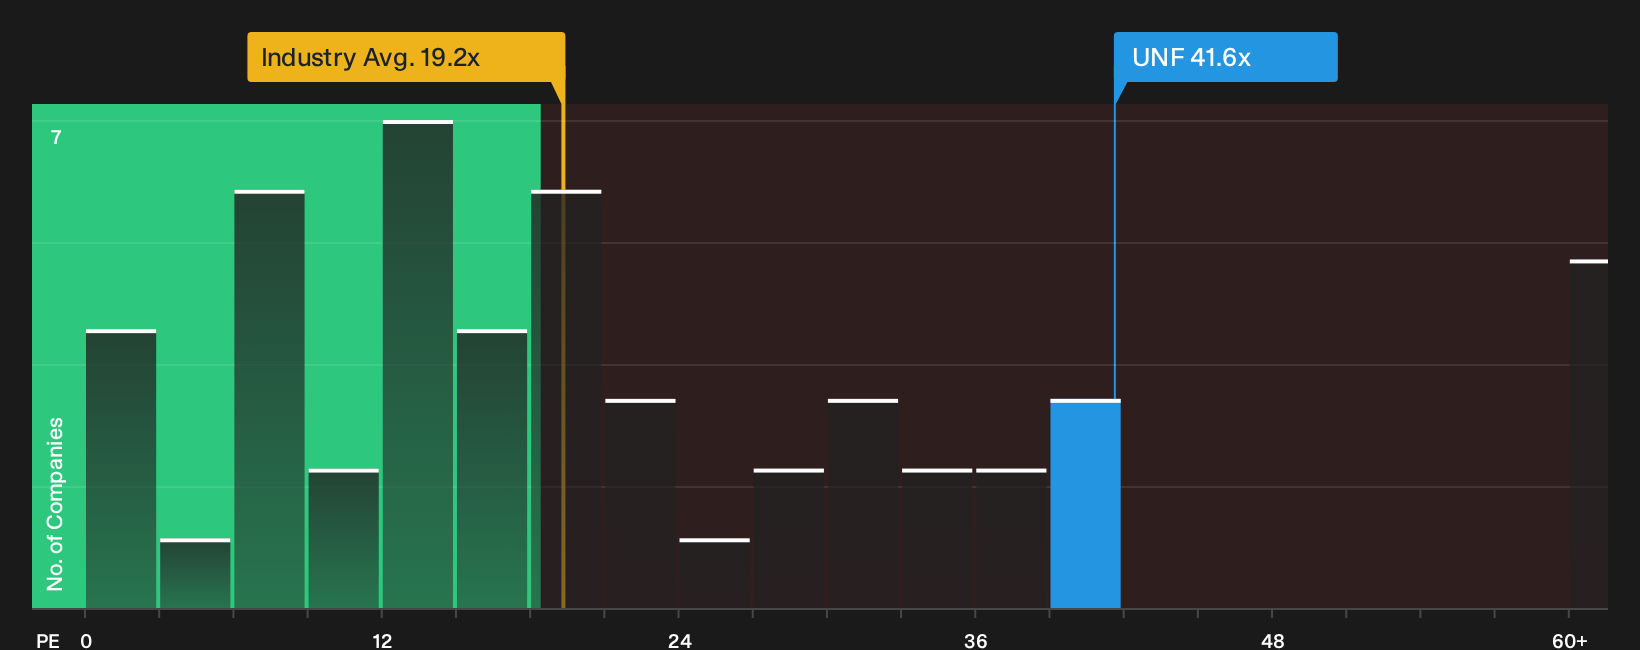
The P/E ratio suits UniFirst because earnings remain the key lens for a services outfit that depends heavily on route efficiency and long term contracts. Right now the stock trades on about 40.8x earnings, which is well above the Commercial Services sector average of roughly 19.2x and also higher than peers around 26.7x. That sets the bar quite high for what those profits need to justify.
A tailored fair value multiple for UniFirst that blends its growth profile, margins, industry and risk points to a lower P/E than where the shares currently change hands. The current 40.8x sits above that reference point, suggesting the market is attaching a premium that goes beyond what those fundamentals alone would imply. For anyone weighing the stock today, the key question is whether UniFirst can keep delivering the kind of earnings that make this richer P/E feel sustainable over time. Explore the numbers behind UniFirst's P/E valuation.
The UniFirst Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for UniFirst leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the shares to look meaningfully cheaper or richer than today’s quote on a fundamentals basis. Each narrative links its number to a clear view on how UniFirst's future expansion, margins and risk profile might evolve, giving you something concrete to test against new information over time.
Community views on UniFirst split between those who see extra upside in the story and those who think expectations already price in a lot.
Bull case: 7% undervalued
"Growth in First Aid and Safety Solutions, including the van business and recent bolt on acquisitions, is building a second revenue engine..."
Discover why this Narrative puts UniFirst at 7% undervalued.
Bear case: roughly fairly valued
"The push toward larger scale ERP and digital projects concentrates a lot of execution risk into the next 18 to 24 months..."
Explore why this Narrative puts UniFirst at roughly fairly valued.
One more UniFirst angle that can reshape how you see the stock
Price tags and earnings only tell part of the UniFirst story, because the people setting priorities, taking risks and deciding how cash is shared with shareholders are guided by their pay structure and track records. See who runs UniFirst and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com