
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How $2 Billion Share Sale Plan Will Impact Corning (GLW) Investors
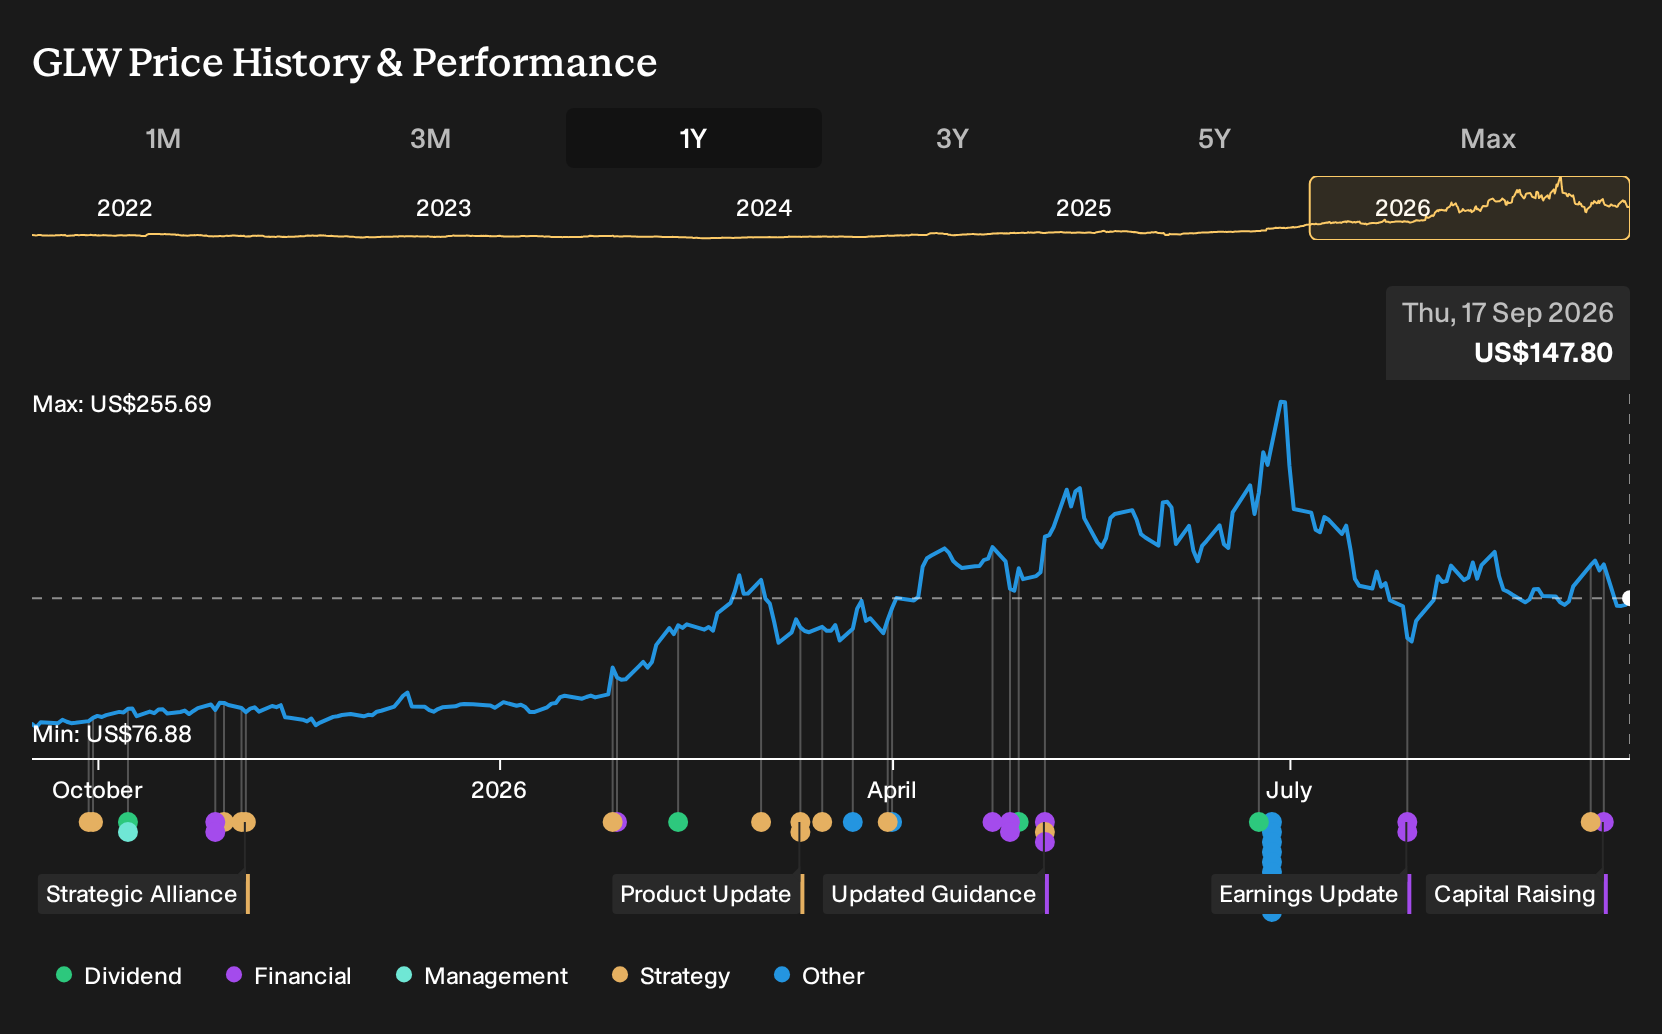
- Corning filed a US$2b at the market equity offering program on 11 September 2026, allowing it to sell new common shares over time through Goldman Sachs.
- The planned share issuance gives Corning added funding flexibility for AI focused optical projects and capacity expansions, while also raising investor questions about dilution and capital allocation priorities.
- We will now look at how Corning’s investment narrative is affected by this large at the market equity program.
Corning Investment Narrative Recap
To own Corning, you need to believe the Springboard plan in optical and solar translates into durable demand for its glass, fiber and materials portfolio, with AI data centers acting as a key leg. The US$2b at the market program gives Corning more room to fund that buildout. The near term swing factor is execution in Optical Communications, especially on AI related projects and capacity, while share issuance and existing debt keep balance sheet risk on the radar.
The biggest business risk is that secular themes like Gen AI and solar prove less supportive than expected, or macro pressure drags on spending for optical networks and automotive products, which could weigh on revenue and margins. Corning’s reliance on non GAAP metrics, tariff exposure and competitive pricing in core markets all add layers of uncertainty that equity financing alone does not resolve.
The SDM4 Multicore Fiber Multi Source Agreement looks most relevant here because it speaks directly to Corning’s AI infrastructure thesis. A defined four core multicore fiber specification for short reach links into data centers gives equipment makers a common technical target and gives Corning a clear product framework for its multicore fiber roadmap. That aligns neatly with the capital it now has the option to raise.
For you as a shareholder, the MSA does not guarantee orders, but it does reduce interoperability risk, which can be a real friction point in new optical architectures. It supports the idea that Corning’s AI opportunity is not just about one off contracts with hyperscalers, but about being part of an industry level standard that could underpin multi vendor deployments, while still leaving the business exposed to shifts in demand and pricing pressure.
Corning's current narrative outlines projected revenue of US$29.4b and earnings of US$5.5b by 2029. These figures are based on an assumed 20.1% annual revenue growth rate and an increase in earnings of about US$3.6b from the US$1.9b reported today.
Discover how Corning's fair value indicates a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Corning’s AI optical upside. They framed an alternate story where revenues reach about US$32.8b and earnings hit roughly US$6.9b by 2029, compared with the consensus US$29.4b and US$5.5b. Those projections were set before this SDM4 and equity news, so opinions may evolve.
Explore 7 other Corning fair value estimates, including one that suggests as much as 53% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Corning research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corning?
If this Corning story has you thinking about where else AI, cash flows and balance sheet strength might intersect, it can help to widen the lens and scan a broader set of opportunities with the Simply Wall St Screener.
- If capital preservation is high on your list, start with companies that score well on resilience by checking out the 11 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, focus on businesses that combine solid fundamentals with attractive pricing using the 29 high quality undervalued stocks.
- If you want income on top of potential price gains, filter for stocks with stronger yields and robust payout profiles through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com