
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Exelixis (EXEL) Stay Cheap After A 185% Five Year Run?
Exelixis has delivered a strong multi year share price run, and the question now is whether that move lines up with what the company earns today. With the stock recently closing at US$58.49, investors are increasingly asking if the earnings story is doing enough work to support that valuation.
- Over the past 5 years Exelixis has returned 185.3%, which puts real pressure on the current earnings base to justify where the stock now trades.
- The recent US FDA review extension for cancer drug candidate zanzalintinib and new milestone payments tied to the Adagene SAFEbody program can shift expectations around future profit timing and the durability of the company's earnings power.
- There is a second opinion on Exelixis worth weighing. See what analysts think Exelixis's shares could be worth.
The issue now is whether Exelixis' recent share price, and the gains baked into it, are well supported by the earnings the company is generating.
If you want a second reference point while you weigh Exelixis against its recent earnings run, it can help to scan a focused set of 29 high quality undervalued stocks.
Is Exelixis Still Cheap on Earnings?
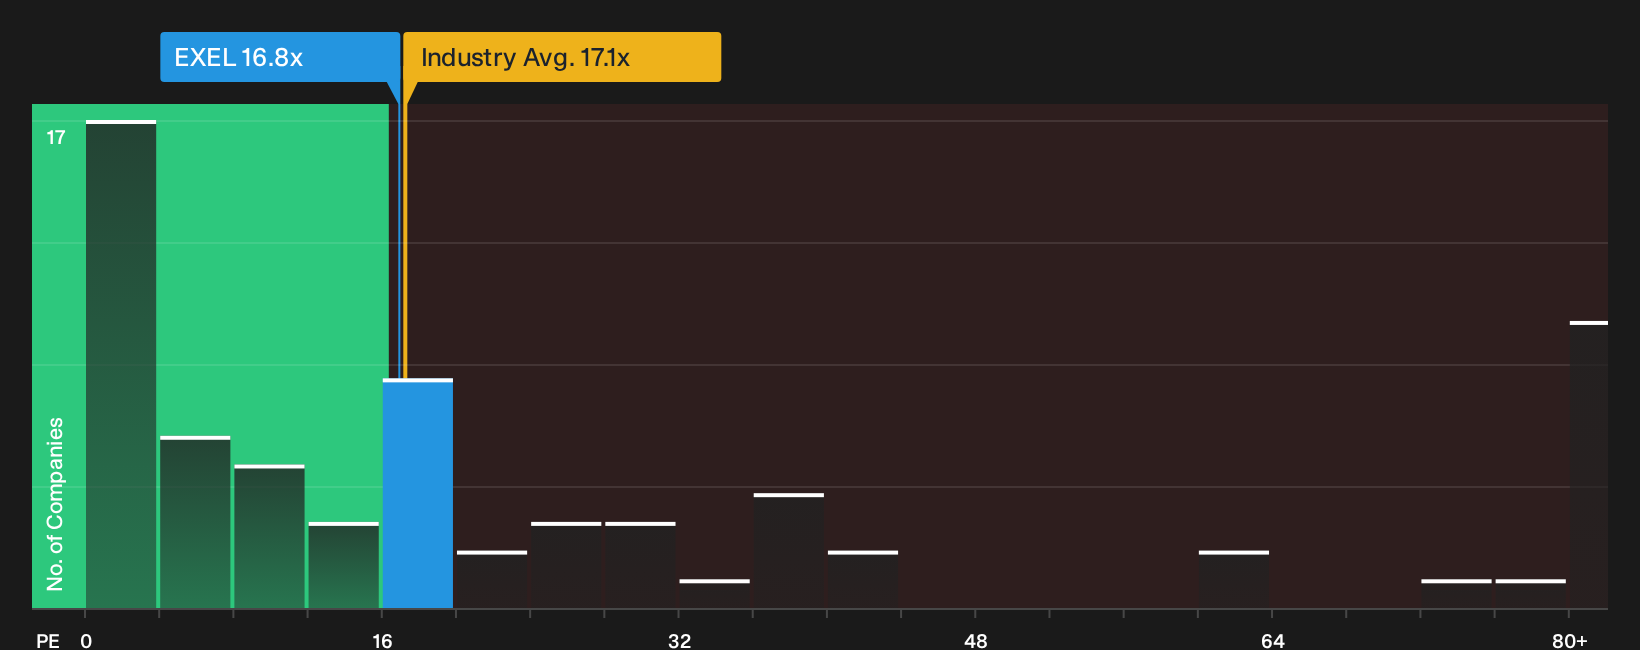
The P/E ratio suits Exelixis because the story here is firmly about earnings from commercialised oncology drugs rather than early stage pipeline optionality. On this lens, the stock trades on about 16.8x earnings, which is very close to the biotech industry average of roughly 17.1x and well below a peer group sitting around 80.6x. That gap to peers indicates the market is not treating Exelixis like the higher multiple biotech cohort that is more heavily priced on distant potential.
Against a tailored fair P/E that reflects Exelixis' own mix of margins, forecast growth, size and risk, the current 16.8x screens on the cheap side. Because the recent FDA review extension for zanzalintinib pulled sentiment back, the fact the shares still trade below that modelled level indicates the market is keeping a discount on the stock despite its earnings base. That leaves P/E pointing to Exelixis as undervalued on this framework, with the exact size of the gap coming into focus when you compare the current multiple with the detailed fair value work. Explore the numbers behind Exelixis's P/E valuation.
The Exelixis Narrative: What Would Justify Today's Price?
Exelixis' recent share price move raises a simple question for you as an investor: what would need to happen to future earnings for today’s valuation to look either stretched or conservative? Simply Wall St Narratives on the Community page turn that question into specific scenarios, with each tying its number to a concrete view on where Exelixis' growth, margins and risks might head next so you can revisit those assumptions as fresh information comes through.
Community views on Exelixis are split between those who see meaningful upside from the pipeline and those who think much of that promise is already reflected in the price.
Bull case: 11% undervalued
"The company's robust cash flow, substantial balance sheet, and active share repurchase program provide significant financial flexibility for opportunistic business development…"
Discover why this Narrative puts Exelixis at 11% undervalued.
Bear case: 10% overvalued
"Cabozantinib (CABOMETYX) remains the dominant revenue driver, with over 90% of total revenues still dependent on this single product…"
Explore why this Narrative puts Exelixis at 10% overvalued.
One more Exelixis check sits outside the current price story
Analyst projections for where Exelixis could be a few years from now offer a separate yardstick to compare against today’s earnings multiple, and that forward view can change how you read the current tag. Explore where analysts expect Exelixis to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com