
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Alkermes (ALKS) Adds A Veteran Director, Is The Stock Still Undervalued?
Alkermes (ALKS) has drawn fresh attention after appointing veteran biopharma executive Anne C. Whitaker to its board. The move expands the director group to eleven and adds extensive commercial and operational experience.
Alkermes has had a strong run into 2026, with a year to date share price return of 65.29% and a 1 year total shareholder return of 63.61%. However, the 30 day share price return of 5.60% suggests some momentum has cooled, even as the board refresh signals that investors are reassessing the risk and growth profile around the current US$46.71 share price.
Spot opportunities beyond Alkermes by scanning a curated 16 high quality undiscovered gems with fundamentals that may not yet be fully reflected in their share prices.Alkermes now pairs a broad neurological and psychiatry portfolio with fresh boardroom expertise. The real tension is whether that mix is already fully captured in a US$46.71 share price or still leaves room based on valuation.
Most Popular Narrative: 16.6% Undervalued
Against Alkermes' last close of $46.71, the most followed narrative pegs fair value at $56, which frames the stock as modestly undervalued while putting real weight on the orexin and neuroscience portfolio to carry a heavier load over time.
Results from the Vibrance 1 Phase II study and the expanding orexin agonist pipeline reduce perceived risk in the company's long-term R&D strategy and open avenues to additional addressable disorders beyond narcolepsy, highlighting potential for future multi-indication revenue streams pending successful late-stage trials and commercialization.
See why 9 investors see Alkermes as 17% undervalued.
Result: Fair Value of $56 (UNDERVALUED)
Still, the Alkermes story can change quickly if orexin trial data disappoints or if rising R&D and integration spending keep GAAP losses wider for longer.
Find out about the key risks to this Alkermes narrative.
Another View: Alkermes Through The P/E Lens
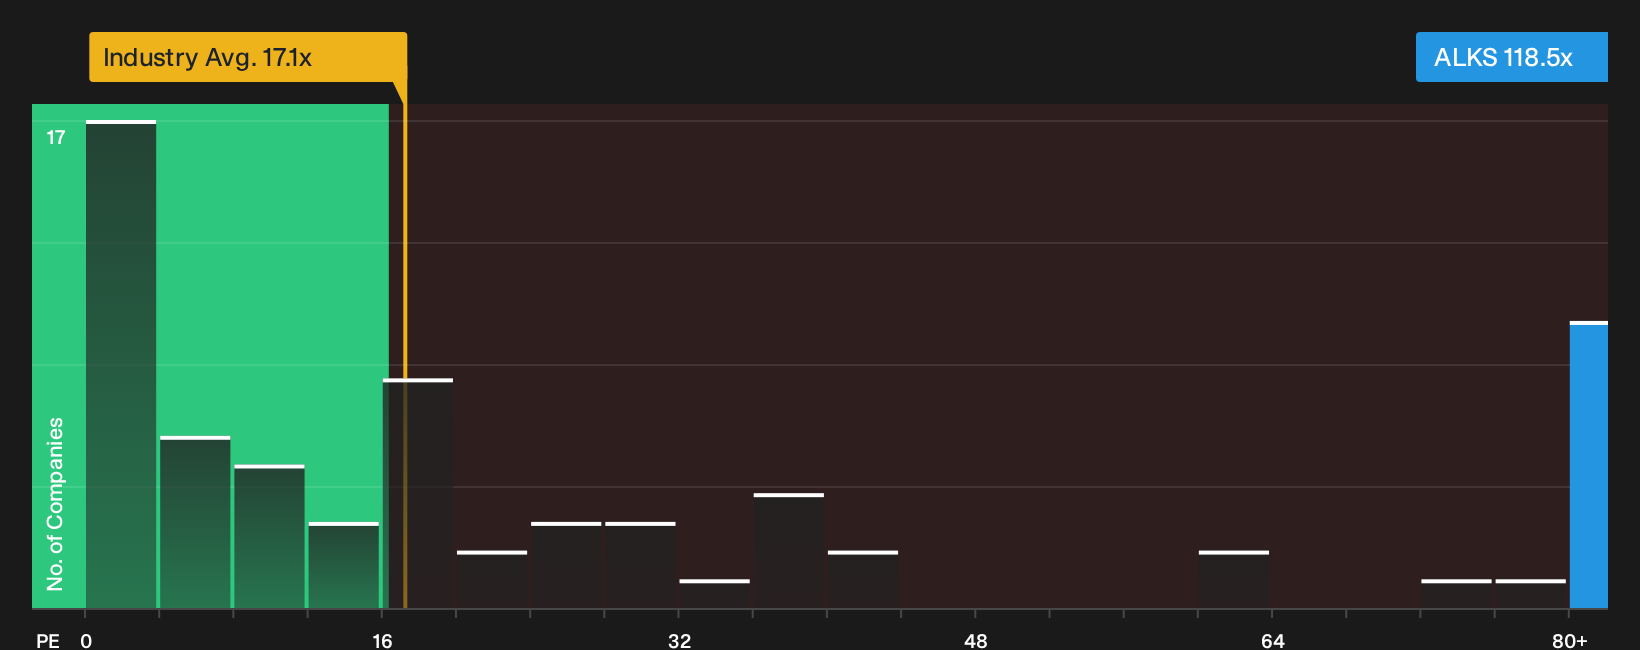
The SWS DCF model points to Alkermes trading 50.2% below an estimated future cash flow value of $93.72, which supports the underpriced narrative around $46.71. Yet the current P/E of 118.5x versus a fair ratio of 40.2x and a US Biotechs average of 17.1x signals a very rich earnings multiple. Which signal do you trust more when real cash flows eventually need to justify both stories?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Alkermes so far. If this feels finely balanced, move quickly to test the data yourself and weigh both sides of the argument through 2 key rewards and 3 important warning signs.
Looking for more Alkermes style investment ideas?
If Alkermes has you thinking more broadly about opportunity, do not stop here. The right watchlist can reshape how you spot potential before the crowd.
- Target resilient cash generators by screening a list of solid balance sheet and fundamentals (23 results) that prioritises financial strength and durable fundamentals.
- Spot potential mispricings early by running a 29 high quality undervalued stocks that filters for quality businesses trading below intrinsic estimates.
- Dial down portfolio swings by focusing on a 11 resilient stocks with low risk scores that highlights companies with more stable risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com