
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NICE Stock In Focus After Major CXone Client Wins
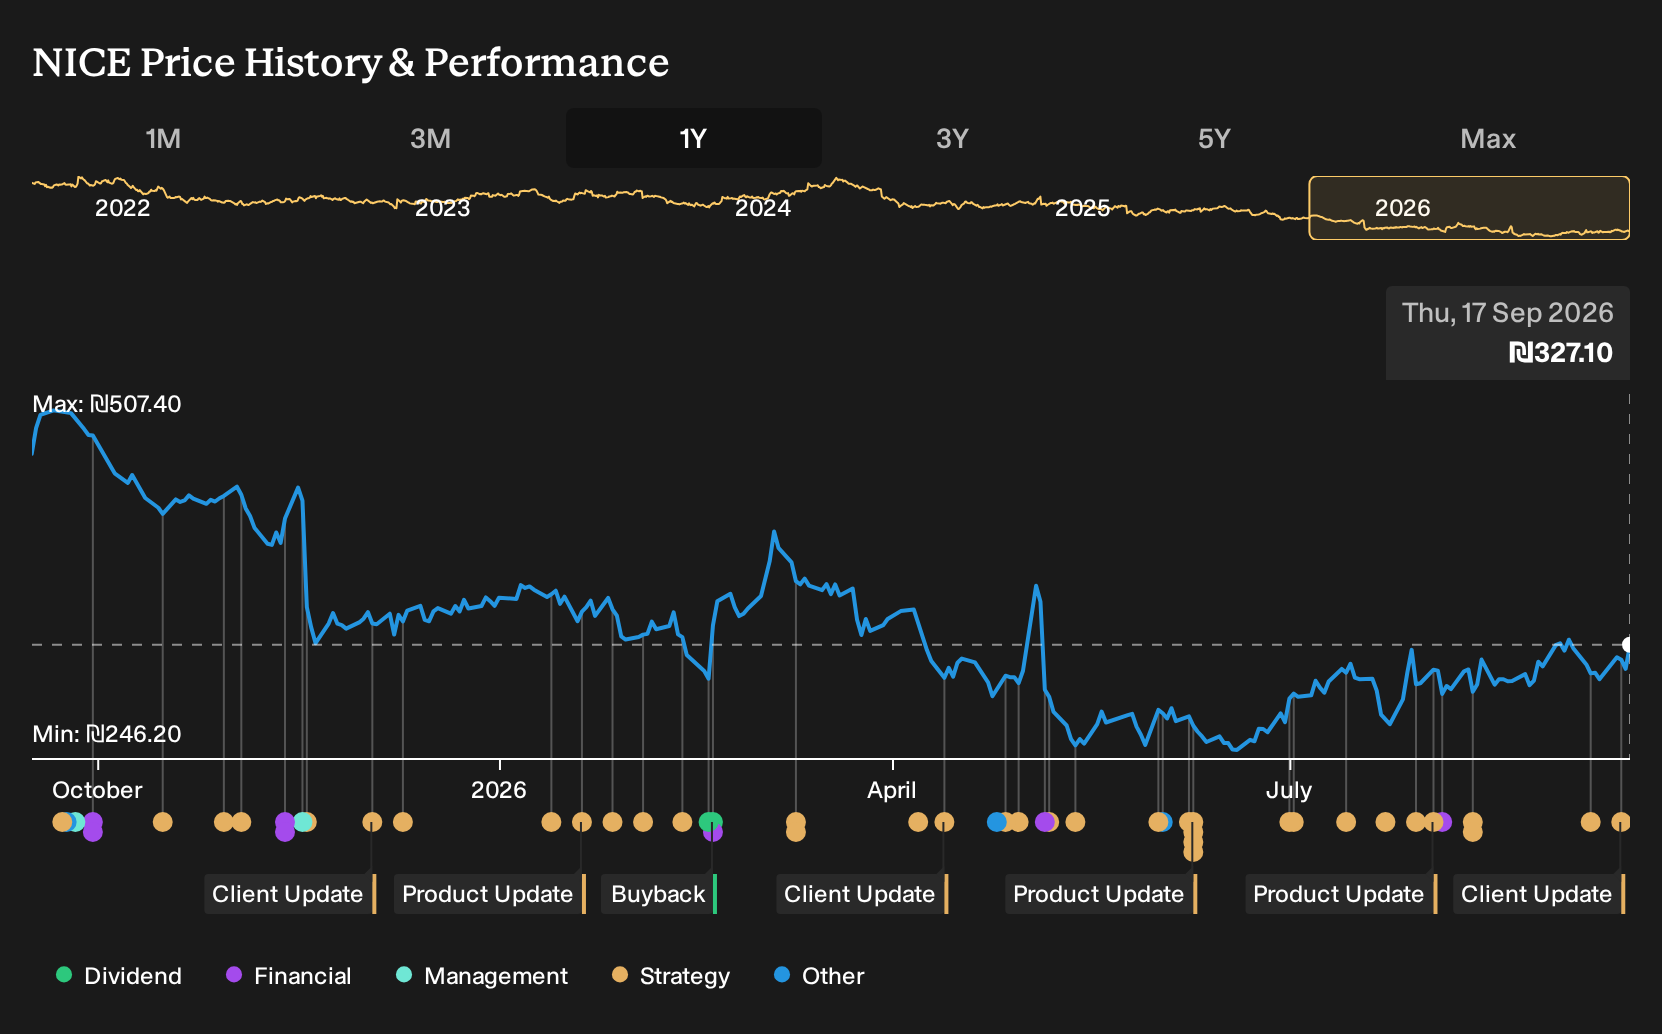
- Merlin Entertainments and AOK PLUS previously announced large scale deployments of NICE CXone and Cognigy to handle millions of AI supported interactions, reporting higher satisfaction scores, stronger issue resolution, and high call acceptance rates.
- These client wins show NICE embedded in critical service infrastructure, with CXone orchestrating both automated and employee supported journeys at meaningful volume across sectors.
- We will now see how this traction for NICE CXone with high volume clients could influence the investment narrative around recurring cloud demand.
Scan beyond NICE and size up other contact centre and automation plays using a curated set of 131 AI small caps that are already turning heavy interaction volumes into AI driven customer experiences.
NICE Investment Narrative Recap
NICE appeals to shareholders who see potential in AI driven customer experience platforms and are comfortable with near term margin pressure from cloud and global expansion. The key short term catalyst remains evidence that these AI and CXone deployments translate into durable, high quality recurring revenue and better utilization of the existing cost base.
The biggest risk remains heavy investment and complex, multi year enterprise rollouts that may take longer to translate into cleaner profitability, particularly given churn issues in acquired units and evolving AI regulation. The Merlin and AOK PLUS news supports the broader narrative but does not fundamentally change this risk balance at this time.
The AOK PLUS deployment looks particularly relevant. It shows NICE handling more than 5 million annual interactions in a tightly regulated public health setting while integrating AI self service, routing across 2,400 employees, and 120 skills on a single CXone and Cognigy foundation. For an investor, that is a real world test of scale, reliability, and implementation capability.
That type of reference account speaks directly to the main catalyst investors are monitoring. Large, complex clients adopting NICE for sovereign cloud and AI orchestration can support the case for sustained cloud ARR and better customer lifetime value. At the same time, these projects also underscore execution risk if similar deployments were to be delayed, overrun on cost, or encounter regulatory friction.
NICE's current earnings sit at US$529.6 million, with analysts forecasting consensus earnings of US$638.7 million by 2029 and modeling revenues of US$4.0b for that same year. This implies revenue growth of 9.8% per year and an earnings increase of about 21% from earnings today.
Uncover how NICE's fair value indicates a 90% potential upside to its current price before sentiment around AI customer experience platforms shifts.
Exploring Other Perspectives
The Simply Wall St Community currently shows only 2 fair value views for NICE, clustered between about US$621 and US$735 per share, which already signals a wide gap for such a small sample. Before the recent Merlin and AOK PLUS wins, these investors were weighing margin pressure, acquisition churn, and AI regulation. Use those contrasts to pressure test your own thesis and explore more community viewpoints.
Explore another NICE fair value estimate, including one that suggests as much as 125% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis.
- A great starting point for your NICE research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NICE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NICE's overall financial health at a glance.
Looking For More Investment Ideas Beyond NICE?
Once you have a handle on NICE, you can broaden your watchlist using the Simply Wall St Screener to spot other opportunities that fit your style, risk tolerance, and income needs.
- If capital preservation comes first for you, focus on stability by reviewing 104 resilient stocks with low risk scores that aim to keep drawdowns more contained.
- If balance sheet strength matters most, zero in on resilience by scanning a list of solid balance sheet and fundamentals (196 results) that can better absorb shocks and fund growth internally.
- If you want businesses the wider market may have overlooked, hunt for mispriced potential across a 618 high quality undiscovered gems with strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com