
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Reddit (RDDT) Be Priced For Perfection After Strong Earnings?
Reddit has delivered rapid revenue growth and upbeat earnings news, yet the share price is still down sharply over the past year. That mix of strong recent headlines and a weaker stock chart raises a simple question for investors who follow Reddit stock: whether today's market value lines up with what the company currently earns.
- The share price has fallen 43.5% over the past year, which puts the focus squarely on whether Reddit's earnings profile can support the valuation that remains.
- Recent earnings news highlighted fast revenue expansion and stronger profitability expectations, which can shape how investors think about the durability and timing of future earnings streams.
- Your read on Reddit is one view; the desks covering it have another. See what analysts think Reddit's shares could be worth.
The stock's next move may depend on whether Reddit's current earnings are enough to justify the price investors are paying today.
If you want a wider lens on social networking and media valuations beyond Reddit, compare its recent swings with companies in the 29 high quality undervalued stocks
Is Reddit Getting Expensive on Earnings?
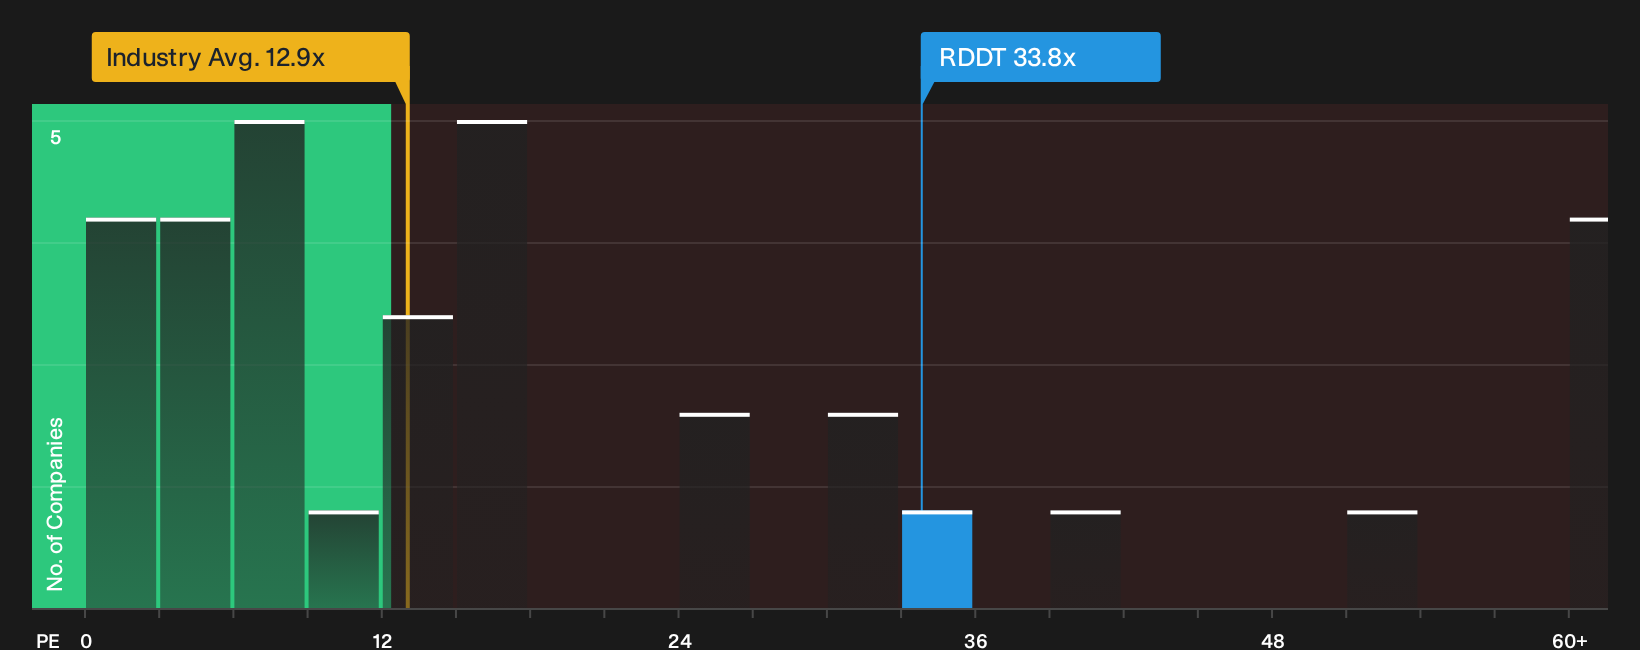
The P/E ratio fits Reddit because earnings are now a key reference point for how investors price the stock. Reddit trades on roughly 33.8x earnings, which is higher than both the interactive media industry average of about 12.9x and a peer group closer to 28.4x. For a reader, that gap means you are paying a richer price for each dollar of profit than is typical in this corner of the market.
The valuation model that blends Reddit's growth profile, margins, size and risk suggests a lower earnings multiple would be more in line with its fundamentals, so the current 33.8x points to the shares looking overvalued on this framework. Because Reddit just posted the fastest revenue growth and strongest guidance lift in its social networking group, the market clearly assigns a premium for that momentum. Yet the P/E already builds in a lot of optimism if those conditions change or simply level off. The key question is whether you think Reddit can keep converting that revenue base into profits that grow fast enough to make this premium multiple feel routine rather than demanding. Explore the numbers behind Reddit's P/E valuation.
The Reddit Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take the P/E puzzle around Reddit and turn it into a set of explicit paths that show what would need to happen to growth, margins and earnings for the stock to be worth much more or meaningfully less than it is today. Rather than leaning on a single multiple or one model result, each narrative lays out the assumptions behind its estimate of Reddit's worth so you can compare those inputs with actual results as they arrive. Narratives sit on Simply Wall St's Community page, so you can read them alongside broader discussion of Reddit's trajectory.
Reddit followers are splitting into two clear camps on valuation, with one group seeing a steep discount and another arguing expectations are still too rich.
Bull case: 64% undervalued
"Reddit is trading 67.8% below my certified fair value. That is not a green light. It is a case to work…"
Discover why this Narrative puts Reddit at 64% undervalued.
Bear case: 14% overvalued
"Regulatory scrutiny and content moderation demands are driving up compliance costs and restricting data monetization, squeezing net margins and profitability…"
Explore why this Narrative puts Reddit at 14% overvalued.
One more piece on Reddit before you make a move
Everything here has focused on what Reddit looks like today, yet there is a separate set of clues in how professional forecasters map out the business a few years from now. Explore where analysts expect Reddit to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com